S.Amdt. 164
What it does: Adds SEC. 641. MODIFICATION OF FUNDING REQUIREMENTS FOR CERTAIN PLANS wherever appropriate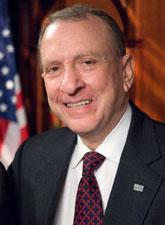 Sen. Arlen Specter (R-PA)
What it changes
1 change to H.J.Res. 2
Adds SEC. 641. MODIFICATION OF FUNDING REQUIREMENTS FOR CERTAIN PLANS wherever appropriate
Adds a sectionInserted: SEC. 641. MODIFICATION OF FUNDING REQUIREMENTS FOR CERTAIN PLANS.
Inserted: (a) Funding Rules for Certain Plans.--
Inserted: (1) In general.--Notwithstanding any other provision of the Internal Revenue Code of 1986 or the Employee Retirement Income Security Act of 1974, the minimum funding rules under paragraph (2) shall apply for any plan year beginning after December 31, 2002, in the case of a defined benefit plan which--
Inserted: (A) was established by an air carrier which was granted a conditional loan guarantee by the Air Transport Stabilization Board on July 10, 2002, and which filed for protection under chapter 11 of title 11, United States Code, on August 11, 2002, and
Inserted: (B) is maintained for the benefit of such carrier's employees pursuant to a collective bargaining agreement.
Inserted: (2) Special funding rule.--
Inserted: (A) In general.--In the case of a plan described in paragraph (1), the minimum funding requirements under this paragraph shall be the requirements set forth in Treasury Regulation section 1.412(c)(1)-3 (as in effect on the date of the enactment of this section).
Inserted: (B) Rules of special application.--In applying the requirements of Treasury Regulation section 1.412(c)(1)-3 for purposes of paragraph (1)--
Inserted: (i) the plan shall be treated as having met the requirements of Treasury Regulation section 1.412(c)(1)-3(a)(2),
Inserted: (ii) the payment schedules shall be determined--
Inserted: (I) by using the maximum amortization period permitted under section 1.412(c)(1)-3, and
Inserted: (II) on the basis of the actuarial valuation of the accrued liability and the current liability of the plan as of January 1, 2003, less the actuarial value of the plan assets on that date,
Show 3 more inserted paragraphsShow less
Inserted: (iii) the payments under a restoration payment schedule shall be made in level amounts over the payment period, and
Inserted: (iv) the actuarial value of assets shall be the fair market value of such assets as of January 1, 2003, with prospective investment returns in excess of or less than the assumed return phased in over 5 years.
Inserted: (b) Effective Date.--The amendments made by this section shall apply to plan years beginning after December 31, 2002.
The amendment doesn't say where this goes; the clerk decides.
Original wording
At the appropriate place, insert:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 164. Mr. SPECTER submitted an amendment intended to be proposed by him to the joint resolution H.J. Res. 2, making further continuing appropriations for the fiscal year 2003, and for other purposes; which was ordered to lie on the table; as follows:
At the appropriate place, insert:
SEC. 641. MODIFICATION OF FUNDING REQUIREMENTS FOR CERTAIN PLANS.
(a) Funding Rules for Certain Plans.--
(1) In general.--Notwithstanding any other provision of the Internal Revenue Code of 1986 or the Employee Retirement Income Security Act of 1974, the minimum funding rules under paragraph (2) shall apply for any plan year beginning after December 31, 2002, in the case of a defined benefit plan which--
(A) was established by an air carrier which was granted a conditional loan guarantee by the Air Transport Stabilization Board on July 10, 2002, and which filed for protection under chapter 11 of title 11, United States Code, on August 11, 2002, and
(B) is maintained for the benefit of such carrier's employees pursuant to a collective bargaining agreement.
(2) Special funding rule.--
(A) In general.--In the case of a plan described in paragraph (1), the minimum funding requirements under this paragraph shall be the requirements set forth in Treasury Regulation section 1.412(c)(1)-3 (as in effect on the date of the enactment of this section).
(B) Rules of special application.--In applying the requirements of Treasury Regulation section 1.412(c)(1)-3 for purposes of paragraph (1)--
(i) the plan shall be treated as having met the requirements of Treasury Regulation section 1.412(c)(1)-3(a)(2),
(ii) the payment schedules shall be determined--
(I) by using the maximum amortization period permitted under section 1.412(c)(1)-3, and
(II) on the basis of the actuarial valuation of the accrued liability and the current liability of the plan as of January 1, 2003, less the actuarial value of the plan assets on that date,
(iii) the payments under a restoration payment schedule shall be made in level amounts over the payment period, and
(iv) the actuarial value of assets shall be the fair market value of such assets as of January 1, 2003, with prospective investment returns in excess of or less than the assumed return phased in over 5 years.
(b) Effective Date.--The amendments made by this section shall apply to plan years beginning after December 31, 2002.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
January 21, 2003