S.Amdt. 3032
What it does: Rewrites page 85, line 20 through page 146, line 23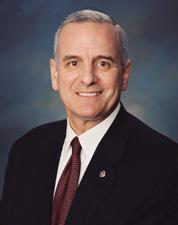 Sen. Mark Dayton (D-MN)
What it changes
1 change to S. 1637
Rewrites page 85, line 20 through page 146, line 23
ReplacesPrinted pageRemoves page 85, line 20 through page 146, line 23 of the printed bill. See that page
Inserted: SEC. 201. DETERMINATION OF FOREIGN PERSONAL HOLDING COMPANY INCOME WITH RESPECT TO TRANSACTIONS IN COMMODITIES.
Inserted: (a) In General.--Clauses (i) and (ii) of section 954(c)(1)(C) (relating to commodity transactions) are amended to read as follows:
Inserted: "(i) arise out of commodity hedging transactions (as defined in paragraph (4)(A)),
Inserted: "(ii) are active business gains or losses from the sale of commodities, but only if substantially all of the controlled foreign corporation's commodities are property described in paragraph (1), (2), or (8) of section 1221(a), or".
Inserted: (b) Definition and Special Rules.--Subsection (c) of section 954 is amended by adding after paragraph (3) the following new paragraph:
Inserted: "(4) Definition and special rules relating to commodity transactions.--
Inserted: "(A) Commodity hedging transactions.--For purposes of paragraph (1)(C)(i), the term 'commodity hedging transaction' means any transaction with respect to a commodity if such transaction--
Inserted: "(i) is a hedging transaction as defined in section 1221(b)(2), determined--
Inserted: "(I) without regard to subparagraph (A)(ii) thereof,
Inserted: "(II) by applying subparagraph (A)(i) thereof by substituting 'ordinary property or property described in section 1231(b)' for 'ordinary property', and
Inserted: "(III) by substituting 'controlled foreign corporation' for 'taxpayer' each place it appears, and
Inserted: "(ii) is clearly identified as such in accordance with section 1221(a)(7).
Show 4 more inserted paragraphsShow less
Inserted: "(B) Treatment of dealer activities under paragraph (1)(C).--Commodities with respect to which gains and losses are not taken into account under paragraph (2)(C) in computing a controlled foreign corporation's foreign personal holding company income shall not be taken into account in applying the substantially all test under paragraph (1)(C)(ii) to such corporation.
Inserted: "(C) Regulations.--The Secretary shall prescribe such regulations as are appropriate to carry out the purposes of paragraph (1)(C) in the case of transactions involving related parties.".
Inserted: (c) Modification of Exception for Dealers.--Clause (i) of section 954(c)(2)(C) is amended by inserting "and transactions involving physical settlement" after "(including hedging transactions".
Inserted: (d) Effective Date.--The amendments made by this section shall apply to transactions entered into after December 31, 2004.
Original wording
Beginning on page 85, line 20, strike all through page 146, line 23, and insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 3032. Mr. DAYTON submitted an amendment intended to be proposed by him to the bill S. 1637, to amend the Internal Revenue Code of 1986 to comply with the World Trade Organization rulings on the FSC/ETI benefit in a manner that preserves jobs and production activities in the United States, to reform and simplify the international taxation rules of the United States, and for other purposes; which was ordered to lie on the table; as follows:
Beginning on page 85, line 20, strike all through page 146, line 23, and insert the following:
SEC. 201. DETERMINATION OF FOREIGN PERSONAL HOLDING COMPANY INCOME WITH RESPECT TO TRANSACTIONS IN COMMODITIES.
(a) In General.--Clauses (i) and (ii) of section 954(c)(1)(C) (relating to commodity transactions) are amended to read as follows:
“(i) arise out of commodity hedging transactions (as defined in paragraph (4)(A)),
“(ii) are active business gains or losses from the sale of commodities, but only if substantially all of the controlled foreign corporation's commodities are property described in paragraph (1), (2), or (8) of section 1221(a), or”.
(b) Definition and Special Rules.--Subsection (c) of section 954 is amended by adding after paragraph (3) the following new paragraph:
“(4) Definition and special rules relating to commodity transactions.--
“(A) Commodity hedging transactions.--For purposes of paragraph (1)(C)(i), the term ‘commodity hedging transaction' means any transaction with respect to a commodity if such transaction--
“(i) is a hedging transaction as defined in section 1221(b)(2), determined--
“(I) without regard to subparagraph (A)(ii) thereof,
“(II) by applying subparagraph (A)(i) thereof by substituting ‘ordinary property or property described in section 1231(b)' for ‘ordinary property', and
“(III) by substituting ‘controlled foreign corporation' for ‘taxpayer' each place it appears, and
“(ii) is clearly identified as such in accordance with section 1221(a)(7).
“(B) Treatment of dealer activities under paragraph (1)(C).--Commodities with respect to which gains and losses are not taken into account under paragraph (2)(C) in computing a controlled foreign corporation's foreign personal holding company income shall not be taken into account in applying the substantially all test under paragraph (1)(C)(ii) to such corporation.
“(C) Regulations.--The Secretary shall prescribe such regulations as are appropriate to carry out the purposes of paragraph (1)(C) in the case of transactions involving related parties.”.
(c) Modification of Exception for Dealers.--Clause (i) of section 954(c)(2)(C) is amended by inserting “and transactions involving physical settlement” after “(including hedging transactions”.
(d) Effective Date.--The amendments made by this section shall apply to transactions entered into after December 31, 2004.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
April 6, 2004