To make certain engineering and architectural services eligible for the deduction relating to income attributable to United States production activities and to limit an employer's deduction for entertainment expenses of covered employees to the amount which the employee includes in income.
What it does: Adds SEC. 103. DEDUCTION FOR UNITED STATES PRODUCTION ACTIVITIES INCLUDES INCOME RELATED TO CERTAIN ARCHITECTURAL AND ENGINEERING SERVICES on page 35, between lines 11 and 12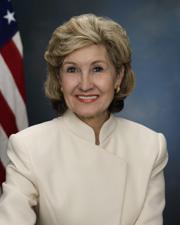 Sen. Kay Bailey Hutchison (R-TX)
Adds SEC. 103. DEDUCTION FOR UNITED STATES PRODUCTION ACTIVITIES INCLUDES INCOME RELATED TO CERTAIN ARCHITECTURAL AND ENGINEERING SERVICES on page 35, between lines 11 and 12
Adds a sectionPrinted pageInserted: SEC. 103. DEDUCTION FOR UNITED STATES PRODUCTION ACTIVITIES INCLUDES INCOME RELATED TO CERTAIN ARCHITECTURAL AND ENGINEERING SERVICES.
Inserted: (a) In General.--Paragraph (1) of section 199(e) (relating to domestic production gross receipts), as added by section 102, is amended to read as follows:
Inserted: "(1) In general.--
Inserted: "(A) Receipts from qualifying production property.--The term 'domestic production gross receipts' means the gross receipts of the taxpayer which are derived from--
Inserted: "(i) any sale, exchange, or other disposition of, or
Inserted: "(ii) any lease, rental, or license of, qualifying production property which was manufactured, produced, grown, or extracted in whole or in significant part by the taxpayer within the United States.
Inserted: "(B) Receipts from certain services.--
Inserted: "(i) In general.--Such term also includes the applicable percentage of gross receipts of the taxpayer which are derived from any engineering or architectural services performed in the United States for construction projects in the United States.
Inserted: "(ii) Applicable percentage.--For purposes of clause (i), the applicable percentage shall be determined under the following table:
Inserted: "In the case of any taxable year beginniThe applicable percentage is--
Inserted: 2004, 2005, 2006, 2007, or 2008...............................25 ....
Inserted: 2009, 2010, 2011, or 2012.....................................50 ....
Show 8 more inserted paragraphsShow less
Inserted: 2013 or thereafter...........................................100.....
Inserted: (b) Limitation of Employer Deduction for Certain Entertainment Expenses With Respect to Covered Employees.--Paragraph (2) of section 274(e) (relating to expenses treated as compensation) is amended to read as follows:
Inserted: "(2) Expenses treated as compensation.--Expenses for goods, services, and facilities--
Inserted: "(A) in the case of a covered employee (within the meaning of section 162(m)(3)), to the extent that the expenses do not exceed the amount of the expenses treated by the taxpayer, with respect to the recipient of the entertainment, amusement, or recreation, as compensation to such covered employee on the taxpayer's return of tax under this chapter and as wages to such covered employee for purposes of chapter 24 (relating to withholding of income tax at source on wages), and
Inserted: "(B) in the case of any other employee, to the extent that the expenses are treated by the taxpayer, with respect to the recipient of the entertainment, amusement, or recreation, as compensation to such employee on the taxpayer's return of tax under this chapter and as wages to such employee for purposes of chapter 24 (relating to withholding of income tax at source on wages).".
Inserted: (c) Effective Dates.--
Inserted: (1) Subsection (a).--The amendment made by subsection (a) shall apply to taxable years ending after the date of the enactment of this Act, and section 15 of the Internal Revenue Code of 1986 shall apply to the amendment made by this subsection as if it were a change in the rate of tax.
Inserted: (2) Subsection (b).--The amendment made by subsection (b) shall apply to expenses incurred after the date of the enactment of this Act and before January 1, 2006.
Original wording
On page 35, between lines 11 and 12, insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
On page 35, between lines 11 and 12, insert the following:
SEC. 103. DEDUCTION FOR UNITED STATES PRODUCTION ACTIVITIES INCLUDES INCOME RELATED TO CERTAIN ARCHITECTURAL AND ENGINEERING SERVICES.
(a) In General.--Paragraph (1) of section 199(e) (relating to domestic production gross receipts), as added by section 102, is amended to read as follows:
“(1) In general.--
“(A) Receipts from qualifying production property.--The term ‘domestic production gross receipts' means the gross receipts of the taxpayer which are derived from--
“(i) any sale, exchange, or other disposition of, or
“(ii) any lease, rental, or license of, qualifying production property which was manufactured, produced, grown, or extracted in whole or in significant part by the taxpayer within the United States.
“(B) Receipts from certain services.--
“(i) In general.--Such term also includes the applicable percentage of gross receipts of the taxpayer which are derived from any engineering or architectural services performed in the United States for construction projects in the United States.
“(ii) Applicable percentage.--For purposes of clause (i), the applicable percentage shall be determined under the following table:
“In the case of any taxable year beginniThe applicable percentage is--
2004, 2005, 2006, 2007, or 2008...............................25 ....
2009, 2010, 2011, or 2012.....................................50 ....
2013 or thereafter...........................................100.....
(b) Limitation of Employer Deduction for Certain Entertainment Expenses With Respect to Covered Employees.--Paragraph (2) of section 274(e) (relating to expenses treated as compensation) is amended to read as follows:
“(2) Expenses treated as compensation.--Expenses for goods, services, and facilities--
“(A) in the case of a covered employee (within the meaning of section 162(m)(3)), to the extent that the expenses do not exceed the amount of the expenses treated by the taxpayer, with respect to the recipient of the entertainment, amusement, or recreation, as compensation to such covered employee on the taxpayer's return of tax under this chapter and as wages to such covered employee for purposes of chapter 24 (relating to withholding of income tax at source on wages), and
“(B) in the case of any other employee, to the extent that the expenses are treated by the taxpayer, with respect to the recipient of the entertainment, amusement, or recreation, as compensation to such employee on the taxpayer's return of tax under this chapter and as wages to such employee for purposes of chapter 24 (relating to withholding of income tax at source on wages).”.
(c) Effective Dates.--
(1) Subsection (a).--The amendment made by subsection (a) shall apply to taxable years ending after the date of the enactment of this Act, and section 15 of the Internal Revenue Code of 1986 shall apply to the amendment made by this subsection as if it were a change in the rate of tax.
(2) Subsection (b).--The amendment made by subsection (b) shall apply to expenses incurred after the date of the enactment of this Act and before January 1, 2006.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment proposed (on the floor): Amendment SA 3138 proposed by Senator Hutchison.(consideration: CR S5199-5200, S5204-5205; text: CR S5199-5200)
May 11, 2004
View full timeline
Senate amendment proposed (on the floor): Amendment SA 3138 proposed by Senator Hutchison.(consideration: CR S5199-5200, S5204-5205; text: CR S5199-5200)
May 11, 2004
Senate amendment agreed to: Amendment SA 3138 agreed to in Senate by Voice Vote.
May 11, 2004
Amendment SA 3138 proposed by Senator Hutchison. (consideration: CR S5199-5200, S5204-5205; text: CR S5199-5200) To make certain engineering and architectural services eligible for the deduction relating to income attributable to United States production activities and to limit an employer's deduction for entertainment expenses of covered employees to the amount which the employee includes in income.
May 11, 2004
Amendment SA 3138 agreed to in Senate by Voice Vote.
May 11, 2004
Senate amendment submitted
May 10, 2004