S.Amdt. 3139
What it does: Adds SEC. 103. MANUFACTURER'S TAX EQUITY CREDIT AGAINST PAYROLL TAXES IN LIEU OF DEDUCTION on page 35, between lines 11 and 12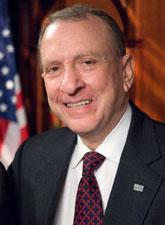 Sen. Arlen Specter (R-PA)
What it changes
1 change to S. 1637
Adds SEC. 103. MANUFACTURER'S TAX EQUITY CREDIT AGAINST PAYROLL TAXES IN LIEU OF DEDUCTION on page 35, between lines 11 and 12
Adds a sectionPrinted pageInserted: SEC. 103. MANUFACTURER'S TAX EQUITY CREDIT AGAINST PAYROLL TAXES IN LIEU OF DEDUCTION.
Inserted: (a) In General.--Subchapter C of chapter 21 is amended by redesignating section 3128 as section 3129 and inserting after section 3127 the following new section:
Inserted: "SEC. 3128. MANUFACTURER'S TAX EQUITY CREDIT.
Inserted: "(a) General Rule.--In the case of a qualified manufacturer who elects application of this section for any taxable year, there shall be allowed a credit against the taxes imposed by this chapter during the taxable year an amount equal to 10 percent of qualified health benefit plan costs paid during the taxable year.
Inserted: "(b) Qualified Manufacturer.--For purposes of this section, the term 'qualified manufacturer' means any taxpayer 50 percent or more of whose gross receipts from activities performed within the United States during the taxable year were domestic production gross receipts (within the meaning of section 199(e)).
Inserted: "(c) Qualified Health Benefit Plan Costs.--For purposes of this section--
Inserted: "(1) In general.--The term 'qualified health benefit plan costs' means any costs paid by the qualified manufacturer for a qualified health benefit plan with respect to qualified plan participants and their spouses and dependents (as defined by section 152), but only if the amount of costs paid by the qualified manufacturer is equal to or greater than 50 percent of the cost of coverage for such qualified plan participants under such plan.
Inserted: "(2) Qualified health benefit plan.--The term 'qualified health benefit plan' means an employee welfare benefit plan (within the meaning of section 3(3) of the Employee Retirement Income Security Act of 1974) which provides health benefits.
Inserted: "(3) Qualified plan participants.--The term 'qualified plan participants' means employees and former employees of the qualified manufacturer--
Inserted: "(A) who participate in a qualified health benefit plan of the qualified manufacturer,
Inserted: "(B) who are between the ages of 55 and 64, and
Inserted: "(C)(i) in the case of a participant who is an employee of such qualified manufacturer during the taxable year, whose services for such qualified manufacturer for such year are performed predominantly in the United States, and
Show 9 more inserted paragraphsShow less
Inserted: "(ii) in the case of a participant who is a former employee of such qualified manufacturer, whose services for such qualified manufacturer were performed predominantly in the United States during the period such participant was an employee.
Inserted: "(d) Denial of Deduction for Income Attributable to United States Production.--No deduction shall be allowed under section 199 for any qualified manufacturer for any taxable year for which such qualified manufacturer elects the application of this section.
Inserted: "(e) Special Rule for Affiliated Groups.--Rules similar to the rules of section 199(h)(3) shall apply for purposes of this section.".
Inserted: (b) Transfer of Funds.--The Secretary of the Treasury shall transfer from the general revenues of the Federal Government an amount sufficient so as to ensure that the income and balances of the trust funds under section 201 of the Social Security Act are not reduced as a result of the application of the amendment made by subsection (a).
Inserted: (c) Determination of Benefits.--In making any determination of benefits under title II of the Social Security Act and part A of title XVIII of such Act, the Commissioner of Social Security shall disregard the effect of the amendment made by subsection (a) on any individual's earnings record.
Inserted: (d) Conforming Amendment.--The table of sections for subchapter C of chapter 21 is amended by striking the last 2 items and inserting the following:
Inserted: "Sec. 3128. Manufacturer's tax equity credit.
Inserted: "Sec. 3129. Short title.".
Inserted: (e) Effective Date.--The amendments made by this section shall apply to taxable years ending after the date of the enactment of this Act.
Original wording
On page 35, between lines 11 and 12, insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 3139. Mr. SPECTER submitted an amendment intended to be proposed by him to the bill S. 1637, to amend the Internal Revenue Code of 1986 to comply with the World Trade Organization rulings on the FSC/ETI benefit in a manner that preserves jobs and production activities in the United States, to reform and simplify the international taxation rules of the United States, and for other purposes; which was ordered to lie on the table; as follows:
On page 35, between lines 11 and 12, insert the following:
SEC. 103. MANUFACTURER'S TAX EQUITY CREDIT AGAINST PAYROLL TAXES IN LIEU OF DEDUCTION.
(a) In General.--Subchapter C of chapter 21 is amended by redesignating section 3128 as section 3129 and inserting after section 3127 the following new section:
“SEC. 3128. MANUFACTURER'S TAX EQUITY CREDIT.
“(a) General Rule.--In the case of a qualified manufacturer who elects application of this section for any taxable year, there shall be allowed a credit against the taxes imposed by this chapter during the taxable year an amount equal to 10 percent of qualified health benefit plan costs paid during the taxable year.
“(b) Qualified Manufacturer.--For purposes of this section, the term ‘qualified manufacturer' means any taxpayer 50 percent or more of whose gross receipts from activities performed within the United States during the taxable year were domestic production gross receipts (within the meaning of section 199(e)).
“(c) Qualified Health Benefit Plan Costs.--For purposes of this section--
“(1) In general.--The term ‘qualified health benefit plan costs' means any costs paid by the qualified manufacturer for a qualified health benefit plan with respect to qualified plan participants and their spouses and dependents (as defined by section 152), but only if the amount of costs paid by the qualified manufacturer is equal to or greater than 50 percent of the cost of coverage for such qualified plan participants under such plan.
“(2) Qualified health benefit plan.--The term ‘qualified health benefit plan' means an employee welfare benefit plan (within the meaning of section 3(3) of the Employee Retirement Income Security Act of 1974) which provides health benefits.
“(3) Qualified plan participants.--The term ‘qualified plan participants' means employees and former employees of the qualified manufacturer--
“(A) who participate in a qualified health benefit plan of the qualified manufacturer,
“(B) who are between the ages of 55 and 64, and
“(C)(i) in the case of a participant who is an employee of such qualified manufacturer during the taxable year, whose services for such qualified manufacturer for such year are performed predominantly in the United States, and
“(ii) in the case of a participant who is a former employee of such qualified manufacturer, whose services for such qualified manufacturer were performed predominantly in the United States during the period such participant was an employee.
“(d) Denial of Deduction for Income Attributable to United States Production.--No deduction shall be allowed under section 199 for any qualified manufacturer for any taxable year for which such qualified manufacturer elects the application of this section.
“(e) Special Rule for Affiliated Groups.--Rules similar to the rules of section 199(h)(3) shall apply for purposes of this section.”.
(b) Transfer of Funds.--The Secretary of the Treasury shall transfer from the general revenues of the Federal Government an amount sufficient so as to ensure that the income and balances of the trust funds under section 201 of the Social Security Act are not reduced as a result of the application of the amendment made by subsection (a).
(c) Determination of Benefits.--In making any determination of benefits under title II of the Social Security Act and part A of title XVIII of such Act, the Commissioner of Social Security shall disregard the effect of the amendment made by subsection (a) on any individual's earnings record.
(d) Conforming Amendment.--The table of sections for subchapter C of chapter 21 is amended by striking the last 2 items and inserting the following:
“Sec. 3128. Manufacturer's tax equity credit.
“Sec. 3129. Short title.”.
(e) Effective Date.--The amendments made by this section shall apply to taxable years ending after the date of the enactment of this Act.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
May 10, 2004