S.Amdt. 586
What it does: Rewrites section 107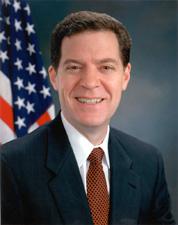 Sen. Sam Brownback (R-KS)
What it changes
1 change to S. 1054 · shown in the bill's text
Rewrites section 107
ReplacesIn S. 1054 · Placed on Calendar Senate
Struck: SEC. 107. INCREASED EXPENSING FOR SMALL BUSINESS.
Inserted: SEC. 107. INCREASE AND EXTENSION OF BONUS DEPRECIATION.
Inserted: (a) In General.--Section 168(k) (relating to special allowance for certain property acquired after September 10, 2001, and before September 11, 2004) is amended by adding at the end the following new paragraph:
Inserted: "(4) 50-percent bonus depreciation for certain property.--
Inserted: "(A) In general.--In the case of 50-percent bonus depreciation property--
Inserted: "(i) paragraph (1)(A) shall be applied by substituting '50 percent' for '30 percent', and
Inserted: "(ii) except as provided in paragraph (2)(C), such property shall be treated as qualified property for purposes of this subsection.
Inserted: "(B) 50-percent bonus depreciation property.--For purposes of this subsection, the term '50-percent bonus depreciation property' means property described in paragraph (2)(A)(i)--
Inserted: "(i) the original use of which commences with the taxpayer after May 5, 2003,
Inserted: "(ii) which is acquired by the taxpayer after May 5, 2003, and before January 1, 2006, but only if no written binding contract for the acquisition was in effect before May 6, 2003, and
Inserted: "(iii) which is placed in service by the taxpayer before January 1, 2006, or, in the case of property described in paragraph (2)(B) (as modified by subparagraph (C) of this paragraph), before January 1, 2007.
Inserted: "(C) Special rules.--Rules similar to the rules of subparagraphs (B) and (D) of paragraph (2) shall apply for purposes of this paragraph; except that--
Inserted: "(i) references to September 10, 2001, shall be treated as references to May 5, 2003, and
Show 14 more inserted paragraphsShow less
Inserted: "(ii) references to September 11, 2001, shall be treated as references to May 6, 2003.
Inserted: "(D) Automobiles.--Paragraph (2)(E) shall be applied by substituting '$9,200' for '$4,600' in the case of 50-percent bonus depreciation property.
Inserted: "(E) Election of 30 percent bonus.--If a taxpayer makes an election under this subparagraph with respect to any class of property for any taxable year, subparagraph (A)(i) shall not apply to all property in such class placed in service during such taxable year."
Inserted: (b) Extension of Placed in Service Dates, Etc. for 30-Percent Bonus Depreciation Property.--
Inserted: (1) In general.--Clause (iv) of section 168(k)(2)(A) is amended--
Inserted: (A) by striking "January 1, 2005" and inserting "January 1, 2006", and
Inserted: (B) by striking "January 1, 2006" (as in effect before the amendment made by subparagraph (A)) and inserting "January 1, 2007".
Inserted: (2) Portion of basis taken into account.--Subparagraphs (B)(ii) and (D)(i) of section 168(k)(2) are each amended by striking "September 11, 2004" each place it appears and inserting "January 1, 2006".
Inserted: (3) Election.--Clause (iii) of section 168(k)(2)(C) is amended by adding at the end the following: "The preceding sentence shall be applied separately with respect to property treated as qualified property by paragraph (4) and other qualified property."
Inserted: (c) Conforming Amendments.--
Inserted: (1) The subsection heading for section 168(k) is amended by striking "September 11, 2004" and inserting "January 1, 2006".
Inserted: (2) The heading for clause (i) of section 1400L(b)(2)(C) is amended by striking "30-percent additional allowable property" and inserting "Bonus depreciation property under section 168(k)".
Inserted: (d) Effective Date.--The amendments made by this section shall apply to taxable years ending after the date of the enactment of this Act.
Inserted: SEC. 107A. INCREASED EXPENSING FOR SMALL BUSINESS.
(a) In General.--Paragraph (1) of section 179(b) (relating to dollar limitation) is amended to read as follows:
"(1) Dollar limitation.--The aggregate cost which may be taken into account under subsection (a) for any taxable year shall not exceed
[struck: $75,000][inserted: $25,000 ($100,000 in the case of taxable years beginning after 2002 and before 2008)].".(b) Increase in Qualifying Investment at Which Phaseout Begins.--
[struck: ]Paragraph (2) of section 179(b) (relating to reduction in limitation) is amended by[struck: striking][inserted: inserting] "[struck: $200,000" ][inserted: ($400,000 in the case of taxable years beginning after 2002 ]and[struck: inserting ][inserted: before 2008)]"[struck: $325,000][inserted: after ]"[inserted: $200,000"].(c) Off-the-Shelf Computer Software.--Paragraph (1) of section 179(d) (defining section 179 property) is amended to read as follows:
"(1) Section 179 property.--For purposes of this section, the term 'section 179 property' means property--
"(A) which is--
"(i) tangible property (to which section 168 applies), or
"(ii) computer software (as defined in section 197(e)(3)(B)) which is described in section 197(e)(3)(A)(i)
[struck: and ][inserted: , ]to which section 167 applies,[inserted: and which is placed in service in a taxable year beginning after 2002 and before 2008,]"(B) which is section 1245 property (as defined in section 1245(a)(3)), and
"(C) which is acquired by purchase for use in the active conduct of a trade or business. Such term shall not include any property described in section 50(b) and shall not include air conditioning or heating units.".
(d) Adjustment of Dollar Limit and Phaseout Threshold for Inflation.--Subsection (b) of section 179 (relating to limitations) is amended by adding at the end the following new paragraph:
"(5) Inflation adjustments.--
"(A) In general.--In the case of any taxable year beginning in a calendar year after 2003[inserted: and before 2008], the
[struck: dollar ][inserted: $100,000 and $400,000 ]amounts in paragraphs (1) and (2) shall each be increased by an amount equal to--Inserted: "(i) such dollar amount, multiplied by
"(
[struck: i) such dollar amount, multiplied by "(]ii) the cost-of-living adjustment determined under section 1(f)(3) for the calendar year in which the taxable year begins, by substituting 'calendar year 2002' for 'calendar year 1992' in subparagraph (B) thereof."(B) Rounding.--
"(i) Dollar limitation.--If the amount in paragraph (1) as increased under subparagraph (A) is not a multiple of $1,000, such amount shall be rounded to the nearest multiple of $1,000.
"(ii) Phaseout amount.--If the amount in paragraph (2) as increased under subparagraph (A) is not a multiple of $10,000, such amount shall be rounded to the nearest multiple of $10,000.".
(e) Revocation of Election.--Paragraph (2) of section 179(c) (relating to election irrevocable) is amended to read as follows:
"(2) Revocation of election.--
[struck: The taxpayer may revoke an ][inserted: An ]election under paragraph (1)[inserted: with respect to any taxable year beginning after 2002 and before 2008], and any specification contained in any such election, [inserted: may be revoked by the taxpayer ]with respect to any property. Such revocation, once made, shall be irrevocable.".(f) Effective Date.--The amendments made by this section shall apply to taxable years beginning after December 31, 2002.
Original wording
Strike section 107 and insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 586. Mr. BROWNBACK submitted an amendment intended to be proposed by him to the bill S. 1054, to provide for reconciliation to section 201 of the concurrent resolution on the budget for fiscal year 2004; which was ordered to lie on the table; as follows:
Strike section 107 and insert the following:
SEC. 107. INCREASE AND EXTENSION OF BONUS DEPRECIATION.
(a) In General.--Section 168(k) (relating to special allowance for certain property acquired after September 10, 2001, and before September 11, 2004) is amended by adding at the end the following new paragraph:
“(4) 50-percent bonus depreciation for certain property.--
“(A) In general.--In the case of 50-percent bonus depreciation property--
“(i) paragraph (1)(A) shall be applied by substituting ‘50 percent' for ‘30 percent', and
“(ii) except as provided in paragraph (2)(C), such property shall be treated as qualified property for purposes of this subsection.
“(B) 50-percent bonus depreciation property.--For purposes of this subsection, the term ‘50-percent bonus depreciation property' means property described in paragraph (2)(A)(i)--
“(i) the original use of which commences with the taxpayer after May 5, 2003,
“(ii) which is acquired by the taxpayer after May 5, 2003, and before January 1, 2006, but only if no written binding contract for the acquisition was in effect before May 6, 2003, and
“(iii) which is placed in service by the taxpayer before January 1, 2006, or, in the case of property described in paragraph (2)(B) (as modified by subparagraph (C) of this paragraph), before January 1, 2007.
“(C) Special rules.--Rules similar to the rules of subparagraphs (B) and (D) of paragraph (2) shall apply for purposes of this paragraph; except that--
“(i) references to September 10, 2001, shall be treated as references to May 5, 2003, and
“(ii) references to September 11, 2001, shall be treated as references to May 6, 2003.
“(D) Automobiles.--Paragraph (2)(E) shall be applied by substituting ‘$9,200' for ‘$4,600' in the case of 50-percent bonus depreciation property.
“(E) Election of 30 percent bonus.--If a taxpayer makes an election under this subparagraph with respect to any class of property for any taxable year, subparagraph (A)(i) shall not apply to all property in such class placed in service during such taxable year.”
(b) Extension of Placed in Service Dates, Etc. for 30-Percent Bonus Depreciation Property.--
(1) In general.--Clause (iv) of section 168(k)(2)(A) is amended--
(A) by striking “January 1, 2005” and inserting “January 1, 2006”, and
(B) by striking “January 1, 2006” (as in effect before the amendment made by subparagraph (A)) and inserting “January 1, 2007”.
(2) Portion of basis taken into account.--Subparagraphs (B)(ii) and (D)(i) of section 168(k)(2) are each amended by striking “September 11, 2004” each place it appears and inserting “January 1, 2006”.
(3) Election.--Clause (iii) of section 168(k)(2)(C) is amended by adding at the end the following: “The preceding sentence shall be applied separately with respect to property treated as qualified property by paragraph (4) and other qualified property.”
(c) Conforming Amendments.--
(1) The subsection heading for section 168(k) is amended by striking “September 11, 2004” and inserting “January 1, 2006”.
(2) The heading for clause (i) of section 1400L(b)(2)(C) is amended by striking “30-percent additional allowable property” and inserting “Bonus depreciation property under section 168(k)”.
(d) Effective Date.--The amendments made by this section shall apply to taxable years ending after the date of the enactment of this Act.
SEC. 107A. INCREASED EXPENSING FOR SMALL BUSINESS.
(a) In General.--Paragraph (1) of section 179(b) (relating to dollar limitation) is amended to read as follows:
“(1) Dollar limitation.--The aggregate cost which may be taken into account under subsection (a) for any taxable year shall not exceed $25,000 ($100,000 in the case of taxable years beginning after 2002 and before 2008).”.
(b) Increase in Qualifying Investment at Which Phaseout Begins.--Paragraph (2) of section 179(b) (relating to reduction in limitation) is amended by inserting “($400,000 in the case of taxable years beginning after 2002 and before 2008)” after “$200,000”.
(c) Off-the-Shelf Computer Software.--Paragraph (1) of section 179(d) (defining section 179 property) is amended to read as follows:
“(1) Section 179 property.--For purposes of this section, the term ‘section 179 property' means property--
“(A) which is--
“(i) tangible property (to which section 168 applies), or
“(ii) computer software (as defined in section 197(e)(3)(B)) which is described in section 197(e)(3)(A)(i), to which section 167 applies, and which is placed in service in a taxable year beginning after 2002 and before 2008,
“(B) which is section 1245 property (as defined in section 1245(a)(3)), and
“(C) which is acquired by purchase for use in the active conduct of a trade or business. Such term shall not include any property described in section 50(b) and shall not include air conditioning or heating units.”.
(d) Adjustment of Dollar Limit and Phaseout Threshold for Inflation.--Subsection (b) of section 179 (relating to limitations) is amended by adding at the end the following new paragraph:
“(5) Inflation adjustments.--
“(A) In general.--In the case of any taxable year beginning in a calendar year after 2003 and before 2008, the $100,000 and $400,000 amounts in paragraphs (1) and (2) shall each be increased by an amount equal to--
“(i) such dollar amount, multiplied by
“(ii) the cost-of-living adjustment determined under section 1(f)(3) for the calendar year in which the taxable year begins, by substituting ‘calendar year 2002' for ‘calendar year 1992' in subparagraph (B) thereof.
“(B) Rounding.--
“(i) Dollar limitation.--If the amount in paragraph (1) as increased under subparagraph (A) is not a multiple of $1,000, such amount shall be rounded to the nearest multiple of $1,000.
“(ii) Phaseout amount.--If the amount in paragraph (2) as increased under subparagraph (A) is not a multiple of $10,000, such amount shall be rounded to the nearest multiple of $10,000.”.
(e) Revocation of Election.--Paragraph (2) of section 179(c) (relating to election irrevocable) is amended to read as follows:
“(2) Revocation of election.--An election under paragraph (1) with respect to any taxable year beginning after 2002 and before 2008, and any specification contained in any such election, may be revoked by the taxpayer with respect to any property. Such revocation, once made, shall be irrevocable.”.
(f) Effective Date.--The amendments made by this section shall apply to taxable years beginning after December 31, 2002.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
May 14, 2003