S.Amdt. 2274
What it does: Rewrites page 158, lines 12–21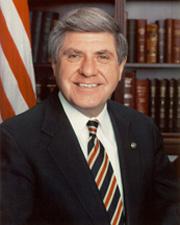 Sen. Ben Nelson (D-NE)
What it changes
1 change to H.R. 3010
Rewrites page 158, lines 12–21
ReplacesPrinted pageRemoves page 158, lines 12–21 of the printed bill. See that page
Inserted: bus Budget Reconciliation Act of 1981, $3,483,000,000.
Inserted: For making payments under title XXVI of the Omnibus Budget Reconciliation Act of 1981, $300,000,000, to remain available until expended: Provided, That these funds are for the unanticipated home energy assistance needs of one or more States, as authorized by section 2604(e) of the Act: Provided further, That the entire amount is designated as an emergency requirement pursuant to section 402 of H. Con. Res. 95 (109th Congress), the concurrent resolution on the budget for fiscal year 2006.
Inserted: general provision--revenue raising provisions SEC. __. PARTIAL PAYMENTS REQUIRED WITH SUBMISSION OF OFFERS-IN-COMPROMISE.
Inserted: (a) In General.--Section 7122 of the Internal Revenue Code of 1986 (relating to compromises) is amended by redesignating subsections (c) and (d) as subsections (d) and (e), respectively, and by inserting after subsection (b) the following new subsection:
Inserted: "(c) Rules for Submission of Offers-in-Compromise.--
Inserted: "(1) Partial payment required with submission.--
Inserted: "(A) Lump-sum offers.--
Inserted: "(i) In general.--The submission of any lump-sum offer-in-compromise shall be accompanied by the payment of 20 percent of amount of such offer.
Inserted: "(ii) Lump-sum offer-in-compromise.--For purposes of this section, the term 'lump-sum offer-in-compromise' means any offer of payments made in 5 or fewer installments.
Inserted: "(B) Periodic payment offers.--The submission of any periodic payment offer-in-compromise shall be accompanied by the payment of the amount of the first proposed installment and each proposed installment due during the period such offer is being evaluated for acceptance and has not been rejected by the Secretary. Any failure to make a payment required under the preceding sentence shall be deemed a withdrawal of the offer-in-compromise.
Inserted: "(2) Rules of application.--
Inserted: "(A) Use of payment.--The application of any payment made under this subsection to the assessed tax or other amounts imposed under this title with respect to such tax may be specified by the taxpayer.
Show 191 more inserted paragraphsShow less
Inserted: "(B) No user fee imposed.--Any user fee which would otherwise be imposed under this section shall not be imposed on any offer-in-compromise accompanied by a payment required under this subsection.".
Inserted: (b) Additional Rules Relating to Treatment of Offers.--
Inserted: (1) Unprocessable offer if payment requirements are not met.--Paragraph (3) of section 7122(d) of the Internal Revenue Code of 1986 (relating to standards for evaluation of offers), as redesignated by subsection (a), is amended by striking "; and" at the end of subparagraph (A) and inserting a comma, by striking the period at the end of subparagraph (B) and inserting ", and", and by adding at the end the following new subparagraph:
Inserted: "(C) any offer-in-compromise which does not meet the requirements of subsection (c) shall be returned to the taxpayer as unprocessable.".
Inserted: (2) Deemed acceptance of offer not rejected within certain period.--Section 7122 of such Code, as amended by subsection (a), is amended by adding at the end the following new subsection:
Inserted: "(f) Deemed Acceptance of Offer Not Rejected Within Certain Period.--Any offer-in-compromise submitted under this section shall be deemed to be accepted by the Secretary if such offer is not rejected by the Secretary before the date which is 24 months after the date of the submission of such offer (12 months for offers-in-compromise submitted after the date which is 5 years after the date of the enactment of this subsection). For purposes of the preceding sentence, any period during which any tax liability which is the subject of such offer-in-compromise is in dispute in any judicial proceeding shall not be taken in to account in determining the expiration of the 24-month period (or 12-month period, if applicable).".
Inserted: (c) Effective Date.--The amendments made by this section shall apply to offers-in-compromise submitted on and after the date which is 60 days after the date of the enactment of this Act.
Inserted: SEC. __. TREATMENT OF CONTINGENT PAYMENT CONVERTIBLE DEBT INSTRUMENTS.
Inserted: (a) In General.--Section 1275(d) of the Internal Revenue Code of 1986 (relating to regulation authority) is amended--
Inserted: (1) by striking "The Secretary" and inserting the following:
Inserted: "(1) In general.--The Secretary", and
Inserted: (2) by adding at the end the following new paragraph:
Inserted: "(2) Treatment of contingent payment convertible debt.--
Inserted: "(A) In general.--In the case of a debt instrument which--
Inserted: "(i) is convertible into stock of the issuing corporation, into stock or debt of a related party (within the meaning of section 267(b) or 707(b)(1)), or into cash or other property in an amount equal to the approximate value of such stock or debt, and
Inserted: "(ii) provides for contingent payments, any regulations which require original issue discount to be determined by reference to the comparable yield of a noncontingent fixed-rate debt instrument shall be applied as if the regulations require that such comparable yield be determined by reference to a noncontingent fixed-rate debt instrument which is convertible into stock.
Inserted: "(B) Special rule.--For purposes of subparagraph (A), the comparable yield shall be determined without taking into account the yield resulting from the conversion of a debt instrument into stock.".
Inserted: (b) Cross Reference.--Section 163(e)(6) of the Internal Revenue Code of 1986 (relating to cross references) is amended by adding at the end the following:
Inserted: "For the treatment of contingent payment convertible debt, see section 1275(d)(2).".
Inserted: (c) Effective Date.--The amendments made by this section shall apply to debt instruments issued on or after the date of the enactment of this Act.
Inserted: SEC. __. IMPOSITION OF MARK-TO-MARKET TAX ON INDIVIDUALS WHO EXPATRIATE.
Inserted: (a) In General.--Subpart A of part II of subchapter N of chapter 1of the Internal Revenue Code of 1986 is amended by inserting after section 877 the following new section:
Inserted: "SEC. 877A. TAX RESPONSIBILITIES OF EXPATRIATION.
Inserted: "(a) General Rules.--For purposes of this subtitle--
Inserted: "(1) Mark to market.--Except as provided in subsections (d) and (f), all property of a covered expatriate to whom this section applies shall be treated as sold on the day before the expatriation date for its fair market value.
Inserted: "(2) Recognition of gain or loss.--In the case of any sale under paragraph (1)--
Inserted: "(A) notwithstanding any other provision of this title, any gain arising from such sale shall be taken into account for the taxable year of the sale, and
Inserted: "(B) any loss arising from such sale shall be taken into account for the taxable year of the sale to the extent otherwise provided by this title, except that section 1091 shall not apply to any such loss.
Inserted: Proper adjustment shall be made in the amount of any gain or loss subsequently realized for gain or loss taken into account under the preceding sentence.
Inserted: "(3) Exclusion for certain gain.--
Inserted: "(A) In general.--The amount which, but for this paragraph, would be includible in the gross income of any individual by reason of this section shall be reduced (but not below zero) by $600,000. For purposes of this paragraph, allocable expatriation gain taken into account under subsection (f)(2) shall be treated in the same manner as an amount required to be includible in gross income.
Inserted: "(B) Cost-of-living adjustment.--
Inserted: "(i) In general.--In the case of an expatriation date occurring in any calendar year after 2005, the $600,000 amount under subparagraph (A) shall be increased by an amount equal to--
Inserted: "(I) such dollar amount, multiplied by
Inserted: "(II) the cost-of-living adjustment determined under section 1(f)(3) for such calendar year, determined by substituting 'calendar year 2004' for 'calendar year 1992' in subparagraph (B) thereof.
Inserted: "(ii) Rounding rules.--If any amount after adjustment under clause (i) is not a multiple of $1,000, such amount shall be rounded to the next lower multiple of $1,000.
Inserted: "(4) Election to continue to be taxed as united states citizen.--
Inserted: "(A) In general.--If a covered expatriate elects the application of this paragraph--
Inserted: "(i) this section (other than this paragraph and subsection (i)) shall not apply to the expatriate, but
Inserted: "(ii) in the case of property to which this section would apply but for such election, the expatriate shall be subject to tax under this title in the same manner as if the individual were a United States citizen.
Inserted: "(B) Requirements.--Subparagraph (A) shall not apply to an individual unless the individual--
Inserted: "(i) provides security for payment of tax in such form and manner, and in such amount, as the Secretary may require,
Inserted: "(ii) consents to the waiver of any right of the individual under any treaty of the United States which would preclude assessment or collection of any tax which may be imposed by reason of this paragraph, and
Inserted: "(iii) complies with such other requirements as the Secretary may prescribe.
Inserted: "(C) Election.--An election under subparagraph (A) shall apply to all property to which this section would apply but for the election and, once made, shall be irrevocable. Such election shall also apply to property the basis of which is determined in whole or in part by reference to the property with respect to which the election was made.
Inserted: "(b) Election to Defer Tax.--
Inserted: "(1) In general.--If the taxpayer elects the application of this subsection with respect to any property treated as sold by reason of subsection (a), the payment of the additional tax attributable to such property shall be postponed until the due date of the return for the taxable year in which such property is disposed of (or, in the case of property disposed of in a transaction in which gain is not recognized in whole or in part, until such other date as the Secretary may prescribe).
Inserted: "(2) Determination of tax with respect to property.--For purposes of paragraph (1), the additional tax attributable to any property is an amount which bears the same ratio to the additional tax imposed by this chapter for the taxable year solely by reason of subsection (a) as the gain taken into account under subsection (a) with respect to such property bears to the total gain taken into account under subsection (a) with respect to all property to which subsection (a) applies.
Inserted: "(3) Termination of postponement.--No tax may be postponed under this subsection later than the due date for the return of tax imposed by this chapter for the taxable year which includes the date of death of the expatriate (or, if earlier, the time that the security provided with respect to the property fails to meet the requirements of paragraph (4), unless the taxpayer corrects such failure within the time specified by the Secretary).
Inserted: "(4) Security.--
Inserted: "(A) In general.--No election may be made under paragraph (1) with respect to any property unless adequate security is provided to the Secretary with respect to such property.
Inserted: "(B) Adequate security.--For purposes of subparagraph (A), security with respect to any property shall be treated as adequate security if--
Inserted: "(i) it is a bond in an amount equal to the deferred tax amount under paragraph (2) for the property, or
Inserted: "(ii) the taxpayer otherwise establishes to the satisfaction of the Secretary that the security is adequate.
Inserted: "(5) Waiver of certain rights.--No election may be made under paragraph (1) unless the taxpayer consents to the waiver of any right under any treaty of the United States which would preclude assessment or collection of any tax imposed by reason of this section.
Inserted: "(6) Elections.--An election under paragraph (1) shall only apply to property described in the election and, once made, is irrevocable. An election may be made under paragraph (1) with respect to an interest in a trust with respect to which gain is required to be recognized under subsection (f)(1).
Inserted: "(7) Interest.--For purposes of section 6601--
Inserted: "(A) the last date for the payment of tax shall be determined without regard to the election under this subsection, and
Inserted: "(B) section 6621(a)(2) shall be applied by substituting '5 percentage points' for '3 percentage points' in subparagraph (B) thereof.
Inserted: "(c) Covered Expatriate.--For purposes of this section--
Inserted: "(1) In general.--Except as provided in paragraph (2), the term 'covered expatriate' means an expatriate.
Inserted: "(2) Exceptions.--An individual shall not be treated as a covered expatriate if--
Inserted: "(A) the individual--
Inserted: "(i) became at birth a citizen of the United States and a citizen of another country and, as of the expatriation date, continues to be a citizen of, and is taxed as a resident of, such other country, and
Inserted: "(ii) has not been a resident of the United States (as defined in section 7701(b)(1)(A)(ii)) during the 5 taxable years ending with the taxable year during which the expatriation date occurs, or
Inserted: "(B)(i) the individual's relinquishment of United States citizenship occurs before such individual attains age 18\1/ 2\, and
Inserted: "(ii) the individual has been a resident of the United States (as so defined) for not more than 5 taxable years before the date of relinquishment.
Inserted: "(d) Exempt Property; Special Rules for Pension Plans.--
Inserted: "(1) Exempt property.--This section shall not apply to the following:
Inserted: "(A) United states real property interests.--Any United States real property interest (as defined in section 897(c)(1)), other than stock of a United States real property holding corporation which does not, on the day before the expatriation date, meet the requirements of section 897(c)(2).
Inserted: "(B) Specified property.--Any property or interest in property not described in subparagraph (A) which the Secretary specifies in regulations.
Inserted: "(2) Special rules for certain retirement plans.--
Inserted: "(A) In general.--If a covered expatriate holds on the day before the expatriation date any interest in a retirement plan to which this paragraph applies--
Inserted: "(i) such interest shall not be treated as sold for purposes of subsection (a)(1), but
Inserted: "(ii) an amount equal to the present value of the expatriate's nonforfeitable accrued benefit shall be treated as having been received by such individual on such date as a distribution under the plan.
Inserted: "(B) Treatment of subsequent distributions.--In the case of any distribution on or after the expatriation date to or on behalf of the covered expatriate from a plan from which the expatriate was treated as receiving a distribution under subparagraph (A), the amount otherwise includible in gross income by reason of the subsequent distribution shall be reduced by the excess of the amount includible in gross income under subparagraph (A) over any portion of such amount to which this subparagraph previously applied.
Inserted: "(C) Treatment of subsequent distributions by plan.--For purposes of this title, a retirement plan to which this paragraph applies, and any person acting on the plan's behalf, shall treat any subsequent distribution described in subparagraph (B) in the same manner as such distribution would be treated without regard to this paragraph.
Inserted: "(D) Applicable plans.--This paragraph shall apply to--
Inserted: "(i) any qualified retirement plan (as defined in section 4974(c)),
Inserted: "(ii) an eligible deferred compensation plan (as defined in section 457(b)) of an eligible employer described in section 457(e)(1)(A), and
Inserted: "(iii) to the extent provided in regulations, any foreign pension plan or similar retirement arrangements or programs.
Inserted: "(e) Definitions.--For purposes of this section--
Inserted: "(1) Expatriate.--The term 'expatriate' means--
Inserted: "(A) any United States citizen who relinquishes citizenship, and
Inserted: "(B) any long-term resident of the United States who--
Inserted: "(i) ceases to be a lawful permanent resident of the United States (within the meaning of section 7701(b)(6)), or
Inserted: "(ii) commences to be treated as a resident of a foreign country under the provisions of a tax treaty between the United States and the foreign country and who does not waive the benefits of such treaty applicable to residents of the foreign country.
Inserted: "(2) Expatriation date.--The term 'expatriation date' means--
Inserted: "(A) the date an individual relinquishes United States citizenship, or
Inserted: "(B) in the case of a long-term resident of the United States, the date of the event described in clause (i) or (ii) of paragraph (1)(B).
Inserted: "(3) Relinquishment of citizenship.--A citizen shall be treated as relinquishing United States citizenship on the earliest of--
Inserted: "(A) the date the individual renounces such individual's United States nationality before a diplomatic or consular officer of the United States pursuant to paragraph (5) of section 349(a) of the Immigration and Nationality Act (8 U.S.C. 1481(a)(5)),
Inserted: "(B) the date the individual furnishes to the United States Department of State a signed statement of voluntary relinquishment of United States nationality confirming the performance of an act of expatriation specified in paragraph (1), (2), (3), or (4) of section 349(a) of the Immigration and Nationality Act (8 U.S.C. 1481(a)(1)-(4)),
Inserted: "(C) the date the United States Department of State issues to the individual a certificate of loss of nationality, or
Inserted: "(D) the date a court of the United States cancels a naturalized citizen's certificate of naturalization.
Inserted: Subparagraph (A) or (B) shall not apply to any individual unless the renunciation or voluntary relinquishment is subsequently approved by the issuance to the individual of a certificate of loss of nationality by the United States Department of State.
Inserted: "(4) Long-term resident.--The term 'long-term resident' has the meaning given to such term by section 877(e)(2).
Inserted: "(f) Special Rules Applicable to Beneficiaries' Interests in Trust.--
Inserted: "(1) In general.--Except as provided in paragraph (2), if an individual is determined under paragraph (3) to hold an interest in a trust on the day before the expatriation date--
Inserted: "(A) the individual shall not be treated as having sold such interest,
Inserted: "(B) such interest shall be treated as a separate share in the trust, and
Inserted: "(C)(i) such separate share shall be treated as a separate trust consisting of the assets allocable to such share,
Inserted: "(ii) the separate trust shall be treated as having sold its assets on the day before the expatriation date for their fair market value and as having distributed all of its assets to the individual as of such time, and
Inserted: "(iii) the individual shall be treated as having recontributed the assets to the separate trust.
Inserted: Subsection (a)(2) shall apply to any income, gain, or loss of the individual arising from a distribution described in subparagraph (C)(ii). In determining the amount of such distribution, proper adjustments shall be made for liabilities of the trust allocable to an individual's share in the trust.
Inserted: "(2) Special rules for interests in qualified trusts.--
Inserted: "(A) In general.--If the trust interest described in paragraph (1) is an interest in a qualified trust--
Inserted: "(i) paragraph (1) and subsection (a) shall not apply, and
Inserted: "(ii) in addition to any other tax imposed by this title, there is hereby imposed on each distribution with respect to such interest a tax in the amount determined under subparagraph (B).
Inserted: "(B) Amount of tax.--The amount of tax under subparagraph (A)(ii) shall be equal to the lesser of--
Inserted: "(i) the highest rate of tax imposed by section 1(e) for the taxable year which includes the day before the expatriation date, multiplied by the amount of the distribution, or
Inserted: "(ii) the balance in the deferred tax account immediately before the distribution determined without regard to any increases under subparagraph (C)(ii) after the 30th day preceding the distribution.
Inserted: "(C) Deferred tax account.--For purposes of subparagraph (B)(ii)--
Inserted: "(i) Opening balance.--The opening balance in a deferred tax account with respect to any trust interest is an amount equal to the tax which would have been imposed on the allocable expatriation gain with respect to the trust interest if such gain had been included in gross income under subsection (a).
Inserted: "(ii) Increase for interest.--The balance in the deferred tax account shall be increased by the amount of interest determined (on the balance in the account at the time the interest accrues), for periods after the 90th day after the expatriation date, by using the rates and method applicable under section 6621 for underpayments of tax for such periods, except that section 6621(a)(2) shall be applied by substituting '5 percentage points' for '3 percentage points' in subparagraph (B) thereof.
Inserted: "(iii) Decrease for taxes previously paid.--The balance in the tax deferred account shall be reduced--
Inserted: "(I) by the amount of taxes imposed by subparagraph (A) on any distribution to the person holding the trust interest, and
Inserted: "(II) in the case of a person holding a nonvested interest, to the extent provided in regulations, by the amount of taxes imposed by subparagraph (A) on distributions from the trust with respect to nonvested interests not held by such person.
Inserted: "(D) Allocable expatriation gain.--For purposes of this paragraph, the allocable expatriation gain with respect to any beneficiary's interest in a trust is the amount of gain which would be allocable to such beneficiary's vested and nonvested interests in the trust if the beneficiary held directly all assets allocable to such interests.
Inserted: "(E) Tax deducted and withheld.--
Inserted: "(i) In general.--The tax imposed by subparagraph (A)(ii) shall be deducted and withheld by the trustees from the distribution to which it relates.
Inserted: "(ii) Exception where failure to waive treaty rights.--If an amount may not be deducted and withheld under clause (i) by reason of the distributee failing to waive any treaty right with respect to such distribution--
Inserted: "(I) the tax imposed by subparagraph (A)(ii) shall be imposed on the trust and each trustee shall be personally liable for the amount of such tax, and
Inserted: "(II) any other beneficiary of the trust shall be entitled to recover from the distributee the amount of such tax imposed on the other beneficiary.
Inserted: "(F) Disposition.--If a trust ceases to be a qualified trust at any time, a covered expatriate disposes of an interest in a qualified trust, or a covered expatriate holding an interest in a qualified trust dies, then, in lieu of the tax imposed by subparagraph (A)(ii), there is hereby imposed a tax equal to the lesser of--
Inserted: "(i) the tax determined under paragraph (1) as if the day before the expatriation date were the date of such cessation, disposition, or death, whichever is applicable, or
Inserted: "(ii) the balance in the tax deferred account immediately before such date.
Inserted: Such tax shall be imposed on the trust and each trustee shall be personally liable for the amount of such tax and any other beneficiary of the trust shall be entitled to recover from the covered expatriate or the estate the amount of such tax imposed on the other beneficiary.
Inserted: "(G) Definitions and special rules.--For purposes of this paragraph--
Inserted: "(i) Qualified trust.--The term 'qualified trust' means a trust which is described in section 7701(a)(30)(E).
Inserted: "(ii) Vested interest.--The term 'vested interest' means any interest which, as of the day before the expatriation date, is vested in the beneficiary.
Inserted: "(iii) Nonvested interest.--The term 'nonvested interest' means, with respect to any beneficiary, any interest in a trust which is not a vested interest. Such interest shall be determined by assuming the maximum exercise of discretion in favor of the beneficiary and the occurrence of all contingencies in favor of the beneficiary.
Inserted: "(iv) Adjustments.--The Secretary may provide for such adjustments to the bases of assets in a trust or a deferred tax account, and the timing of such adjustments, in order to ensure that gain is taxed only once.
Inserted: "(v) Coordination with retirement plan rules.--This subsection shall not apply to an interest in a trust which is part of a retirement plan to which subsection (d)(2) applies.
Inserted: "(3) Determination of beneficiaries' interest in trust.--
Inserted: "(A) Determinations under paragraph (1).--For purposes of paragraph (1), a beneficiary's interest in a trust shall be based upon all relevant facts and circumstances, including the terms of the trust instrument and any letter of wishes or similar document, historical patterns of trust distributions, and the existence of and functions performed by a trust protector or any similar adviser.
Inserted: "(B) Other determinations.--For purposes of this section--
Inserted: "(i) Constructive ownership.--If a beneficiary of a trust is a corporation, partnership, trust, or estate, the shareholders, partners, or beneficiaries shall be deemed to be the trust beneficiaries for purposes of this section.
Inserted: "(ii) Taxpayer return position.--A taxpayer shall clearly indicate on its income tax return--
Inserted: "(I) the methodology used to determine that taxpayer's trust interest under this section, and
Inserted: "(II) if the taxpayer knows (or has reason to know) that any other beneficiary of such trust is using a different methodology to determine such beneficiary's trust interest under this section.
Inserted: "(g) Termination of Deferrals, Etc.--In the case of any covered expatriate, notwithstanding any other provision of this title--
Inserted: "(1) any period during which recognition of income or gain is deferred shall terminate on the day before the expatriation date, and
Inserted: "(2) any extension of time for payment of tax shall cease to apply on the day before the expatriation date and the unpaid portion of such tax shall be due and payable at the time and in the manner prescribed by the Secretary.
Inserted: "(h) Imposition of Tentative Tax.--
Inserted: "(1) In general.--If an individual is required to include any amount in gross income under subsection (a) for any taxable year, there is hereby imposed, immediately before the expatriation date, a tax in an amount equal to the amount of tax which would be imposed if the taxable year were a short taxable year ending on the expatriation date.
Inserted: "(2) Due date.--The due date for any tax imposed by paragraph (1) shall be the 90th day after the expatriation date.
Inserted: "(3) Treatment of tax.--Any tax paid under paragraph (1) shall be treated as a payment of the tax imposed by this chapter for the taxable year to which subsection (a) applies.
Inserted: "(4) Deferral of tax.--The provisions of subsection (b) shall apply to the tax imposed by this subsection to the extent attributable to gain includible in gross income by reason of this section.
Inserted: "(i) Special Liens for Deferred Tax Amounts.--
Inserted: "(1) Imposition of lien.--
Inserted: "(A) In general.--If a covered expatriate makes an election under subsection (a)(4) or (b) which results in the deferral of any tax imposed by reason of subsection (a), the deferred amount (including any interest, additional amount, addition to tax, assessable penalty, and costs attributable to the deferred amount) shall be a lien in favor of the United States on all property of the expatriate located in the United States (without regard to whether this section applies to the property).
Inserted: "(B) Deferred amount.--For purposes of this subsection, the deferred amount is the amount of the increase in the covered expatriate's income tax which, but for the election under subsection (a)(4) or (b), would have occurred by reason of this section for the taxable year including the expatriation date.
Inserted: "(2) Period of lien.--The lien imposed by this subsection shall arise on the expatriation date and continue until--
Inserted: "(A) the liability for tax by reason of this section is satisfied or has become unenforceable by reason of lapse of time, or
Inserted: "(B) it is established to the satisfaction of the Secretary that no further tax liability may arise by reason of this section.
Inserted: "(3) Certain rules apply.--The rules set forth in paragraphs (1), (3), and (4) of section 6324A(d) shall apply with respect to the lien imposed by this subsection as if it were a lien imposed by section 6324A.
Inserted: "(j) Regulations.--The Secretary shall prescribe such regulations as may be necessary or appropriate to carry out the purposes of this section.".
Inserted: (b) Inclusion in Income of Gifts and Bequests Received by United States Citizens and Residents From Expatriates.--Section 102 of the Internal Revenue Code of 1986 (relating to gifts, etc. not included in gross income) is amended by adding at the end the following new subsection:
Inserted: "(d) Gifts and Inheritances From Covered Expatriates.--
Inserted: "(1) In general.--Subsection (a) shall not exclude from gross income the value of any property acquired by gift, bequest, devise, or inheritance from a covered expatriate after the expatriation date. For purposes of this subsection, any term used in this subsection which is also used in section 877A shall have the same meaning as when used in section 877A.
Inserted: "(2) Exceptions for transfers otherwise subject to estate or gift tax.--Paragraph (1) shall not apply to any property if either--
Inserted: "(A) the gift, bequest, devise, or inheritance is--
Inserted: "(i) shown on a timely filed return of tax imposed by chapter 12 as a taxable gift by the covered expatriate, or
Inserted: "(ii) included in the gross estate of the covered expatriate for purposes of chapter 11 and shown on a timely filed return of tax imposed by chapter 11 of the estate of the covered expatriate, or
Inserted: "(B) no such return was timely filed but no such return would have been required to be filed even if the covered expatriate were a citizen or long-term resident of the United States.".
Inserted: (c) Definition of Termination of United States Citizenship.--Section 7701(a) of the Internal Revenue Code of 1986 is amended by adding at the end the following new paragraph:
Inserted: "(49) Termination of united states citizenship.--
Inserted: "(A) In general.--An individual shall not cease to be treated as a United States citizen before the date on which the individual's citizenship is treated as relinquished under section 877A(e)(3).
Inserted: "(B) Dual citizens.--Under regulations prescribed by the Secretary, subparagraph (A) shall not apply to an individual who became at birth a citizen of the United States and a citizen of another country.".
Inserted: (d) Ineligibility for Visa or Admission to United States.--
Inserted: (1) In general.--Section 212(a)(10)(E) of the Immigration and Nationality Act (8 U.S.C. 1182(a)(10)(E)) is amended to read as follows:
Inserted: "(E) Former citizens not in compliance with expatriation revenue provisions.--Any alien who is a former citizen of the United States who relinquishes United States citizenship (within the meaning of section 877A(e)(3) of the Internal Revenue Code of 1986) and who is not in compliance with section 877A of such Code (relating to expatriation).".
Inserted: (2) Availability of information.--
Inserted: (A) In general.--Section 6103(l) of the Internal Revenue Code of 1986 (relating to disclosure of returns and return information for purposes other than tax administration) is amended by adding at the end the following new paragraph:
Inserted: "(21) Disclosure to deny visa or admission to certain expatriates.--Upon written request of the Attorney General or the Attorney General's delegate, the Secretary shall disclose whether an individual is in compliance with section 877A (and if not in compliance, any items of noncompliance) to officers and employees of the Federal agency responsible for administering section 212(a)(10)(E) of the Immigration and Nationality Act solely for the purpose of, and to the extent necessary in, administering such section 212(a)(10)(E).".
Inserted: (B) Safeguards.--Section 6103(p)(4) of such Code (relating to safeguards) is amended by striking "or (20)" each place it appears and inserting "(20), or (21)".
Inserted: (3) Effective dates.--The amendments made by this subsection shall apply to individuals who relinquish United States citizenship on or after the date of the enactment of this Act.
Inserted: (e) Conforming Amendments.--
Inserted: (1) Section 877 of the Internal Revenue Code of 1986 is amended by adding at the end the following new subsection:
Inserted: "(h) Application.--This section shall not apply to an expatriate (as defined in section 877A(e)) whose expatriation date (as so defined) occurs on or after the date of the enactment of the Safe, Accountable, Flexible, and Efficient Transportation Equity Act of 2005.".
Inserted: (2) Section 2107 of such Code is amended by adding at the end the following new subsection:
Inserted: "(f) Application.--This section shall not apply to any expatriate subject to section 877A.".
Inserted: (3) Section 2501(a)(3) of such Code is amended by adding at the end the following new subparagraph:
Inserted: "(C) Application.--This paragraph shall not apply to any expatriate subject to section 877A.".
Inserted: (f) Clerical Amendment.--The table of sections for subpart A of part II of subchapter N of chapter 1 of the Internal Revenue Code of 1986 is amended by inserting after the item relating to section 877 the following new item:
Inserted: "Sec. 877A. Tax responsibilities of expatriation.".
Inserted: (g) Effective Date.--
Inserted: (1) In general.--Except as provided in this subsection, the amendments made by this section shall apply to expatriates (within the meaning of section 877A(e) of the Internal Revenue Code of 1986, as added by this section) whose expatriation date (as so defined) occurs on or after the date of the enactment of this Act.
Inserted: (2) Gifts and bequests.--Section 102(d) of the Internal Revenue Code of 1986 (as added by subsection (b)) shall apply to gifts and bequests received on or after the date of the enactment of this Act, from an individual or the estate of an individual whose expatriation date (as so defined) occurs after such date.
Inserted: (3) Due date for tentative tax.--The due date under section 877A(h)(2) of the Internal Revenue Code of 1986, as added by this section, shall in no event occur before the 90th day after the date of the enactment of this Act.
Original wording
On page 158, strike lines 12 through 21 and insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 2274. Mr. NELSON of Nebraska (for himself and Mr. Carper) submitted an amendment intended to be proposed by him to the bill H.R. 3010, making appropriations for the Departments of Labor, Health and Human Services, and Education, and Related Agencies for the fiscal year ending September 30, 2006, and for other purposes; which was ordered to lie on the table; as follows:
On page 158, strike lines 12 through 21 and insert the following:
bus Budget Reconciliation Act of 1981, $3,483,000,000.
For making payments under title XXVI of the Omnibus Budget Reconciliation Act of 1981, $300,000,000, to remain available until expended: Provided, That these funds are for the unanticipated home energy assistance needs of one or more States, as authorized by section 2604(e) of the Act: Provided further, That the entire amount is designated as an emergency requirement pursuant to section 402 of H. Con. Res. 95 (109th Congress), the concurrent resolution on the budget for fiscal year 2006.
general provision--revenue raising provisions SEC. __. PARTIAL PAYMENTS REQUIRED WITH SUBMISSION OF OFFERS-IN-COMPROMISE.
(a) In General.--Section 7122 of the Internal Revenue Code of 1986 (relating to compromises) is amended by redesignating subsections (c) and (d) as subsections (d) and (e), respectively, and by inserting after subsection (b) the following new subsection:
“(c) Rules for Submission of Offers-in-Compromise.--
“(1) Partial payment required with submission.--
“(A) Lump-sum offers.--
“(i) In general.--The submission of any lump-sum offer-in-compromise shall be accompanied by the payment of 20 percent of amount of such offer.
“(ii) Lump-sum offer-in-compromise.--For purposes of this section, the term ‘lump-sum offer-in-compromise' means any offer of payments made in 5 or fewer installments.
“(B) Periodic payment offers.--The submission of any periodic payment offer-in-compromise shall be accompanied by the payment of the amount of the first proposed installment and each proposed installment due during the period such offer is being evaluated for acceptance and has not been rejected by the Secretary. Any failure to make a payment required under the preceding sentence shall be deemed a withdrawal of the offer-in-compromise.
“(2) Rules of application.--
“(A) Use of payment.--The application of any payment made under this subsection to the assessed tax or other amounts imposed under this title with respect to such tax may be specified by the taxpayer.
“(B) No user fee imposed.--Any user fee which would otherwise be imposed under this section shall not be imposed on any offer-in-compromise accompanied by a payment required under this subsection.”.
(b) Additional Rules Relating to Treatment of Offers.--
(1) Unprocessable offer if payment requirements are not met.--Paragraph (3) of section 7122(d) of the Internal Revenue Code of 1986 (relating to standards for evaluation of offers), as redesignated by subsection (a), is amended by striking “; and” at the end of subparagraph (A) and inserting a comma, by striking the period at the end of subparagraph (B) and inserting “, and”, and by adding at the end the following new subparagraph:
“(C) any offer-in-compromise which does not meet the requirements of subsection (c) shall be returned to the taxpayer as unprocessable.”.
(2) Deemed acceptance of offer not rejected within certain period.--Section 7122 of such Code, as amended by subsection (a), is amended by adding at the end the following new subsection:
“(f) Deemed Acceptance of Offer Not Rejected Within Certain Period.--Any offer-in-compromise submitted under this section shall be deemed to be accepted by the Secretary if such offer is not rejected by the Secretary before the date which is 24 months after the date of the submission of such offer (12 months for offers-in-compromise submitted after the date which is 5 years after the date of the enactment of this subsection). For purposes of the preceding sentence, any period during which any tax liability which is the subject of such offer-in-compromise is in dispute in any judicial proceeding shall not be taken in to account in determining the expiration of the 24-month period (or 12-month period, if applicable).”.
(c) Effective Date.--The amendments made by this section shall apply to offers-in-compromise submitted on and after the date which is 60 days after the date of the enactment of this Act.
SEC. __. TREATMENT OF CONTINGENT PAYMENT CONVERTIBLE DEBT INSTRUMENTS.
(a) In General.--Section 1275(d) of the Internal Revenue Code of 1986 (relating to regulation authority) is amended--
(1) by striking “The Secretary” and inserting the following:
“(1) In general.--The Secretary”, and
(2) by adding at the end the following new paragraph:
“(2) Treatment of contingent payment convertible debt.--
“(A) In general.--In the case of a debt instrument which--
“(i) is convertible into stock of the issuing corporation, into stock or debt of a related party (within the meaning of section 267(b) or 707(b)(1)), or into cash or other property in an amount equal to the approximate value of such stock or debt, and
“(ii) provides for contingent payments, any regulations which require original issue discount to be determined by reference to the comparable yield of a noncontingent fixed-rate debt instrument shall be applied as if the regulations require that such comparable yield be determined by reference to a noncontingent fixed-rate debt instrument which is convertible into stock.
“(B) Special rule.--For purposes of subparagraph (A), the comparable yield shall be determined without taking into account the yield resulting from the conversion of a debt instrument into stock.”.
(b) Cross Reference.--Section 163(e)(6) of the Internal Revenue Code of 1986 (relating to cross references) is amended by adding at the end the following:
“For the treatment of contingent payment convertible debt, see section 1275(d)(2).”.
(c) Effective Date.--The amendments made by this section shall apply to debt instruments issued on or after the date of the enactment of this Act.
SEC. __. IMPOSITION OF MARK-TO-MARKET TAX ON INDIVIDUALS WHO EXPATRIATE.
(a) In General.--Subpart A of part II of subchapter N of chapter 1of the Internal Revenue Code of 1986 is amended by inserting after section 877 the following new section:
“SEC. 877A. TAX RESPONSIBILITIES OF EXPATRIATION.
“(a) General Rules.--For purposes of this subtitle--
“(1) Mark to market.--Except as provided in subsections (d) and (f), all property of a covered expatriate to whom this section applies shall be treated as sold on the day before the expatriation date for its fair market value.
“(2) Recognition of gain or loss.--In the case of any sale under paragraph (1)--
“(A) notwithstanding any other provision of this title, any gain arising from such sale shall be taken into account for the taxable year of the sale, and
“(B) any loss arising from such sale shall be taken into account for the taxable year of the sale to the extent otherwise provided by this title, except that section 1091 shall not apply to any such loss.
Proper adjustment shall be made in the amount of any gain or loss subsequently realized for gain or loss taken into account under the preceding sentence.
“(3) Exclusion for certain gain.--
“(A) In general.--The amount which, but for this paragraph, would be includible in the gross income of any individual by reason of this section shall be reduced (but not below zero) by $600,000. For purposes of this paragraph, allocable expatriation gain taken into account under subsection (f)(2) shall be treated in the same manner as an amount required to be includible in gross income.
“(B) Cost-of-living adjustment.--
“(i) In general.--In the case of an expatriation date occurring in any calendar year after 2005, the $600,000 amount under subparagraph (A) shall be increased by an amount equal to--
“(I) such dollar amount, multiplied by
“(II) the cost-of-living adjustment determined under section 1(f)(3) for such calendar year, determined by substituting ‘calendar year 2004' for ‘calendar year 1992' in subparagraph (B) thereof.
“(ii) Rounding rules.--If any amount after adjustment under clause (i) is not a multiple of $1,000, such amount shall be rounded to the next lower multiple of $1,000.
“(4) Election to continue to be taxed as united states citizen.--
“(A) In general.--If a covered expatriate elects the application of this paragraph--
“(i) this section (other than this paragraph and subsection (i)) shall not apply to the expatriate, but
“(ii) in the case of property to which this section would apply but for such election, the expatriate shall be subject to tax under this title in the same manner as if the individual were a United States citizen.
“(B) Requirements.--Subparagraph (A) shall not apply to an individual unless the individual--
“(i) provides security for payment of tax in such form and manner, and in such amount, as the Secretary may require,
“(ii) consents to the waiver of any right of the individual under any treaty of the United States which would preclude assessment or collection of any tax which may be imposed by reason of this paragraph, and
“(iii) complies with such other requirements as the Secretary may prescribe.
“(C) Election.--An election under subparagraph (A) shall apply to all property to which this section would apply but for the election and, once made, shall be irrevocable. Such election shall also apply to property the basis of which is determined in whole or in part by reference to the property with respect to which the election was made.
“(b) Election to Defer Tax.--
“(1) In general.--If the taxpayer elects the application of this subsection with respect to any property treated as sold by reason of subsection (a), the payment of the additional tax attributable to such property shall be postponed until the due date of the return for the taxable year in which such property is disposed of (or, in the case of property disposed of in a transaction in which gain is not recognized in whole or in part, until such other date as the Secretary may prescribe).
“(2) Determination of tax with respect to property.--For purposes of paragraph (1), the additional tax attributable to any property is an amount which bears the same ratio to the additional tax imposed by this chapter for the taxable year solely by reason of subsection (a) as the gain taken into account under subsection (a) with respect to such property bears to the total gain taken into account under subsection (a) with respect to all property to which subsection (a) applies.
“(3) Termination of postponement.--No tax may be postponed under this subsection later than the due date for the return of tax imposed by this chapter for the taxable year which includes the date of death of the expatriate (or, if earlier, the time that the security provided with respect to the property fails to meet the requirements of paragraph (4), unless the taxpayer corrects such failure within the time specified by the Secretary).
“(4) Security.--
“(A) In general.--No election may be made under paragraph (1) with respect to any property unless adequate security is provided to the Secretary with respect to such property.
“(B) Adequate security.--For purposes of subparagraph (A), security with respect to any property shall be treated as adequate security if--
“(i) it is a bond in an amount equal to the deferred tax amount under paragraph (2) for the property, or
“(ii) the taxpayer otherwise establishes to the satisfaction of the Secretary that the security is adequate.
“(5) Waiver of certain rights.--No election may be made under paragraph (1) unless the taxpayer consents to the waiver of any right under any treaty of the United States which would preclude assessment or collection of any tax imposed by reason of this section.
“(6) Elections.--An election under paragraph (1) shall only apply to property described in the election and, once made, is irrevocable. An election may be made under paragraph (1) with respect to an interest in a trust with respect to which gain is required to be recognized under subsection (f)(1).
“(7) Interest.--For purposes of section 6601--
“(A) the last date for the payment of tax shall be determined without regard to the election under this subsection, and
“(B) section 6621(a)(2) shall be applied by substituting ‘5 percentage points' for ‘3 percentage points' in subparagraph (B) thereof.
“(c) Covered Expatriate.--For purposes of this section--
“(1) In general.--Except as provided in paragraph (2), the term ‘covered expatriate' means an expatriate.
“(2) Exceptions.--An individual shall not be treated as a covered expatriate if--
“(A) the individual--
“(i) became at birth a citizen of the United States and a citizen of another country and, as of the expatriation date, continues to be a citizen of, and is taxed as a resident of, such other country, and
“(ii) has not been a resident of the United States (as defined in section 7701(b)(1)(A)(ii)) during the 5 taxable years ending with the taxable year during which the expatriation date occurs, or
“(B)(i) the individual's relinquishment of United States citizenship occurs before such individual attains age 18\1/ 2\, and
“(ii) the individual has been a resident of the United States (as so defined) for not more than 5 taxable years before the date of relinquishment.
“(d) Exempt Property; Special Rules for Pension Plans.--
“(1) Exempt property.--This section shall not apply to the following:
“(A) United states real property interests.--Any United States real property interest (as defined in section 897(c)(1)), other than stock of a United States real property holding corporation which does not, on the day before the expatriation date, meet the requirements of section 897(c)(2).
“(B) Specified property.--Any property or interest in property not described in subparagraph (A) which the Secretary specifies in regulations.
“(2) Special rules for certain retirement plans.--
“(A) In general.--If a covered expatriate holds on the day before the expatriation date any interest in a retirement plan to which this paragraph applies--
“(i) such interest shall not be treated as sold for purposes of subsection (a)(1), but
“(ii) an amount equal to the present value of the expatriate's nonforfeitable accrued benefit shall be treated as having been received by such individual on such date as a distribution under the plan.
“(B) Treatment of subsequent distributions.--In the case of any distribution on or after the expatriation date to or on behalf of the covered expatriate from a plan from which the expatriate was treated as receiving a distribution under subparagraph (A), the amount otherwise includible in gross income by reason of the subsequent distribution shall be reduced by the excess of the amount includible in gross income under subparagraph (A) over any portion of such amount to which this subparagraph previously applied.
“(C) Treatment of subsequent distributions by plan.--For purposes of this title, a retirement plan to which this paragraph applies, and any person acting on the plan's behalf, shall treat any subsequent distribution described in subparagraph (B) in the same manner as such distribution would be treated without regard to this paragraph.
“(D) Applicable plans.--This paragraph shall apply to--
“(i) any qualified retirement plan (as defined in section 4974(c)),
“(ii) an eligible deferred compensation plan (as defined in section 457(b)) of an eligible employer described in section 457(e)(1)(A), and
“(iii) to the extent provided in regulations, any foreign pension plan or similar retirement arrangements or programs.
“(e) Definitions.--For purposes of this section--
“(1) Expatriate.--The term ‘expatriate' means--
“(A) any United States citizen who relinquishes citizenship, and
“(B) any long-term resident of the United States who--
“(i) ceases to be a lawful permanent resident of the United States (within the meaning of section 7701(b)(6)), or
“(ii) commences to be treated as a resident of a foreign country under the provisions of a tax treaty between the United States and the foreign country and who does not waive the benefits of such treaty applicable to residents of the foreign country.
“(2) Expatriation date.--The term ‘expatriation date' means--
“(A) the date an individual relinquishes United States citizenship, or
“(B) in the case of a long-term resident of the United States, the date of the event described in clause (i) or (ii) of paragraph (1)(B).
“(3) Relinquishment of citizenship.--A citizen shall be treated as relinquishing United States citizenship on the earliest of--
“(A) the date the individual renounces such individual's United States nationality before a diplomatic or consular officer of the United States pursuant to paragraph (5) of section 349(a) of the Immigration and Nationality Act (8 U.S.C. 1481(a)(5)),
“(B) the date the individual furnishes to the United States Department of State a signed statement of voluntary relinquishment of United States nationality confirming the performance of an act of expatriation specified in paragraph (1), (2), (3), or (4) of section 349(a) of the Immigration and Nationality Act (8 U.S.C. 1481(a)(1)-(4)),
“(C) the date the United States Department of State issues to the individual a certificate of loss of nationality, or
“(D) the date a court of the United States cancels a naturalized citizen's certificate of naturalization.
Subparagraph (A) or (B) shall not apply to any individual unless the renunciation or voluntary relinquishment is subsequently approved by the issuance to the individual of a certificate of loss of nationality by the United States Department of State.
“(4) Long-term resident.--The term ‘long-term resident' has the meaning given to such term by section 877(e)(2).
“(f) Special Rules Applicable to Beneficiaries' Interests in Trust.--
“(1) In general.--Except as provided in paragraph (2), if an individual is determined under paragraph (3) to hold an interest in a trust on the day before the expatriation date--
“(A) the individual shall not be treated as having sold such interest,
“(B) such interest shall be treated as a separate share in the trust, and
“(C)(i) such separate share shall be treated as a separate trust consisting of the assets allocable to such share,
“(ii) the separate trust shall be treated as having sold its assets on the day before the expatriation date for their fair market value and as having distributed all of its assets to the individual as of such time, and
“(iii) the individual shall be treated as having recontributed the assets to the separate trust.
Subsection (a)(2) shall apply to any income, gain, or loss of the individual arising from a distribution described in subparagraph (C)(ii). In determining the amount of such distribution, proper adjustments shall be made for liabilities of the trust allocable to an individual's share in the trust.
“(2) Special rules for interests in qualified trusts.--
“(A) In general.--If the trust interest described in paragraph (1) is an interest in a qualified trust--
“(i) paragraph (1) and subsection (a) shall not apply, and
“(ii) in addition to any other tax imposed by this title, there is hereby imposed on each distribution with respect to such interest a tax in the amount determined under subparagraph (B).
“(B) Amount of tax.--The amount of tax under subparagraph (A)(ii) shall be equal to the lesser of--
“(i) the highest rate of tax imposed by section 1(e) for the taxable year which includes the day before the expatriation date, multiplied by the amount of the distribution, or
“(ii) the balance in the deferred tax account immediately before the distribution determined without regard to any increases under subparagraph (C)(ii) after the 30th day preceding the distribution.
“(C) Deferred tax account.--For purposes of subparagraph (B)(ii)--
“(i) Opening balance.--The opening balance in a deferred tax account with respect to any trust interest is an amount equal to the tax which would have been imposed on the allocable expatriation gain with respect to the trust interest if such gain had been included in gross income under subsection (a).
“(ii) Increase for interest.--The balance in the deferred tax account shall be increased by the amount of interest determined (on the balance in the account at the time the interest accrues), for periods after the 90th day after the expatriation date, by using the rates and method applicable under section 6621 for underpayments of tax for such periods, except that section 6621(a)(2) shall be applied by substituting ‘5 percentage points' for ‘3 percentage points' in subparagraph (B) thereof.
“(iii) Decrease for taxes previously paid.--The balance in the tax deferred account shall be reduced--
“(I) by the amount of taxes imposed by subparagraph (A) on any distribution to the person holding the trust interest, and
“(II) in the case of a person holding a nonvested interest, to the extent provided in regulations, by the amount of taxes imposed by subparagraph (A) on distributions from the trust with respect to nonvested interests not held by such person.
“(D) Allocable expatriation gain.--For purposes of this paragraph, the allocable expatriation gain with respect to any beneficiary's interest in a trust is the amount of gain which would be allocable to such beneficiary's vested and nonvested interests in the trust if the beneficiary held directly all assets allocable to such interests.
“(E) Tax deducted and withheld.--
“(i) In general.--The tax imposed by subparagraph (A)(ii) shall be deducted and withheld by the trustees from the distribution to which it relates.
“(ii) Exception where failure to waive treaty rights.--If an amount may not be deducted and withheld under clause (i) by reason of the distributee failing to waive any treaty right with respect to such distribution--
“(I) the tax imposed by subparagraph (A)(ii) shall be imposed on the trust and each trustee shall be personally liable for the amount of such tax, and
“(II) any other beneficiary of the trust shall be entitled to recover from the distributee the amount of such tax imposed on the other beneficiary.
“(F) Disposition.--If a trust ceases to be a qualified trust at any time, a covered expatriate disposes of an interest in a qualified trust, or a covered expatriate holding an interest in a qualified trust dies, then, in lieu of the tax imposed by subparagraph (A)(ii), there is hereby imposed a tax equal to the lesser of--
“(i) the tax determined under paragraph (1) as if the day before the expatriation date were the date of such cessation, disposition, or death, whichever is applicable, or
“(ii) the balance in the tax deferred account immediately before such date.
Such tax shall be imposed on the trust and each trustee shall be personally liable for the amount of such tax and any other beneficiary of the trust shall be entitled to recover from the covered expatriate or the estate the amount of such tax imposed on the other beneficiary.
“(G) Definitions and special rules.--For purposes of this paragraph--
“(i) Qualified trust.--The term ‘qualified trust' means a trust which is described in section 7701(a)(30)(E).
“(ii) Vested interest.--The term ‘vested interest' means any interest which, as of the day before the expatriation date, is vested in the beneficiary.
“(iii) Nonvested interest.--The term ‘nonvested interest' means, with respect to any beneficiary, any interest in a trust which is not a vested interest. Such interest shall be determined by assuming the maximum exercise of discretion in favor of the beneficiary and the occurrence of all contingencies in favor of the beneficiary.
“(iv) Adjustments.--The Secretary may provide for such adjustments to the bases of assets in a trust or a deferred tax account, and the timing of such adjustments, in order to ensure that gain is taxed only once.
“(v) Coordination with retirement plan rules.--This subsection shall not apply to an interest in a trust which is part of a retirement plan to which subsection (d)(2) applies.
“(3) Determination of beneficiaries' interest in trust.--
“(A) Determinations under paragraph (1).--For purposes of paragraph (1), a beneficiary's interest in a trust shall be based upon all relevant facts and circumstances, including the terms of the trust instrument and any letter of wishes or similar document, historical patterns of trust distributions, and the existence of and functions performed by a trust protector or any similar adviser.
“(B) Other determinations.--For purposes of this section--
“(i) Constructive ownership.--If a beneficiary of a trust is a corporation, partnership, trust, or estate, the shareholders, partners, or beneficiaries shall be deemed to be the trust beneficiaries for purposes of this section.
“(ii) Taxpayer return position.--A taxpayer shall clearly indicate on its income tax return--
“(I) the methodology used to determine that taxpayer's trust interest under this section, and
“(II) if the taxpayer knows (or has reason to know) that any other beneficiary of such trust is using a different methodology to determine such beneficiary's trust interest under this section.
“(g) Termination of Deferrals, Etc.--In the case of any covered expatriate, notwithstanding any other provision of this title--
“(1) any period during which recognition of income or gain is deferred shall terminate on the day before the expatriation date, and
“(2) any extension of time for payment of tax shall cease to apply on the day before the expatriation date and the unpaid portion of such tax shall be due and payable at the time and in the manner prescribed by the Secretary.
“(h) Imposition of Tentative Tax.--
“(1) In general.--If an individual is required to include any amount in gross income under subsection (a) for any taxable year, there is hereby imposed, immediately before the expatriation date, a tax in an amount equal to the amount of tax which would be imposed if the taxable year were a short taxable year ending on the expatriation date.
“(2) Due date.--The due date for any tax imposed by paragraph (1) shall be the 90th day after the expatriation date.
“(3) Treatment of tax.--Any tax paid under paragraph (1) shall be treated as a payment of the tax imposed by this chapter for the taxable year to which subsection (a) applies.
“(4) Deferral of tax.--The provisions of subsection (b) shall apply to the tax imposed by this subsection to the extent attributable to gain includible in gross income by reason of this section.
“(i) Special Liens for Deferred Tax Amounts.--
“(1) Imposition of lien.--
“(A) In general.--If a covered expatriate makes an election under subsection (a)(4) or (b) which results in the deferral of any tax imposed by reason of subsection (a), the deferred amount (including any interest, additional amount, addition to tax, assessable penalty, and costs attributable to the deferred amount) shall be a lien in favor of the United States on all property of the expatriate located in the United States (without regard to whether this section applies to the property).
“(B) Deferred amount.--For purposes of this subsection, the deferred amount is the amount of the increase in the covered expatriate's income tax which, but for the election under subsection (a)(4) or (b), would have occurred by reason of this section for the taxable year including the expatriation date.
“(2) Period of lien.--The lien imposed by this subsection shall arise on the expatriation date and continue until--
“(A) the liability for tax by reason of this section is satisfied or has become unenforceable by reason of lapse of time, or
“(B) it is established to the satisfaction of the Secretary that no further tax liability may arise by reason of this section.
“(3) Certain rules apply.--The rules set forth in paragraphs (1), (3), and (4) of section 6324A(d) shall apply with respect to the lien imposed by this subsection as if it were a lien imposed by section 6324A.
“(j) Regulations.--The Secretary shall prescribe such regulations as may be necessary or appropriate to carry out the purposes of this section.”.
(b) Inclusion in Income of Gifts and Bequests Received by United States Citizens and Residents From Expatriates.--Section 102 of the Internal Revenue Code of 1986 (relating to gifts, etc. not included in gross income) is amended by adding at the end the following new subsection:
“(d) Gifts and Inheritances From Covered Expatriates.--
“(1) In general.--Subsection (a) shall not exclude from gross income the value of any property acquired by gift, bequest, devise, or inheritance from a covered expatriate after the expatriation date. For purposes of this subsection, any term used in this subsection which is also used in section 877A shall have the same meaning as when used in section 877A.
“(2) Exceptions for transfers otherwise subject to estate or gift tax.--Paragraph (1) shall not apply to any property if either--
“(A) the gift, bequest, devise, or inheritance is--
“(i) shown on a timely filed return of tax imposed by chapter 12 as a taxable gift by the covered expatriate, or
“(ii) included in the gross estate of the covered expatriate for purposes of chapter 11 and shown on a timely filed return of tax imposed by chapter 11 of the estate of the covered expatriate, or
“(B) no such return was timely filed but no such return would have been required to be filed even if the covered expatriate were a citizen or long-term resident of the United States.”.
(c) Definition of Termination of United States Citizenship.--Section 7701(a) of the Internal Revenue Code of 1986 is amended by adding at the end the following new paragraph:
“(49) Termination of united states citizenship.--
“(A) In general.--An individual shall not cease to be treated as a United States citizen before the date on which the individual's citizenship is treated as relinquished under section 877A(e)(3).
“(B) Dual citizens.--Under regulations prescribed by the Secretary, subparagraph (A) shall not apply to an individual who became at birth a citizen of the United States and a citizen of another country.”.
(d) Ineligibility for Visa or Admission to United States.--
(1) In general.--Section 212(a)(10)(E) of the Immigration and Nationality Act (8 U.S.C. 1182(a)(10)(E)) is amended to read as follows:
“(E) Former citizens not in compliance with expatriation revenue provisions.--Any alien who is a former citizen of the United States who relinquishes United States citizenship (within the meaning of section 877A(e)(3) of the Internal Revenue Code of 1986) and who is not in compliance with section 877A of such Code (relating to expatriation).”.
(2) Availability of information.--
(A) In general.--Section 6103(l) of the Internal Revenue Code of 1986 (relating to disclosure of returns and return information for purposes other than tax administration) is amended by adding at the end the following new paragraph:
“(21) Disclosure to deny visa or admission to certain expatriates.--Upon written request of the Attorney General or the Attorney General's delegate, the Secretary shall disclose whether an individual is in compliance with section 877A (and if not in compliance, any items of noncompliance) to officers and employees of the Federal agency responsible for administering section 212(a)(10)(E) of the Immigration and Nationality Act solely for the purpose of, and to the extent necessary in, administering such section 212(a)(10)(E).”.
(B) Safeguards.--Section 6103(p)(4) of such Code (relating to safeguards) is amended by striking “or (20)” each place it appears and inserting “(20), or (21)”.
(3) Effective dates.--The amendments made by this subsection shall apply to individuals who relinquish United States citizenship on or after the date of the enactment of this Act.
(e) Conforming Amendments.--
(1) Section 877 of the Internal Revenue Code of 1986 is amended by adding at the end the following new subsection:
“(h) Application.--This section shall not apply to an expatriate (as defined in section 877A(e)) whose expatriation date (as so defined) occurs on or after the date of the enactment of the Safe, Accountable, Flexible, and Efficient Transportation Equity Act of 2005.”.
(2) Section 2107 of such Code is amended by adding at the end the following new subsection:
“(f) Application.--This section shall not apply to any expatriate subject to section 877A.”.
(3) Section 2501(a)(3) of such Code is amended by adding at the end the following new subparagraph:
“(C) Application.--This paragraph shall not apply to any expatriate subject to section 877A.”.
(f) Clerical Amendment.--The table of sections for subpart A of part II of subchapter N of chapter 1 of the Internal Revenue Code of 1986 is amended by inserting after the item relating to section 877 the following new item:
“Sec. 877A. Tax responsibilities of expatriation.”.
(g) Effective Date.--
(1) In general.--Except as provided in this subsection, the amendments made by this section shall apply to expatriates (within the meaning of section 877A(e) of the Internal Revenue Code of 1986, as added by this section) whose expatriation date (as so defined) occurs on or after the date of the enactment of this Act.
(2) Gifts and bequests.--Section 102(d) of the Internal Revenue Code of 1986 (as added by subsection (b)) shall apply to gifts and bequests received on or after the date of the enactment of this Act, from an individual or the estate of an individual whose expatriation date (as so defined) occurs after such date.
(3) Due date for tentative tax.--The due date under section 877A(h)(2) of the Internal Revenue Code of 1986, as added by this section, shall in no event occur before the 90th day after the date of the enactment of this Act.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
October 26, 2005