To require the Secretary of the Treasury to establish a disability preference program for qualified tax collection contracts.
What it does: Adds SEC. __. DISABILITY PREFERENCE PROGRAM FOR TAX COLLECTION CONTRACTS at the end of title IV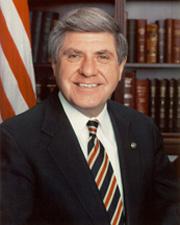 Sen. Ben Nelson (D-NE)
What it changes
1 change to S. 2020 · shown in the bill's text
Adds SEC. __. DISABILITY PREFERENCE PROGRAM FOR TAX COLLECTION CONTRACTS at the end of title IV
Adds a sectionIn S. 2020 · Placed on Calendar Senate
(d) Effective Date.--The amendments made by this section shall apply to amounts paid or accrued during the period beginning after December 31, 2006, and before January 1, 2008, and properly allocable to such period, with respect to mortgage insurance contracts issued after December 31, 2006.
Inserted: SEC. __. DISABILITY PREFERENCE PROGRAM FOR TAX COLLECTION CONTRACTS.
Inserted: (a) In General.--The Secretary of the Treasury shall not enter into any qualified tax collection contract after April 1, 2006, until the Secretary implements a disability preference program that meets the requirements of subsection (b).
Inserted: (b) Disability Preference Program Requirements.--
Inserted: (1) In general.--A disability preference program meets the requirements of this subsection if such program requires that not less than 10 percent of the accounts of each dollar value category are awarded to persons described in paragraph (2).
Inserted: (2) Person described.--For purposes of paragraph (1), a person is described in this paragraph if--
Inserted: (A) as of the date any qualified tax collection contract is awarded--
Inserted: (i) such person employs not less than 50 severely disabled individuals within the United States; or
Inserted: (ii) not less than 30 percent of the employees of such person within the United States are severely disabled individuals;
Inserted: (B) such person agrees as a condition of the qualified tax collection contract that not more than 90 days after the date such contract is awarded, not less than 35 percent of the employees of such person employed in connection with providing services under such contract shall--
Inserted: (i) be hired after the date such contract is awarded; and
Inserted: (ii) be severely disabled individuals; and
Inserted: (C) such person is otherwise qualified to perform the services required.
Show 8 more inserted paragraphsShow less
Inserted: (c) Definitions.--For purposes of this section--
Inserted: (1) Qualified tax collection contract.--The term "qualified tax collection contract" shall have the meaning given such term under section 6306(b) of the Internal Revenue Code of 1986.
Inserted: (2) Dollar value category.--The term "dollar value category" means the dollar ranges of accounts for collection as determined and assigned by the Secretary under section 6306(b)(1)(B) of the Internal Revenue Code of 1986 with respect to a qualified tax collection contract.
Inserted: (3) Severely disabled individual.--The term "severely disabled individual" means--
Inserted: (A) a veteran of the United States armed forces with a disability of 50 percent or greater--
Inserted: (i) determined by the Secretary of Veterans Affairs to be service-connected; or
Inserted: (ii) deemed by law to be service-connected; or
Inserted: (B) any individual who is a disabled beneficiary (as defined in section 1148(k)(2) of the Social Security Act (42 U.S.C. 1320b-19(k)(2))) or who would be considered to be such a disabled beneficiary but for having income or resources in excess of the income or resources eligibility limits established under title XVI of the Social Security Act (42 U.S.C. 1381 et seq.), respectively.
Original wording
At the end of title IV, insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
At the end of title IV, insert the following:
SEC. __. DISABILITY PREFERENCE PROGRAM FOR TAX COLLECTION CONTRACTS.
(a) In General.--The Secretary of the Treasury shall not enter into any qualified tax collection contract after April 1, 2006, until the Secretary implements a disability preference program that meets the requirements of subsection (b).
(b) Disability Preference Program Requirements.--
(1) In general.--A disability preference program meets the requirements of this subsection if such program requires that not less than 10 percent of the accounts of each dollar value category are awarded to persons described in paragraph (2).
(2) Person described.--For purposes of paragraph (1), a person is described in this paragraph if--
(A) as of the date any qualified tax collection contract is awarded--
(i) such person employs not less than 50 severely disabled individuals within the United States; or
(ii) not less than 30 percent of the employees of such person within the United States are severely disabled individuals;
(B) such person agrees as a condition of the qualified tax collection contract that not more than 90 days after the date such contract is awarded, not less than 35 percent of the employees of such person employed in connection with providing services under such contract shall--
(i) be hired after the date such contract is awarded; and
(ii) be severely disabled individuals; and
(C) such person is otherwise qualified to perform the services required.
(c) Definitions.--For purposes of this section--
(1) Qualified tax collection contract.--The term “qualified tax collection contract” shall have the meaning given such term under section 6306(b) of the Internal Revenue Code of 1986.
(2) Dollar value category.--The term “dollar value category” means the dollar ranges of accounts for collection as determined and assigned by the Secretary under section 6306(b)(1)(B) of the Internal Revenue Code of 1986 with respect to a qualified tax collection contract.
(3) Severely disabled individual.--The term “severely disabled individual” means--
(A) a veteran of the United States armed forces with a disability of 50 percent or greater--
(i) determined by the Secretary of Veterans Affairs to be service-connected; or
(ii) deemed by law to be service-connected; or
(B) any individual who is a disabled beneficiary (as defined in section 1148(k)(2) of the Social Security Act (42 U.S.C. 1320b-19(k)(2))) or who would be considered to be such a disabled beneficiary but for having income or resources in excess of the income or resources eligibility limits established under title XVI of the Social Security Act (42 U.S.C. 1381 et seq.), respectively.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
November 17, 2005
View full timeline
Senate amendment submitted
November 17, 2005
Senate amendment proposed (on the floor): Amendment SA 2625 proposed by Senator Nelson NE.(consideration: CR S13120-13121, S13130; text: CR S13120-13121)
November 17, 2005
Senate amendment agreed to: Amendment SA 2625 agreed to in Senate by Unanimous Consent.
November 17, 2005
Amendment SA 2625 proposed by Senator Nelson NE. (consideration: CR S13120-13121, S13130; text: CR S13120-13121) To require the Secretary of the Treasury to establish a disability preference program for qualified tax collection contracts.
November 17, 2005
Amendment SA 2625 agreed to in Senate by Unanimous Consent.
November 17, 2005