An amendment numbered 2 printed in House Report 110-450 to better consumer protection by improving mortgage servicing, protecting appraiser independence, ensuring better appraisal quality and regulatory oversight, requiring escrows for mortgages for borrowers who might experience difficulty with repayment, and establishing disclosure for consumers who waive escrow accounts.
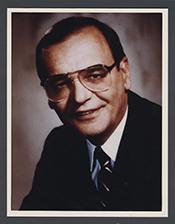 Rep. Paul E. Kanjorski (D-PA)
Description
Amendment to better consumer protection by improving mortgage servicing, protecting appraiser independence, ensuring better appraisal quality and regulatory oversight, requiring escrows for mortgages for borrowers who might experience difficulty with repayment, and establishing disclosure for consumers who waive escrow accounts.
Text
Offered
Page 134, after line 13 insert the folowing new titles (and conform the table of contents accordingly):
TITLE VI--MORTGAGE SERVICING
SEC. 601. ESCROW AND IMPOUND ACCOUNTS RELATING TO CERTAIN CONSUMER CREDIT TRANSACTIONS.
(a) In General.--Chapter 2 of the Truth in Lending Act (15 U.S.C. 1631 et seq.) is amended by inserting after section 129B (as added by section 201) the following new section:
“SEC. 129C. ESCROW OR IMPOUND ACCOUNTS RELATING TO CERTAIN CONSUMER CREDIT TRANSACTIONS.
“(a) In General.--Except as provided in subsection (b) or (c), a creditor, in connection with the formation or consummation of a consumer credit transaction secured by a first lien on the principal dwelling of the consumer, other than a consumer credit transaction under an open end credit plan or a reverse mortgage, shall establish, at the time of the consummation of such transaction, an escrow or impound account for the payment of taxes and hazard insurance, and, if applicable, flood insurance, mortgage insurance, ground rents, and any other required periodic payments or premiums with respect to the property or the loan terms, as provided in, and in accordance with, this section.
“(b) When Required.--No impound, trust, or other type of account for the payment of property taxes, insurance premiums, or other purposes relating to the property may be required as a condition of a real property sale contract or a loan secured by a first deed of trust or mortgage on the principal dwelling of the consumer, other than a consumer credit transaction under an open end credit plan or a reverse mortgage, except when--
“(1) any such impound, trust, or other type of escrow or impound account for such purposes is required by Federal or State law;
“(2) a loan is made, guaranteed, or insured by a State or Federal governmental lending or insuring agency;
“(3) the consumer's debt-to-income ratio at the time the home mortgage is established taking into account income from all sources including the consumer's employment exceeds 50 percent;
“(4) the transaction is secured by a first mortgage or lien on the consumer's principal dwelling and the annual percentage rate on the credit, at the time of consummation of the transaction, will exceed by more than 3.0 percentage points the yield on Treasury securities having comparable periods of maturity on the 15th day of the month immediately preceding the month in which the application of the extension of credit is received by the creditor;
“(5) a consumer obtains a mortgage referred to in section 103(aa);
“(6) the original principal amount of such loan at the time of consummation of the transaction is--
“(A) 90 percent or more of the sale price, if the property involved is purchased with the proceeds of the loan; or
“(B) 90 percent or more of the appraised value of the property securing the loan;
“(7) the combined principal amount of all loans secured by the real property exceeds 95 percent of the appraised value of the property securing the loans at the time of consummation of the last mortgage transaction;
“(8) the consumer was the subject of a proceeding under title 11, United States Code, at any time during the 7-year period preceding the date of the transaction (as determined on the basis of the date of entry of the order for relief or the date of adjudication, as the case may be, with respect to such proceeding and included in a consumer report on the consumer under the Fair Credit Reporting Act); or
“(9) so required by the Board pursuant to regulation.
“(c) Duration of Mandatory Escrow or Impound Account.--An escrow or impound account established pursuant to subsection (b), shall remain in existence for a minimum period of 5 years and until such borrower has sufficient equity in the dwelling securing the consumer credit transaction so as to no longer be required to maintain private mortgage insurance, or such other period as may be provided in regulations to address situations such as borrower delinquency, unless the underlying mortgage establishing the account is terminated.
“(d) Clarification on Escrow Accounts for Loans Not Meeting Statutory Test.--For mortgages not covered by the requirements of subsection (b), no provision of this section shall be construed as precluding the establishment of an impound, trust, or other type of account for the payment of property taxes, insurance premiums, or other purposes relating to the property--
“(1) on terms mutually agreeable to the parties to the loan;
“(2) at the discretion of the lender or servicer, as provided by the contract between the lender or servicer and the borrower; or
“(3) pursuant to the requirements for the escrowing of flood insurance payments for regulated lending institutions in section 102(d) of the Flood Disaster Protection Act of 1973.
“(e) Administration of Mandatory Escrow or Impound Accounts.--
“(1) In general.--Except as may otherwise be provided for in this title or in regulations prescribed by the Board, escrow or impound accounts established pursuant to subsection (b) shall be established in a federally insured depository institution.
“(2) Administration.--Except as provided in this section or regulations prescribed under this section, an escrow or impound account subject to this section shall be administered in accordance with--
“(A) the Real Estate Settlement Procedures Act of 1974 and regulations prescribed under such Act;
“(B) the Flood Disaster Protection Act of 1973 and regulations prescribed under such Act; and
“(C) the law of the State, if applicable, where the real property securing the consumer credit transaction is located.
“(3) Applicability of payment of interest.--If prescribed by applicable State or Federal law, each creditor shall pay interest to the consumer on the amount held in any impound, trust, or escrow account that is subject to this section in the manner as prescribed by that applicable State or Federal law.
“(4) Penalty coordination with respa.--Any action or omission on the part of any person which constitutes a violation of the Real Estate Settlement Procedures Act of 1974 or any regulation prescribed under such Act for which the person has paid any fine, civil money penalty, or other damages shall not give rise to any additional fine, civil money penalty, or other damages under this section, unless the action or omission also constitutes a direct violation of this section.
“(f) Disclosures Relating to Mandatory Escrow or Impound Account.--In the case of any impound, trust, or escrow account that is subject to this section, the creditor shall disclose by written notice to the consumer at least 3 business days before the consummation of the consumer credit transaction giving rise to such account or in accordance with timeframes established in prescribed regulations the following information:
“(1) The fact that an escrow or impound account will be established at consummation of the transaction.
“(2) The amount required at closing to initially fund the escrow or impound account.
“(3) The amount, in the initial year after the consummation of the transaction, of the estimated taxes and hazard insurance, including flood insurance, if applicable, and any other required periodic payments or premiums that reflects, as appropriate, either the taxable assessed value of the real property securing the transaction, including the value of any improvements on the property or to be constructed on the property (whether or not such construction will be financed from the proceeds of the transaction) or the replacement costs of the property.
“(4) The estimated monthly amount payable to be escrowed for taxes, hazard insurance (including flood insurance, if applicable) and any other required periodic payments or premiums.
“(5) The fact that, if the consumer chooses to terminate the account at the appropriate time in the future, the consumer will become responsible for the payment of all taxes, hazard insurance, and flood insurance, if applicable, as well as any other required periodic payments or premiums on the property unless a new escrow or impound account is established.
“(g) Definitions.--For purposes of this section, the following definitions shall apply:
“(1) Flood insurance.--The term ‘flood insurance' means flood insurance coverage provided under the national flood insurance program pursuant to the National Flood Insurance Act of 1968.
“(2) Hazard insurance.--The term ‘hazard insurance' shall have the same meaning as provided for ‘hazard insurance', ‘casualty insurance', ‘homeowner's insurance', or other similar term under the law of the State where the real property securing the consumer credit transaction is located.”.
(b) Implementation.--
(1) Regulations.--The Board of Governors of the Federal Reserve System, the Comptroller of the Currency, the Director of the Office of Thrift Supervision, the Federal Deposit Insurance Corporation, the National Credit Union Administration Board, (hereafter in this Act referred to as the “Federal banking agencies”) and the Federal Trade Commission shall prescribe, in final form, such regulations as determined to be necessary to implement the amendments made by subsection (a) before the end of the 180-day period beginning on the date of the enactment of this Act.
(2) Effective date.--The amendments made by subsection (a) shall only apply to covered mortgage loans consummated after the end of the 1-year period beginning on the date of the publication of final regulations in the Federal Register.
(c) Clerical Amendment.--The table of sections for chapter 2 of the Truth in Lending Act is amended by inserting after the item relating to section 129B (as added by section 201) the following new item:
“129C. Escrow or impound accounts relating to certain consumer credit transactions.”.
SEC. 602. DISCLOSURE NOTICE REQUIRED FOR CONSUMERS WHO WAIVE ESCROW SERVICES.
(a) In General.--Section 129C of the Truth in Lending Act (as added by section 601) is amended by adding at the end the following new subsection:
“(h) Disclosure Notice Required for Consumers Who Waive Escrow Services.--
“(1) In general.--If--
“(A) an impound, trust, or other type of account for the payment of property taxes, insurance premiums, or other purposes relating to real property securing a consumer credit transaction is not established in connection with the transaction; or
“(B) a consumer chooses, at any time after such an account is established in connection with any such transaction and in accordance with any statute, regulation, or contractual agreement, to close such account, the creditor or servicer shall provide a timely and clearly written disclosure to the consumer that advises the consumer of the responsibilities of the consumer and implications for the consumer in the absence of any such account.
“(2) Disclosure requirements.--Any disclosure provided to a consumer under paragraph (1) shall include the following:
“(A) Information concerning any applicable fees or costs associated with either the non-establishment of any such account at the time of the transaction, or any subsequent closure of any such account.
“(B) A clear and prominent notice that the consumer is responsible for personally and directly paying the non-escrowed items, in addition to paying the mortgage loan payment, in the absence of any such account, and the fact that the costs for taxes, insurance, and related fees can be substantial.
“(C) A clear explanation of the consequences of any failure to pay non-escrowed items, including the possible requirement for the forced placement of insurance by the creditor or servicer and the potentially higher cost (including any potential commission payments to the servicer) or reduced coverage for the consumer in the event of any such creditor-placed insurance.”.
(b) Implementation.--
(1) Regulations.--The Federal banking agencies and the Federal Trade Commission shall prescribe, in final form, such regulations as such agencies determine to be necessary to implement the amendments made by subsection (a) before the end of the 180-day period beginning on the date of the enactment of this Act.
(2) Effective date.--The amendments made by subsection (a) shall only apply in accordance with the regulations established in paragraph (1) and beginning on the date occurring 180-days after the date of the publication of final regulations in the Federal Register.
SEC. 603. REAL ESTATE SETTLEMENT PROCEDURES ACT OF 1974 AMENDMENTS.
(a) Servicer Prohibitions.--Section 6 of the Real Estate Settlement Procedures Act of 1974 (12 U.S.C. 2605) is amended by adding at the end the following new subsections:
“(k) Servicer Prohibitions.--
“(1) In general.--A servicer of a federally related mortgage shall not--
“(A) obtain force-placed hazard insurance unless there is a reasonable basis to believe the borrower has failed to comply with the loan contract's requirements to maintain property insurance;
“(B) charge fees for responding to valid qualified written requests (as defined in regulations which the Secretary shall prescribe) under this section;
“(C) fail to take timely action to respond to a borrower's requests to correct errors relating to allocation of payments, final balances for purposes of paying off the loan, or avoiding foreclosure, or other standard servicer's duties;
“(D) fail to respond within 10 business days to a request from a borrower to provide the identity, address, and other relevant contact information about the owner assignee of the loan; or
“(E) fail to comply with any other obligation found by the Secretary, by regulation, to be appropriate to carry out the consumer protection purposes of this Act.
“(2) Force-placed insurance defined.--For purposes of this subsection and subsections (l) and (m), the term ‘force-placed insurance' means hazard insurance coverage obtained by a servicer of a federally related mortgage when the borrower has failed to maintain or renew hazard insurance on such property as required of the borrower under the terms of the mortgage.
“(l) Requirements for Force-Placed Insurance.--A servicer of a federally related mortgage shall not be construed as having a reasonable basis for obtaining force-placed insurance unless the requirements of this subsection have been met.
“(1) Written notices to borrower.--A servicer may not impose any charge on any borrower for force-placed insurance with respect to any property securing a federally related mortgage unless--
“(A) the servicer has sent, by first-class mail, a written notice to the borrower containing--
“(i) a reminder of the borrower's obligation to maintain hazard insurance on the property securing the federally related mortgage;
“(ii) a statement that the servicer does not have evidence of insurance coverage of such property;
“(iii) a clear and conspicuous statement of the procedures by which the borrower may demonstrate that the borrower already has insurance coverage; and
“(iv) a statement that the servicer may obtain such coverage at the borrower's expense if the borrower does not provide such demonstration of the borrower's existing coverage in a timely manner;
“(B) the servicer has sent, by first-class mail, a second written notice, at least 30 days after the mailing of the notice under subparagraph (A) that contains all the information described in each clauses of such subparagraph; and
“(C) the servicer has not received from the borrower any demonstration of hazard insurance coverage for the property securing the mortgage by the end of the 15-day period beginning on the date the notice under subparagraph (B) was sent by the servicer.
“(2) Sufficiency of demonstration.--A servicer of a federally related mortgage shall accept any reasonable form of written confirmation from a borrower of existing insurance coverage, which shall include the existing insurance policy number along with the identity of, and contact information for, the insurance company or agent.
“(3) Termination of force-placed insurance.--Within 15 days of the receipt by a servicer of confirmation of a borrower's existing insurance coverage, the servicer shall--
“(A) terminate the force-placed insurance; and
“(B) refund to the consumer all force-placed insurance premiums paid by the borrower during any period during which the borrower's insurance coverage and the force-placed insurance coverage were each in effect, and any related fees charged to the consumer's account with respect to the force-placed insurance during such period.
“(4) Clarification with respect to flood disaster protection act.--No provision of this section shall be construed as prohibiting a servicer from providing simultaneous or concurrent notice of a lack of flood insurance pursuant to section 102(e) of the Flood Disaster Protection Act of 1973.
“(m) Limitations on Force-Placed Insurance Charges.--All charges for force-placed insurance premiums shall be bona fide and reasonable in amount.
“(n) Prompt Crediting of Payments Required.--
“(1) In general.--All amounts received by a lender or a servicer on a home loan at the address where the borrower has been instructed to make payments shall be accepted and credited, or treated as credited, on the business day received, to the extent that the borrower has made the full contractual payment and has provided sufficient information to credit the account.
“(2) Scheduled method.--If a servicer uses the scheduled method of accounting, any regularly scheduled payment made prior to the scheduled due date shall be credited no later than the due date.
“(3) Notice of noncredit.--If any payment is received by a lender or a servicer on a home loan and not credited, or treated as credited, the borrower shall be notified within 10 business days by mail at the borrower's last known address of the disposition of the payment, the reason the payment was not credited, or treated as credited to the account, and any actions necessary by the borrower to make the loan current.”.
(b) Increase in Penalty Amounts.--Section 6(f) of the Real Estate Settlement Procedures Act of 1974 (12 U.S.C. 2605(f)) is amended--
(1) in paragraphs (1)(B) and (2)(B), by striking “$1,000” each place such term appears and inserting “$2,000”; and
(2) in paragraph (2)(B)(i), by striking “$500,000” and inserting “$1,000,000”.
(c) Decrease in Response Times.--Section 6(e) of the Real Estate Settlement Procedures Act of 1974 (12 U.S.C. 2605(e)) is amended--
(1) in paragraph (1)(A), by striking “20 days” and inserting “10 days”;
(2) in paragraph (2), by striking “60 days” and inserting “30 days”; and
(3) by adding at the end the following new paragraph:
“(4) Limited extension of response time.--The 30-day period described in paragraph (2) may be extended for not more than 30 days if, before the end of such 30-day period, the servicer notifies the borrower of the extension and the reasons for the delay in responding.”.
(d) Requests for Pay-Off Amounts.--Section 6(e) of the Real Estate Settlement Procedures Act of 1974 (12 U.S.C. 2605(e)) is amended by inserting after paragraph (4) (as added by subsection (c) of this section) the following new paragraph:
“(5) Requests for pay-off amounts.--A creditor or servicer shall send a payoff balance within 7 business days of the receipt of a written request for such balance from or on behalf of the borrower.”.
(e) Prompt Refund of Escrow Accounts Upon Payoff.--Section 6(g) of the Real Estate Settlement Procedures Act of 1974 (12 U.S.C. 2605(g)) is amended by adding at the end the following new sentence: “Any balance in any such account that is within the servicer's control at the time the loan is paid off shall be promptly returned to the borrower within 20 business days or credited to a similar account for a new mortgage loan to the borrower with the same lender.”.
SEC. 604. MORTGAGE SERVICING STUDIES REQUIRED.
(a) Mortgage Servicing Practices.--
(1) Study.--The Secretary of Housing and Urban Development, in consultation with the Federal banking agencies, and the Federal Trade Commission, shall conduct a comprehensive study on mortgage servicing practices and their potential for fraud and abuse.
(2) Issues to be included.--In addition to other issues the Secretary of Housing and Urban Development, the Federal banking agencies, and the Federal Trade Commission may determine to be appropriate and possibly pertinent to the study conducted under paragraph (1), the study shall include the following issues:
(A) A survey of the industry in order to examine the issue of the timely or effective posting of payments by servicers.
(B) The employment of daily interest when payments are made after a due date.
(C) The charging of late fees on the entire outstanding principal.
(D) The charging of interest on servicing fees.
(E) The utilization of collection practices that failed to comply with the Fair Debt Collection Practices Act.
(F) The charging of prepayment penalties when not authorized by either the note or law.
(G) The employment of unconscionable forbearance agreements.
(H) Foreclosure abuses.
(3) Report.--Before the end of the 12-month period beginning on the date of the enactment of this Act, the Secretary of Housing and Urban Development shall submit a report on the study conducted under this subsection to the Committee on Financial Services of the House of Representatives and the Committee on Banking, Housing, and Urban Affairs of the Senate.
(b) Mortgage Servicing Improvements.--
(1) Study.--The Secretary of Housing and Urban Development, in consultation with the Federal banking agencies, and the Federal Trade Commission, shall conduct a comprehensive study on means to improve the best practices of the mortgage servicing industry, and Federal and State laws governing such industry.
(2) Report.--Before the end of the 18-month period beginning on the date of the enactment of this Act, the Secretary of Housing and Urban Development shall submit a report on the study conducted under this subsection to the Committee on Financial Services of the House of Representatives and the Committee on Banking, Housing, and Urban Affairs of the Senate, together with such recommendations for administrative or legislative action as the Secretary, in consultation with the Board and the Commission, may determine to be appropriate.
SEC. 605. ESCROWS INCLUDED IN REPAYMENT ANALYSIS.
(a) In General.--Section 128(b) of the Truth in Lending Act (15 U.S.C. 1638(b)) is amended by adding at the end the following new paragraph:
“(4) Repayment analysis required to include escrow payments.--
“(A) In general.--In the case of any consumer credit transaction secured by a first mortgage or lien on the principal dwelling of the consumer, other than a consumer credit transaction under an open end credit plan or a reverse mortgage, for which an impound, trust, or other type of account has been or will be established in connection with the transaction for the payment of property taxes, hazard and flood (if any) insurance premiums, or other periodic payments or premiums with respect to the property, the information required to be provided under subsection (a) with respect to the number, amount, and due dates or period of payments scheduled to repay the total of payments shall take into account the amount of any monthly payment to such account for each such repayment in accordance with section 10(a)(2) of the Real Estate Settlement Procedures Act of 1974.
“(B) Assessment value.--The amount taken into account under subparagraph (A) for the payment of property taxes, hazard and flood (if any) insurance premiums, or other periodic payments or premiums with respect to the property shall reflect the taxable assessed value of the real property securing the transaction after the consummation of the transaction, including the value of any improvements on the property or to be constructed on the property (whether or not such construction will be financed from the proceeds of the transaction), if known, and the replacement costs of the property for hazard insurance, in the initial year after the transaction.”.
TITLE VII--APPRAISAL ACTIVITIES
SEC. 701. PROPERTY APPRAISAL REQUIREMENTS.
Section 129 of the Truth in Lending Act (15 U.S.C. 1639) is amended by inserting after subsection (u) (as added by section 303(f)) the following new subsection:
“(v) Property Appraisal Requirements.--
“(1) In general.--A creditor may not extend credit in the form of a mortgage referred to in section 103(aa) to any consumer without first obtaining a written appraisal of the property to be mortgaged prepared in accordance with the requirements of this subsection.
“(2) Appraisal requirements.--
“(A) Physical property visit.--An appraisal of property to be secured by a mortgage referred to in section 103(aa) does not meet the requirement of this subsection unless it is performed by a qualified appraiser who conducts a physical property visit of the interior of the mortgaged property.
“(B) Second appraisal under certain circumstances.--
“(i) In general.--If the purpose of a mortgage referred to in section 103(aa) is to finance the purchase or acquisition of the mortgaged property from a person within 180 days of the purchase or acquisition of such property by that person at a price that was lower than the current sale price of the property, the creditor shall obtain a second appraisal from a different qualified appraiser. The second appraisal shall include an analysis of the difference in sale prices, changes in market conditions, and any improvements made to the property between the date of the previous sale and the current sale.
“(ii) No cost to consumer.--The cost of any second appraisal required under clause (i) may not be charged to the consumer.
“(C) Qualified appraiser defined.--For purposes of this subsection, the term ‘qualified appraiser' means a person who--
“(i) is certified or licensed by the State in which the property to be appraised is located; and
“(ii) performs each appraisal in conformity with the Uniform Standards of Professional Appraisal Practice and title XI of the Financial Institutions Reform, Recovery, and Enforcement Act of 1989, and the regulations prescribed under such title, as in effect on the date of the appraisal.
“(3) Free copy of appraisal.--A creditor shall provide 1 copy of each appraisal conducted in accordance with this subsection in connection with a mortgage referred to in section 103(aa) to the consumer without charge, and at least 3 days prior to the transaction closing date.
“(4) Consumer notification.--At the time of the initial mortgage application, the consumer shall be provided with a statement by the creditor that any appraisal prepared for the mortgage is for the sole use of the creditor, and that the consumer may choose to have a separate appraisal conducted at their own expense.
“(5) Violations.--In addition to any other liability to any person under this title, a creditor found to have willfully failed to obtain an appraisal as required in this subsection shall be liable to the consumer for the sum of $2,000.”.
SEC. 702. UNFAIR AND DECEPTIVE PRACTICES AND ACTS RELATING TO CERTAIN CONSUMER CREDIT TRANSACTIONS.
(a) In General.--Chapter 2 of the Truth in Lending Act (15 U.S.C. 1631 et seq.) is amended by inserting after section 129C (as added by section 601) the following new section:
“SEC. 129D. UNFAIR AND DECEPTIVE PRACTICES AND ACTS RELATING TO CERTAIN CONSUMER CREDIT TRANSACTIONS.
“(a) In General.--It shall be unlawful, in providing any services for a consumer credit transaction secured by the principal dwelling of the consumer, to engage in any unfair or deceptive act or practice as described in or pursuant to regulations prescribed under this section.
“(b) Appraisal Independence.--For purposes of subsection (a), unfair and deceptive practices shall include--
“(1) any appraisal of a property offered as security for repayment of the consumer credit transaction that is conducted in connection with such transaction in which a person with an interest in the underlying transaction compensates, coerces, extorts, colludes, instructs, induces, bribes, or intimidates a person conducting or involved in an appraisal, or attempts, to compensate, coerce, extort, collude, instruct, induce, bribe, or intimidate such a person, for the purpose of causing the appraised value assigned, under the appraisal, to the property to be based on any factor other than the independent judgment of the appraiser;
“(2) mischaracterizing, or suborning any mischaracterization of, the appraised value of the property securing the extension of the credit;
“(3) seeking to influence an appraiser or otherwise to encourage a targeted value in order to facilitate the making or pricing of the transaction; and
“(4) failing to timely compensate an appraiser for a completed appraisal regardless of whether the transaction closes.
“(c) Exceptions.--The requirements of subsection (b) shall not be construed as prohibiting a mortgage lender, mortgage broker, mortgage banker, real estate broker, appraisal management company, employee of an appraisal management company, or any other person with an interest in a real estate transaction from asking an appraiser to provide 1 or more of the following services:
“(1) Consider additional, appropriate property information, including the consideration of additional comparable properties to make or support an appraisal.
“(2) Provide further detail, substantiation, or explanation for the appraiser's value conclusion.
“(3) Correct errors in the appraisal report.
“(d) Rulemaking Proceedings.--The Board, the Comptroller of the Currency, the Director of the Office of Thrift Supervision, the Federal Deposit Insurance Corporation, the National Credit Union Administration Board, and the Federal Trade Commission--
“(1) shall, for purposes of this section, jointly prescribe regulations defining with specificity acts or practices which are unfair or deceptive in the provision of mortgage lending services for a consumer credit transaction secured by the principal dwelling of the consumer or mortgage brokerage services for such a transaction and defining any terms in this section or such regulations; and
“(2) may jointly issue interpretive guidelines and general statements of policy with respect to unfair or deceptive acts or practices in the provision of mortgage lending services for a consumer credit transaction secured by the principal dwelling of the consumer and mortgage brokerage services for such a transaction, within the meaning of subsections (a), (b), and (c).
“(e) Penalties.--
“(1) First violation.--In addition to the enforcement provisions referred to in section 130, each person who violates this section shall forfeit and pay a civil penalty of not more than $10,000 for each day any such violation continues.
“(2) Subsequent violations.--In the case of any person on whom a civil penalty has been imposed under paragraph (1), paragraph (1) shall be applied by substituting ‘$20,000' for ‘$10,000' with respect to all subsequent violations.
“(3) Assessment.--The agency referred to in subsection (a) or (c) of section 108 with respect to any person described in paragraph (1) shall assess any penalty under this subsection to which such person is subject.”.
(b) Clerical Amendment.--The table of sections for chapter 2 of the Truth in Lending Act is amended by inserting after the item relating to section 129C (as added by section 601) the following new item:
“129D. Unfair and deceptive practices and acts relating to certain consumer credit transactions.”.
SEC. 703. APPRAISAL SUBCOMMITTEE OF FIEC, APPRAISER INDEPENDENCE, AND APPROVED APPRAISER EDUCATION.
(a) Consumer Protection Mission.--
(1) Purpose.--A purpose for the establishment and operation of the Appraisal Subcommittee of the Financial Institutions Examination Council (hereafter in this section referred to as the “Appraisal Subcommittee”) shall be to establish a consumer protection mandate.
(2) Functions of appraisal subcommittee.--It shall be a function of the Appraisal Subcommittee to protect the consumer from improper appraisal practices and the predations of unlicensed appraisers.
(3) Threshold levels.--In establishing a threshold level under section 1112(b) of the Financial Institutions Reform, Recovery, and Enforcement Act of 1989 (12 U.S.C. 3341(b)), each agency shall determine in writing that the threshold level provides reasonable protection for consumers who purchase 1-4 unit single-family residences.
(b) Annual Report of Appraisal Subcommittee.--The annual report of the Appraisal Subcommittee under section 1103(a)(4) of Financial Institutions Reform, Recovery, and Enforcement Act of 1989 shall detail the activities of the Appraisal Subcommittee, including the results of all audits of State appraiser regulatory agencies, and provide an accounting of disapproved actions and warnings taken in the previous year, including a description of the conditions causing the disapproval.
(c) Open Meetings.--All meetings of the Appraisal Subcommittee shall be held in public session after notice in the Federal Register.
(d) Regulations.--The Appraisal Subcommittee may prescribe regulations after notice and opportunity for comment. Any regulations prescribed by the Appraisal Subcommittee shall (unless otherwise provided in this section or title XI of the Financial Institutions Reform, Recovery, and Enforcement Act of 1989) be limited to the following functions: temporary practice, national registry, information sharing, and enforcement. For purposes of prescribing regulations, the Appraisal Subcommittee shall establish an advisory committee of industry participants, including appraisers, lenders, consumer advocates, and government agencies, and hold regular meetings.
(e) Field Appraisals and Appraisal Reviews.--All field appraisals performed at a property within a State shall be prepared by appraisers licensed in the State where the property is located. All Uniform Standards of Professional Appraisal Practice-compliant appraisal reviews shall be performed by an appraiser who is duly licensed by a State appraisal board.
(f) State Agency Reporting Requirement.--Each State with an appraiser certifying and licensing agency whose certifications and licenses comply with title XI of the Financial Institutions Reform, Recovery, and Enforcement Act of 1989 shall transmit reports on sanctions, disciplinary actions, license and certification revocations, and license and certification suspensions on a timely basis to the national registry of the Appraisal Subcommittee.
(g) Registry Fees Modified.--
(1) In general.--The annual registry fees for persons performing appraisals in federally related transactions shall be increased from $25 to $40. The maximum amount up to which the Appraisal Subcommittee may adjust any registry fees shall be increased from $50 to $80 per annum. The Appraisal Subcommittee shall consider at least once every 5 years whether to adjust the dollar amount of the registry fees to account for inflation. In implementing any change in registry fees, the Appraisal Subcommittee shall provide flexibility to the States for multi-year certifications and licenses already in place, as well as a transition period to implement the changes in registry fees.
(2) Incremental revenues.--Incremental revenues collected pursuant to the increases required by this section shall be placed in a separate account at the United States Treasury, entitled the Appraisal Subcommittee Account.
(h) Grants and Reports.--
(1) In general.--Amounts appropriated for or collected by the Appraisal Subcommittee after the date of the enactment of this Act shall, in addition to other uses authorized, be used--
(A) to make grants to State appraiser regulatory agencies to help defray those costs relating to enforcement activities; and
(B) to report to all State appraiser certifying and licensing agencies when a license or certification is surrendered, revoked, or suspended.
(2) Limitation on obligations.--Obligations authorized under this section may not exceed 75 percent of the fiscal year total of incremental increase in fees collected and deposited in the Appraisal Subcommittee Account pursuant to section 703(g) of this Act.
(i) Criteria.--
(1) Definition.--For purposes of this section and title XI of the Financial Institutions Reform, Recovery, and Enforcement Act of 1989 (notwithstanding section 1116(c) of such title), the term “State licensed appraiser” means an individual who has satisfied the requirements for State licensing in a State or territory whose criteria for the licensing of a real estate appraiser currently meet or exceed the minimum criteria issued by the Appraisal Qualifications Board of The Appraisal Foundation for the licensing of real estate appraisers.
(2) Minimum qualification requirements.--Any requirements established for individuals in the position of “Trainee Appraiser” and “Supervisory Appraiser” shall meet or exceed the minimum qualification requirements of the Appraiser Qualifications Board of The Appraisal Foundation. The Appraisal Subcommittee shall have the authority to enforce these requirements.
(j) Monitoring of State Appraiser Certifying and Licensing Agencies.--The Appraisal Subcommittee shall monitor State appraiser certifying and licencing agencies for the purpose of determining whether a State agency's funding and staffing are consistent with the requirements of title XI of the Financial Institutions Reform, Recovery, and Enforcement Act of 1989, whether a State agency processes complaints and completes exams in a reasonable time period, and whether a State agency reports claims and disciplinary actions on a timely basis to the national registry maintained by the Appraisal Subcommittee. The Appraisal Subcommittee shall have the authority to impose interim sanctions and suspensions.
(k) Reciprocity.--A State appraiser certifying or licensing agency shall issue a reciprocal certification or license for an individual from another State when--
(1) the appraiser licensing and certification program of such other State is in compliance with the provisions of this title; and
(2) the appraiser holds a valid certification from a State whose requirements for certification or licensing meet or exceed the licensure standards established by the State where an individual seeks appraisal licensure.
(l) Consideration of Professional Appraisal Designations.--No provision of section 1122(d) of the Financial Institutions Reform, Recovery, and Enforcement Act of 1989 shall be construed as prohibiting consideration of designations conferred by recognized national professional appraisal organizations, such as sponsoring organizations of The Appraisal Foundation.
(m) Appraiser Independence.--
(1) Prohibitions on interested parties in a real estate transaction.--No mortgage lender, mortgage broker, mortgage banker, real estate broker, appraisal management company, employee of an appraisal management company, nor any other person with an interest in a real estate transaction involving an appraisal shall improperly influence, or attempt to improperly influence, through coercion, extortion, collusion, compensation, instruction, inducement, intimidation, non-payment for services rendered, or bribery, the development, reporting, result, or review of a real estate appraisal sought in connection with a mortgage loan.
(2) Exceptions.--The requirements of paragraph (1) shall not be construed as prohibiting a mortgage lender, mortgage broker, mortgage banker, real estate broker, appraisal management company, employee of an appraisal management company, or any other person with an interest in a real estate transaction from asking an appraiser to provide 1 or more of the following services:
(A) Consider additional, appropriate property information, including the consideration of additional comparable properties to make or support an appraisal.
(B) Provide further detail, substantiation, or explanation for the appraiser's value conclusion.
(C) Correct errors in the appraisal report.
(3) Prohibitions on conflicts of interest.--No certified or licensed appraiser conducting an appraisal may have a direct or indirect interest, financial or otherwise, in the property or transaction involving the appraisal.
(4) Mandatory reporting.--Any mortgage lender, mortgage broker, mortgage banker, real estate broker, appraisal management company, employee of an appraisal management company, or any other person with an interest in a real estate transaction involving an appraisal who has a reasonable basis to believe an appraiser is violating applicable laws, or is otherwise engaging in unethical conduct, shall refer the matter to the applicable State appraiser certifying and licensing agency.
(5) Regulations.--The Federal financial institutions regulatory agencies (as defined in section 1003(1) of the Federal Financial Institutions Examination Council Act of 1978) shall prescribe such regulations as may be necessary to carry out the provisions of this subsection.
(6) Penalties.--Any person who violates any provision of this subsection shall be subject to civil penalties under section 8(i)(2) of the Federal Deposit Insurance Act or section 206(k)(2) of the Federal Credit Union Act, as appropriate.
(7) Proceeding.--A proceeding with respect to a violation of this subsection shall be an administrative proceeding which may be conducted by a Federal financial institutions regulatory agency in accordance with the procedures set forth in subchapter II of chapter 5 of title 5, United States Code.
(n) Approved Education.--The Appraisal Subcommittee shall encourage the States to accept courses approved by the Appraiser Qualification Board's Course Approval Program.
SEC. 704. STUDY REQUIRED ON IMPROVEMENTS IN APPRAISAL PROCESS AND COMPLIANCE PROGRAMS.
(a) Study.--The Comptroller General shall conduct a comprehensive study on possible improvements in the appraisal process generally, and specifically on the consistency in and the effectiveness of, and possible improvements in, State compliance efforts and programs in accordance with title XI of the Financial Institutions Reform, Recovery, and Enforcement Act of 1989. In addition, this study shall examine the existing de minimis loan levels established by Federal regulators for compliance under title XI and whether there is a need to revise them to reflect the addition of consumer protection to the purposes and functions of the Appraisal Subcommittee.
(b) Report.--Before the end of the 18-month period beginning on the date of the enactment of this Act, the Comptroller General shall submit a report on the study under subsection (a) to the Committee on Financial Services of the House of Representatives and the Committee on Banking, Housing, and Urban Affairs of the Senate, together with such recommendations for administrative or legislative action, at the Federal or State level, as the Comptroller General may determine to be appropriate.
SEC. 705. CONSUMER APPRAISAL DISCLOSURE.
(a) In General.--Chapter 2 of the Truth in Lending Act (15 U.S.C. 1631 et seq.) is amended by inserting after section 129D (as added by section 702) the following new section:
“SEC. 129E. CONSUMER APPRAISAL DISCLOSURE.
“In any case in which an appraisal is performed in connection with an extension of credit secured by an interest in real property, the creditor or other mortgage originator shall make available to the applicant for the extension of credit a copy of all appraisal valuation reports upon completion but no later than 3 business days prior to the transaction closing date.”.
(b) Clerical Amendment.--The table of sections for chapter 2 of the Truth in Lending Act is amended by inserting after the item relating to section 129D (as added by section 702) the following new item:
“129E. Consumer appraisal disclosure.”.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
House amendment offered
November 15, 2007
View full timeline
House amendment offered
November 15, 2007
House amendment agreed to: On agreeing to the Kanjorski amendment (A003) Agreed to by voice vote.
November 15, 2007 • 1:30 PM
Amendment agreed to Committee of the Whole
November 15, 2007 • 1:30 PM
House amendment offered/reported by : Amendment (A003) offered by Mr. Kanjorski.(consideration: CR H14006-14011; text: CR H14006-14010)
November 15, 2007 • 1:19 PM
Amendment (A003) offered by Mr. Kanjorski. (consideration: CR H14006-14011; text: CR H14006-14010)
November 15, 2007 • 1:19 PM
On agreeing to the Kanjorski amendment (A003) Agreed to by voice vote.
November 15, 2007 • 1:30 PM