S.Amdt. 3834
What it does: Rewrites the text S.Amdt. 3630 would insert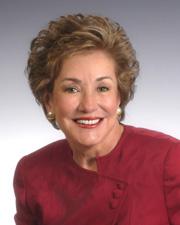 Sen. Elizabeth Dole (R-NC)
What it changes
1 change to S.Amdt. 3630 · shown in S.Amdt. 3630's text
Rewrites the text S.Amdt. 3630 would insert
Rewrites S.Amdt. 3630In place of the text S.Amdt. 3630 would insertIn S.Amdt. 3630 as proposed
Struck: SEC. ___. CREDIT FOR TRANSPORTATION OF FOOD FOR CHARITABLE PURPOSES.
Struck: (a) In General.--Subpart B of part IV of subchapter A of chapter 1, as amended by this Act, is amended by adding at the end the following new section:
Struck: "SEC. 30G. CREDIT FOR TRANSPORTATION OF FOOD FOR CHARITABLE PURPOSES.
Struck: "(a) Allowance of Credit.--There shall be allowed as a credit against the tax imposed by this chapter for the taxable year an amount equal to 25 cents for each mile for which the taxpayer uses a qualified truck for a qualified charitable purpose during the taxable year.
Show 12 more struck paragraphsShow less
Struck: "(b) Qualified Charitable Purpose.--For purposes of this section, the term 'qualified charitable purpose' means the transportation of food in connection with the hunger relief efforts of an organization which is described in section 501(c)(3) and is exempt from taxation under section 501(a) (other than a private foundation, as defined in section 509(a), which is not an operating foundation, as defined in section 4942(j)(3)).
Struck: "(c) Qualified Truck.--For purposes of this section, the term 'qualified truck' means a truck which--
Struck: "(1) has a capacity of not less than 1,760 cubic square feet,
Struck: "(2) is owned, leased, or operated by the taxpayer, and
Struck: "(3) is ordinarily used for hauling property in the course of a business.
Struck: "(d) Other Rules.--
Struck: "(1) Denial of double benefit.--No credit shall be allowed under this section with respect to any amount for which a deduction is allowed under any other provision of this chapter.
Struck: "(2) No credit where taxpayer is compensated.--No credit shall be allowed under this section if the taxpayer receives compensation in connection with the use of the qualified truck for the qualified charitable purpose.
Struck: "(3) Capacity requirement.--No credit shall be allowed under this section unless at least 50 percent of the hauling capacity of the qualified truck (measured in cubic square feet) is used for the qualified charitable purpose.".
Struck: (b) Conforming Amendment.--The table of sections for subpart B of part IV of subchapter A of chapter 1, as amended by this Act, is amended by adding at the end the following new item:
Struck: "Sec. 30G. Credit for transportation of food for charitable purposes.".
Struck: (c) Effective Date.--The amendments made by this section shall apply to taxable years ending after December 31, 2007.
Inserted: SEC. ___. 2-YEAR EXTENSION AND EXPANSION OF CHARITABLE DEDUCTION FOR CONTRIBUTIONS OF FOOD INVENTORY.
Inserted: (a) In General.--Section 170(e)(3)(C) (relating to special rule for certain contributions of inventory and other property) is amended--
Inserted: (1) by striking "December 31, 2007" in clause (iv) and inserting "December 31, 2009", and
Inserted: (2) by redesignating clauses (iii) and (iv) as clauses (iv) and (v), respectively, and by inserting after clause (ii) the following new clause:
Inserted: "(iii) Determination of basis.--If a taxpayer--
Inserted: "(I) does not account for inventories under section 471, and
Inserted: "(II) is not required to capitalize indirect costs under section 263A, the taxpayer may elect, solely for purposes of subparagraph (B), to treat the basis of any apparently wholesome food as being equal to 25 percent of the fair market value of such food.".
Inserted: (b) Effective Date.--The amendments made by this section shall apply to contributions made after December 31, 2007.
Inserted: SEC. ___. MILEAGE REIMBURSEMENTS TO CHARITABLE VOLUNTEERS EXCLUDED FROM GROSS INCOME.
Inserted: (a) In General.--Part III of subchapter B of chapter 1 is amended by inserting after section 139A the following new section:
Inserted: "SEC. 139B. MILEAGE REIMBURSEMENTS TO CHARITABLE VOLUNTEERS.
Inserted: "(a) In General.--Gross income of an individual does not include amounts received, from an organization described in section 170(c), as reimbursement of operating expenses with respect to use of a passenger automobile for the benefit of such organization. The preceding sentence shall apply only to the extent that such reimbursement would be deductible under this chapter if section 274(d) were applied--
Show 13 more inserted paragraphsShow less
Inserted: "(1) by using the standard business mileage rate in effect under section 162(a) at the time of such use, and
Inserted: "(2) as if the individual were an employee of an organization not described in section 170(c).
Inserted: "(b) Application to Volunteer Services Only.--Subsection (a) shall not apply with respect to any expenses relating to the performance of services for compensation.
Inserted: "(c) No Double Benefit.--No deduction or credit shall be allowed under any other provision of this title with respect to the expenses excludable from gross income under subsection (a).".
Inserted: (b) Clerical Amendment.--The table of sections for part III of subchapter B of chapter 1 of the Internal Revenue Code of 1986 is amended by inserting after the item relating to section 139A and inserting the following new item:
Inserted: "Sec. 139B. Reimbursement for use of passenger automobile for charity.".
Inserted: (c) Effective Date.--The amendments made by this section shall apply to taxable years beginning after the date of the enactment of this Act.
Inserted: SEC. ___. BASIS ADJUSTMENT TO STOCK OF S CORPORATIONS MAKING CHARITABLE CONTRIBUTIONS OF PROPERTY.
Inserted: (a) Technical Amendment Related to Section 1203 of the Pension Protection Act of 2006.--Subsection (d) of section 1366 is amended by adding at the end the following new paragraph:
Inserted: "(4) Application of limitation on charitable contributions.--In the case of any charitable contribution of property to which the second sentence of section 1367(a)(2) applies, paragraph (1) shall not apply to the extent of the excess (if any) of--
Inserted: "(A) the shareholder's pro rata share of such contribution, over
Inserted: "(B) the shareholder's pro rata share of the adjusted basis of such property.".
Inserted: (b) Effective Date.--The amendment made by this section shall take effect as if included in the provision of the Pension Protection Act of 2006 to which it relates.
Original wording
In lieu of the matter proposed to be inserted, insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 3834. Mrs. DOLE (for herself, Mr. Grassley, and Mr. Lugar) submitted an amendment intended to be proposed to amendment SA 3630 submitted by Mrs. Dole and intended to be proposed to the bill H.R. 2419, to provide for the continuation of agricultural programs through fiscal year 2012, and for other purposes; which was ordered to lie on the table; as follows:
In lieu of the matter proposed to be inserted, insert the following:
SEC. ___. 2-YEAR EXTENSION AND EXPANSION OF CHARITABLE DEDUCTION FOR CONTRIBUTIONS OF FOOD INVENTORY.
(a) In General.--Section 170(e)(3)(C) (relating to special rule for certain contributions of inventory and other property) is amended--
(1) by striking “December 31, 2007” in clause (iv) and inserting “December 31, 2009”, and
(2) by redesignating clauses (iii) and (iv) as clauses (iv) and (v), respectively, and by inserting after clause (ii) the following new clause:
“(iii) Determination of basis.--If a taxpayer--
“(I) does not account for inventories under section 471, and
“(II) is not required to capitalize indirect costs under section 263A, the taxpayer may elect, solely for purposes of subparagraph (B), to treat the basis of any apparently wholesome food as being equal to 25 percent of the fair market value of such food.”.
(b) Effective Date.--The amendments made by this section shall apply to contributions made after December 31, 2007.
SEC. ___. MILEAGE REIMBURSEMENTS TO CHARITABLE VOLUNTEERS EXCLUDED FROM GROSS INCOME.
(a) In General.--Part III of subchapter B of chapter 1 is amended by inserting after section 139A the following new section:
“SEC. 139B. MILEAGE REIMBURSEMENTS TO CHARITABLE VOLUNTEERS.
“(a) In General.--Gross income of an individual does not include amounts received, from an organization described in section 170(c), as reimbursement of operating expenses with respect to use of a passenger automobile for the benefit of such organization. The preceding sentence shall apply only to the extent that such reimbursement would be deductible under this chapter if section 274(d) were applied--
“(1) by using the standard business mileage rate in effect under section 162(a) at the time of such use, and
“(2) as if the individual were an employee of an organization not described in section 170(c).
“(b) Application to Volunteer Services Only.--Subsection (a) shall not apply with respect to any expenses relating to the performance of services for compensation.
“(c) No Double Benefit.--No deduction or credit shall be allowed under any other provision of this title with respect to the expenses excludable from gross income under subsection (a).”.
(b) Clerical Amendment.--The table of sections for part III of subchapter B of chapter 1 of the Internal Revenue Code of 1986 is amended by inserting after the item relating to section 139A and inserting the following new item:
“Sec. 139B. Reimbursement for use of passenger automobile for charity.”.
(c) Effective Date.--The amendments made by this section shall apply to taxable years beginning after the date of the enactment of this Act.
SEC. ___. BASIS ADJUSTMENT TO STOCK OF S CORPORATIONS MAKING CHARITABLE CONTRIBUTIONS OF PROPERTY.
(a) Technical Amendment Related to Section 1203 of the Pension Protection Act of 2006.--Subsection (d) of section 1366 is amended by adding at the end the following new paragraph:
“(4) Application of limitation on charitable contributions.--In the case of any charitable contribution of property to which the second sentence of section 1367(a)(2) applies, paragraph (1) shall not apply to the extent of the excess (if any) of--
“(A) the shareholder's pro rata share of such contribution, over
“(B) the shareholder's pro rata share of the adjusted basis of such property.”.
(b) Effective Date.--The amendment made by this section shall take effect as if included in the provision of the Pension Protection Act of 2006 to which it relates.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
December 12, 2007