S.Amdt. 5129
What it does: Adds TITLE II--INCENTIVES FOR PLUG-IN ELECTRIC DRIVE VEHICLES on page 43, line 17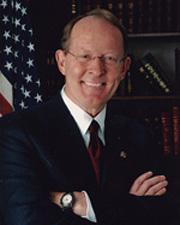 Sen. Lamar Alexander (R-TN)
What it changes
1 change to S. 3268
Adds TITLE II--INCENTIVES FOR PLUG-IN ELECTRIC DRIVE VEHICLES on page 43, line 17
Adds a titlePrinted pageInserted: TITLE II--INCENTIVES FOR PLUG-IN ELECTRIC DRIVE VEHICLES
Inserted: SEC. 21. CREDIT FOR NEW QUALIFIED PLUG-IN ELECTRIC DRIVE MOTOR VEHICLES.
Inserted: (a) In General.--Subpart B of part IV of subchapter A of chapter 1 of the Internal Revenue Code of 1986 (relating to other credits) is amended by adding at the end the following new section:
Inserted: "SEC. 30D. PLUG-IN ELECTRIC DRIVE MOTOR VEHICLE CREDIT.
Inserted: "(a) Allowance of Credit.--
Inserted: "(1) In general.--There shall be allowed as a credit against the tax imposed by this chapter for the taxable year an amount equal to the applicable amount with respect to each new qualified plug-in electric drive motor vehicle placed in service by the taxpayer during the taxable year.
Inserted: "(2) Applicable amount.--For purposes of paragraph (1), the applicable amount is the sum of--
Inserted: "(A) $2,000, plus
Inserted: "(B) $400 for each kilowatt hour of traction battery capacity in excess of 2.5 kilowatt hours.
Inserted: "(b) Limitations.--
Inserted: "(1) Limitation based on weight.--The amount of the credit allowed under subsection (a) by reason of subsection (a)(2)(A) shall not exceed--
Inserted: "(A) $7,500, in the case of any new qualified plug-in electric drive motor vehicle with a gross vehicle weight rating of not more than 10,000 pounds,
Show 135 more inserted paragraphsShow less
Inserted: "(B) $10,000, in the case of any new qualified plug-in electric drive motor vehicle with a gross vehicle weight rating of more than 10,000 pounds but not more than 14,000 pounds,
Inserted: "(C) $15,000, in the case of any new qualified plug-in electric drive motor vehicle with a gross vehicle weight rating of more than 14,000 pounds but not more than 26,000 pounds, and
Inserted: "(D) $20,000, in the case of any new qualified plug-in electric drive motor vehicle with a gross vehicle weight rating of more than 26,000 pounds.
Inserted: "(2) Limitation based on amount of tax.--The credit allowed under subsection (a) for any taxable year shall not exceed the excess of--
Inserted: "(A) the sum of the regular tax liability (as defined in section 26(b)) plus the tax imposed by section 55, over
Inserted: "(B) the sum of the credits allowable under subpart A and section 27 for the taxable year.
Inserted: "(3) Limitation on number of passenger vehicles and light trucks eligible for credit.--No credit shall be allowed under subsection (a) for any new qualified plug-in electric drive motor vehicle which is a passenger vehicle or light truck in any calendar year following the calendar year which includes the first date on which the total number of such new qualified plug-in electric drive motor vehicles sold for use in the United States after December 31, 2007, is at least 250,000.
Inserted: "(c) New Qualified Plug-in Electric Drive Motor Vehicle.--For purposes of this section, the term 'new qualified plug-in electric drive motor vehicle' means a motor vehicle--
Inserted: "(1) which draws propulsion using one or more traction batteries with an aggregate capacity of not less than 2.5 kilowatt hours,
Inserted: "(2) which uses an offboard source of electricity to recharge one or more such batteries,
Inserted: "(3) which, where required for the applicable make and model, has received a certificate of conformity under the Clean Air Act, or which meets all Federal safety and emissions requirements for on-road use,
Inserted: "(4) the original use of which commences with the taxpayer,
Inserted: "(5) which is acquired for use or lease by the taxpayer and not for resale, and
Inserted: "(6) which is made by a manufacturer.
Inserted: "(d) Other Definitions and Special Rules.--For purposes of this section--
Inserted: "(1) Motor vehicle.--The term 'motor vehicle' means any vehicle which is manufactured primarily for use on public streets, roads, and highways (not including a vehicle operated exclusively on a rail or rails).
Inserted: "(2) Other terms.--The terms 'passenger automobile', 'light truck', and 'manufacturer' have the meanings given such terms in regulations prescribed by the Administrator of the Environmental Protection Agency for purposes of the administration of title II of the Clean Air Act (42 U.S.C. 7521 et seq.).
Inserted: "(3) Traction battery capacity.--Traction battery capacity shall be measured in kilowatt hours from a 100 percent state of charge to a zero percent state of charge.
Inserted: "(4) Reduction in basis.--For purposes of this subtitle, the basis of any property for which a credit is allowable under subsection (a) shall be reduced by the amount of such credit so allowed.
Inserted: "(5) No double benefit.--The amount of any deduction or other credit allowable under this chapter for a new qualified plug-in electric drive motor vehicle shall be reduced by the amount of credit allowed under subsection (a) for such vehicle for the taxable year.
Inserted: "(6) Property used by tax-exempt entity.--In the case of a vehicle the use of which is described in paragraph (3) or (4) of section 50(b) and which is not subject to a lease, the person who sold such vehicle to the person or entity using such vehicle shall be treated as the taxpayer that placed such vehicle in service, but only if such person clearly discloses to such person or entity in a document the amount of any credit allowable under subsection (a) with respect to such vehicle (determined without regard to subsection (b)(2)).
Inserted: "(7) Property used outside united states, etc., not qualified.--No credit shall be allowable under subsection (a) with respect to any property referred to in section 50(b)(1) or with respect to the portion of the cost of any property taken into account under section 179.
Inserted: "(8) Recapture.--The Secretary shall, by regulations, provide for recapturing the benefit of any credit allowable under subsection (a) with respect to any property which ceases to be property eligible for such credit (including recapture in the case of a lease period of less than the economic life of a vehicle).
Inserted: "(9) Election to not take credit.--No credit shall be allowed under subsection (a) for any vehicle if the taxpayer elects not to have this section apply to such vehicle.
Inserted: "(10) Interaction with air quality and motor vehicle safety standards.--Unless otherwise provided in this section, a motor vehicle shall not be considered eligible for a credit under this section unless such vehicle is in compliance with--
Inserted: "(A) the applicable provisions of the Clean Air Act for the applicable make and model year of the vehicle (or applicable air quality provisions of State law in the case of a State which has adopted such provision under a waiver under section 209(b) of the Clean Air Act), and
Inserted: "(B) the motor vehicle safety provisions of sections 30101 through 30169 of title 49, United States Code.
Inserted: "(e) Regulations.--
Inserted: "(1) In general.--Except as provided in paragraph (2), the Secretary shall promulgate such regulations as necessary to carry out the provisions of this section.
Inserted: "(2) Coordination in prescription of certain regulations.--The Secretary of the Treasury, in coordination with the Secretary of Transportation and the Administrator of the Environmental Protection Agency, shall prescribe such regulations as necessary to determine whether a motor vehicle meets the requirements to be eligible for a credit under this section.".
Inserted: (b) Coordination With Other Motor Vehicle Credits.--
Inserted: (1) Electric drive motor vehicles.--Paragraph (1) of section 30(c) of the Internal Revenue Code of 1986 is amended by adding at the end the following new flush sentence:
Inserted: "Such term shall not include any motor vehicle which is a new qualified plug-in electric drive motor vehicle (as defined by section 30D(c))."
Inserted: (2) New qualified fuel cell motor vehicles.--Paragraph (3) of section 30B(b) of such Code is amended by adding at the end the following new flush sentence: "Such term shall not include any motor vehicle which is a new qualified plug-in electric drive motor vehicle (as defined by section 30D(c))."
Inserted: (3) New qualified hybrid motor vehicles.--Paragraph (3) of section 30B(d) of such Code is amended by adding at the end the following new flush sentence:
Inserted: "Such term shall not include any motor vehicle which is a new qualified plug-in electric drive motor vehicle (as defined by section 30D(c))."
Inserted: (c) Conforming Amendments.--
Inserted: (1) Section 1016(a) of the Internal Revenue Code of 1986 is amended by striking "and" at the end of paragraph (36), by striking the period at the end of paragraph (37) and inserting ", and", and by adding at the end the following new paragraph:
Inserted: "(38) to the extent provided in section 30D(d)(5)."
Inserted: (2) Section 6501(m) of such Code is amended by inserting "30D(d)(10)" after "30C(e)(5)".
Inserted: (3) The table of sections for subpart B of part IV of such Code is amended by adding at the end the following new item:
Inserted: "Sec. 30D. Plug-in electric drive motor vehicle credit."
Inserted: (d) Conversion Kits.--
Inserted: (1) In general.--Section 30B of the Internal Revenue Code of 1986 (relating to alternative motor vehicle credit) is amended by redesignating subsections (i) and (j) as subsections (j) and (k), respectively, and by inserting after subsection (h) the following new subsection:
Inserted: "(i) Plug-in Conversion Credit.--
Inserted: "(1) In general.--For purposes of subsection (a), the plug-in conversion credit determined under this subsection with respect to any motor vehicle which is converted to a qualified plug-in electric drive motor vehicle is the lesser of--
Inserted: "(A) an amount equal to--
Inserted: "(i) $2,000, plus
Inserted: "(ii) $400 for each kilowatt hour of capacity of the plug-in traction battery module installed in such vehicle in excess of 2.5 kilowatt hours, or
Inserted: "(B) 50 percent of the cost of the plug-in traction battery module installed in such vehicle as part of such conversion.
Inserted: "(2) Limitations.--The amount of the credit allowed under this subsection shall not exceed $4,000 with respect to the conversion of any motor vehicle.
Inserted: "(3) Definitions and special rules.--For purposes of this subsection--
Inserted: "(A) Qualified plug-in electric drive motor vehicle.--The term 'qualified plug-in electric drive motor vehicle' means any new qualified plug-in electric drive motor vehicle (as defined in section 30D(c), determined without regard to paragraphs (4) and (6) thereof).
Inserted: "(B) Plug-in traction battery module.--The term 'plug-in traction battery module' means an electro-chemical energy storage device which--
Inserted: "(i) has a traction battery capacity of not less than 2.5 kilowatt hours,
Inserted: "(ii) is equipped with an electrical plug by means of which it can be energized and recharged when plugged into an external source of electric power,
Inserted: "(iii) consists of a standardized configuration and is mass produced,
Inserted: "(iv) has been tested and approved by the National Highway Transportation Safety Administration as compliant with applicable motor vehicle and motor vehicle equipment safety standards when installed by a mechanic with standardized training in protocols established by the battery manufacturer as part of a nationwide distribution program, and
Inserted: "(v) is certified by a battery manufacturer as meeting the requirements of clauses (i) through (iv).
Inserted: "(C) Credit allowed to lessor of battery module.--In the case of a plug-in traction battery module which is leased to the taxpayer, the credit allowed under this subsection shall be allowed to the lessor of the plug-in traction battery module.
Inserted: "(D) Credit allowed in addition to other credits.--The credit allowed under this subsection shall be allowed with respect to a motor vehicle notwithstanding whether a credit has been allowed with respect to such motor vehicle under this section (other than this subsection) in any preceding taxable year.
Inserted: "(4) Termination.--This subsection shall not apply to conversions made after December 31, 2010.".
Inserted: (2) Credit treated as part of alternative motor vehicle credit.--Section 30B(a) of such Code is amended by striking "and" at the end of paragraph (3), by striking the period at the end of paragraph (4) and inserting ", and", and by adding at the end the following new paragraph:
Inserted: "(5) the plug-in conversion credit determined under subsection (i).".
Inserted: (3) No recapture for vehicles converted to qualified plug-in electric drive motor vehicles.--Paragraph (8) of section 30B(h) of such Code is amended by adding at the end the following: ", except that no benefit shall be recaptured if such property ceases to eligible for such credit by reason of conversion to a qualified plug-in electric drive motor vehicle."
Inserted: (e) Effective Date.--The amendments made by this section shall apply to property placed in service after December 31, 2007, in taxable years beginning after such date.
Inserted: SEC. 22. CLASSIFICATION OF SMART METERS AS 5-YEAR PROPERTY.
Inserted: (a) In General.--Subparagraph (B) of section 168(e)(3) of the Internal Revenue Code of 1986 (relating to 5-year property) is amended--
Inserted: (1) by striking "and" at the end of clause (v),
Inserted: (2) by redesignating clause (vi) as clause (vii), and
Inserted: (3) by inserting after clause (v) the following new clause:
Inserted: "(vi) any advanced electricity time-based meter that--
Inserted: "(I) measures and records electricity usage data on a time differentiated basis,
Inserted: "(II) has 2-way communications capability,
Inserted: "(III) provides data that enables the electricity supplier to provide usage information to customers electronically, and
Inserted: "(IV) is placed in service before January 1, 2014, and".
Inserted: (b) Conforming Amendment.--Paragraph (3) of section 168(e) of such Code (relating to classification of certain property) is amended by striking "clause (vi)(I)" in the last sentence and inserting "clause (vii)(I)".
Inserted: (c) Effective Date.--The amendments made by this section shall apply to taxable years beginning after December 31, 2007.
Inserted: SEC. 23. ALTERNATIVE FUEL VEHICLE REFUELING PROPERTY CREDIT.
Inserted: (a) Increase in Credit Amount.--Section 30C of the Internal Revenue Code of 1986 is amended--
Inserted: (1) by striking "30 percent" in subsection (a) and inserting "50 percent", and
Inserted: (2) by striking "$30,000" in subsection (b)(1) and inserting "$50,000".
Inserted: (b) Expansion of Electric Property.--Subsection (c) of section 30C of the Internal Revenue Code of 1986 (relating to qualified alternative fuel vehicle refueling property) is amended--
Inserted: (1) by striking "and" at the end of paragraph (1),
Inserted: (2) by redesignating paragraph (2) as paragraph (3),
Inserted: (3) by striking "Any mixture--" and all that follows in paragraph (3)(B), as so redesignated, and inserting "Any mixture of biodiesel (as defined in section 40A(d)(1)) and diesel fuel (as defined in section 4083(a)(3)), determined without regard to any use of kerosene and containing at least 20 percent biodiesel.", and
Inserted: (4) by inserting after paragraph (1) the following new paragraph:
Inserted: "(2) paragraph (3)(B) of section 179A(d) applied to all electric property used to support the charging of electric vehicles, neighborhood electric vehicles, or plug-in hybrids, without regard to the gross vehicle weight rating of such vehicles, and".
Inserted: (c) Extension of Credit.--Section 30C(g) of the Internal Revenue Code of 1986 is amended--
Inserted: (1) by inserting "electric property and" before "property relating to hydrogen" in paragraph (1), and
Inserted: (2) by striking "December 31, 2009" in paragraph (2) and inserting "December 31, 2010".
Inserted: (d) Effective Date.--The amendments made by this section shall apply to property placed in service after the date of the enactment of this Act, in taxable years ending after such date.
Inserted: SEC. 24. INCENTIVES FOR MANUFACTURING FACILITIES PRODUCING PLUG-IN ELECTRIC DRIVE MOTOR VEHICLE AND COMPONENTS.
Inserted: (a) Deduction for Manufacturing Facilities.--Part VI of subchapter B of chapter 1 of the Internal Revenue Code of 1986 (relating to itemized deductions for individuals and corporations) is amended by inserting after section 179E the following new section:
Inserted: "SEC. 179F. EXPENSING FOR MANUFACTURING FACILITIES PRODUCING PLUG-IN ELECTRIC DRIVE MOTOR VEHICLE AND COMPONENTS.
Inserted: "(a) Treatment as Expenses.--A taxpayer may elect to treat the applicable percentage of the cost of any qualified plug-in electric drive motor vehicle manufacturing facility property as an expense which is not chargeable to a capital account. Any cost so treated shall be allowed as a deduction for the taxable year in which the qualified manufacturing facility property is placed in service.
Inserted: "(b) Applicable Percentage.--For purposes of subsection (a), the applicable percentage is--
Inserted: "(1) 100 percent, in the case of qualified plug-in electric drive motor vehicle manufacturing facility property which is placed in service before January 1, 2013, and
Inserted: "(2) 50 percent, in the case of qualified plug-in electric drive motor vehicle manufacturing facility property which is placed in service after December 31, 2012, and before January 1, 2015.
Inserted: "(c) Election.--
Inserted: "(1) In general.--An election under this section for any taxable year shall be made on the taxpayer's return of the tax imposed by this chapter for the taxable year. Such election shall be made in such manner as the Secretary may by regulations prescribe.
Inserted: "(2) Election irrevocable.--Any election made under this section may not be revoked except with the consent of the Secretary.
Inserted: "(d) Qualified Plug-in Electric Drive Motor Vehicle Manufacturing Facility Property.--For purposes of this section--
Inserted: "(1) In general.--The term 'qualified plug-in electric drive motor vehicle manufacturing facility property' means any qualified property--
Inserted: "(A) the original use of which commences with the taxpayer,
Inserted: "(B) which is placed in service by the taxpayer after the date of the enactment of this section and before January 1, 2015, and
Inserted: "(C) no written binding contract for the construction of which was in effect on or before the date of the enactment of this section.
Inserted: "(2) Qualified property.--
Inserted: "(A) In general.--The term 'qualified property' means any property which is a facility or a portion of a facility used for the production of--
Inserted: "(i) any new qualified plug-in electric drive motor vehicle (as defined by section 30D(c)), or
Inserted: "(ii) any eligible component.
Inserted: "(B) Eligible component.--The term 'eligible component' means any battery, any electric motor or generator, or any power control unit which is designed specifically for use in a new qualified plug-in electric drive motor vehicle (as so defined).
Inserted: "(e) Special Rule for Dual Use Property.--In the case of any qualified plug-in electric drive motor vehicle manufacturing facility property which is used to produce both qualified property and other property which is not qualified property, the amount of costs taken into account under subsection (a) shall be reduced by an amount equal to--
Inserted: "(1) the total amount of such costs (determined before the application of this subsection), multiplied by
Inserted: "(2) the percentage of property expected to be produced which is not qualified property.".
Inserted: (b) Refund of Credit for Prior Year Minimum Tax Liability.--Section 53 of the Internal Revenue Code of 1986 (relating to credit for prior year minimum tax liability) is amended by adding at the end the following new subsection:
Inserted: "(f) Election To Treat Amounts Attributable to Qualified Manufacturing Facility.--
Inserted: "(1) In general.--In the case of an eligible taxpayer, the amount determined under subsection (c) for the taxable year (after the application of subsection (e)) shall be increased by an amount equal to the applicable percentage of any qualified plug-in electric drive motor vehicle manufacturing facility property which is placed in service during the taxable year.
Inserted: "(2) Applicable percentage.--For purposes of paragraph (1), the applicable percentage is--
Inserted: "(A) 35 percent, in the case of qualified plug-in electric drive motor vehicle manufacturing facility property which is placed in service before January 1, 2013, and
Inserted: "(B) 17.5 percent, in the case of qualified plug-in electric drive motor vehicle manufacturing facility property which is placed in service after December 31, 2012, and before January 1, 2015.
Inserted: "(3) Eligible taxpayer.--For purposes of this subsection, the term 'eligible taxpayer' means any taxpayer--
Inserted: "(A) who places in service qualified plug-in electric drive motor vehicle manufacturing facility property during the taxable year,
Inserted: "(B) who does not make an election under section 179F(c), and
Inserted: "(C) who makes an election under this subsection.
Inserted: "(4) Other definitions and special rules.--
Inserted: "(A) Qualified plug-in electric drive motor vehicle manufacturing facility property.--The term 'qualified plug-in electric drive motor vehicle manufacturing facility property' has the meaning given such term under section 179F(d).
Inserted: "(B) Special rule for dual use property.--In the case of any qualified plug-in electric drive motor vehicle manufacturing facility property which is used to produce both qualified property (as defined in section 179F(d)) and other property which is not qualified property, the amount of costs taken into account under paragraph (1)shall be reduced by an amount equal to--
Inserted: "(i) the total amount of such costs (determined before the application of this subparagraph), multiplied by
Inserted: "(ii) the percentage of property expected to be produced which is not qualified property.
Inserted: "(C) Election.--
Inserted: "(i) In general.--An election under this subsection for any taxable year shall be made on the taxpayer's return of the tax imposed by this chapter for the taxable year. Such election shall be made in such manner as the Secretary may by regulations prescribe.
Inserted: "(ii) Election irrevocable.--Any election made under this subsection may not be revoked except with the consent of the Secretary.
Inserted: "(5) Credit refundable.--For purposes of this title (other than this section), the credit allowed by reason of this subsection shall be treated as if it were allowed under subpart C.".
Inserted: (c) Effective Date.--The amendments made by this section shall apply to taxable years beginning after the date of the enactment of this Act.
Original wording
On page 43, after line 17, insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 5129. Mr. ALEXANDER submitted an amendment intended to be proposed by him to the bill S. 3268, to amend the Commodity Exchange Act, to prevent excessive price speculation with respect to energy commodities, and for other purposes; which was ordered to lie on the table; as follows:
On page 43, after line 17, insert the following:
TITLE II--INCENTIVES FOR PLUG-IN ELECTRIC DRIVE VEHICLES
SEC. 21. CREDIT FOR NEW QUALIFIED PLUG-IN ELECTRIC DRIVE MOTOR VEHICLES.
(a) In General.--Subpart B of part IV of subchapter A of chapter 1 of the Internal Revenue Code of 1986 (relating to other credits) is amended by adding at the end the following new section:
“SEC. 30D. PLUG-IN ELECTRIC DRIVE MOTOR VEHICLE CREDIT.
“(a) Allowance of Credit.--
“(1) In general.--There shall be allowed as a credit against the tax imposed by this chapter for the taxable year an amount equal to the applicable amount with respect to each new qualified plug-in electric drive motor vehicle placed in service by the taxpayer during the taxable year.
“(2) Applicable amount.--For purposes of paragraph (1), the applicable amount is the sum of--
“(A) $2,000, plus
“(B) $400 for each kilowatt hour of traction battery capacity in excess of 2.5 kilowatt hours.
“(b) Limitations.--
“(1) Limitation based on weight.--The amount of the credit allowed under subsection (a) by reason of subsection (a)(2)(A) shall not exceed--
“(A) $7,500, in the case of any new qualified plug-in electric drive motor vehicle with a gross vehicle weight rating of not more than 10,000 pounds,
“(B) $10,000, in the case of any new qualified plug-in electric drive motor vehicle with a gross vehicle weight rating of more than 10,000 pounds but not more than 14,000 pounds,
“(C) $15,000, in the case of any new qualified plug-in electric drive motor vehicle with a gross vehicle weight rating of more than 14,000 pounds but not more than 26,000 pounds, and
“(D) $20,000, in the case of any new qualified plug-in electric drive motor vehicle with a gross vehicle weight rating of more than 26,000 pounds.
“(2) Limitation based on amount of tax.--The credit allowed under subsection (a) for any taxable year shall not exceed the excess of--
“(A) the sum of the regular tax liability (as defined in section 26(b)) plus the tax imposed by section 55, over
“(B) the sum of the credits allowable under subpart A and section 27 for the taxable year.
“(3) Limitation on number of passenger vehicles and light trucks eligible for credit.--No credit shall be allowed under subsection (a) for any new qualified plug-in electric drive motor vehicle which is a passenger vehicle or light truck in any calendar year following the calendar year which includes the first date on which the total number of such new qualified plug-in electric drive motor vehicles sold for use in the United States after December 31, 2007, is at least 250,000.
“(c) New Qualified Plug-in Electric Drive Motor Vehicle.--For purposes of this section, the term ‘new qualified plug-in electric drive motor vehicle' means a motor vehicle--
“(1) which draws propulsion using one or more traction batteries with an aggregate capacity of not less than 2.5 kilowatt hours,
“(2) which uses an offboard source of electricity to recharge one or more such batteries,
“(3) which, where required for the applicable make and model, has received a certificate of conformity under the Clean Air Act, or which meets all Federal safety and emissions requirements for on-road use,
“(4) the original use of which commences with the taxpayer,
“(5) which is acquired for use or lease by the taxpayer and not for resale, and
“(6) which is made by a manufacturer.
“(d) Other Definitions and Special Rules.--For purposes of this section--
“(1) Motor vehicle.--The term ‘motor vehicle' means any vehicle which is manufactured primarily for use on public streets, roads, and highways (not including a vehicle operated exclusively on a rail or rails).
“(2) Other terms.--The terms ‘passenger automobile', ‘light truck', and ‘manufacturer' have the meanings given such terms in regulations prescribed by the Administrator of the Environmental Protection Agency for purposes of the administration of title II of the Clean Air Act (42 U.S.C. 7521 et seq.).
“(3) Traction battery capacity.--Traction battery capacity shall be measured in kilowatt hours from a 100 percent state of charge to a zero percent state of charge.
“(4) Reduction in basis.--For purposes of this subtitle, the basis of any property for which a credit is allowable under subsection (a) shall be reduced by the amount of such credit so allowed.
“(5) No double benefit.--The amount of any deduction or other credit allowable under this chapter for a new qualified plug-in electric drive motor vehicle shall be reduced by the amount of credit allowed under subsection (a) for such vehicle for the taxable year.
“(6) Property used by tax-exempt entity.--In the case of a vehicle the use of which is described in paragraph (3) or (4) of section 50(b) and which is not subject to a lease, the person who sold such vehicle to the person or entity using such vehicle shall be treated as the taxpayer that placed such vehicle in service, but only if such person clearly discloses to such person or entity in a document the amount of any credit allowable under subsection (a) with respect to such vehicle (determined without regard to subsection (b)(2)).
“(7) Property used outside united states, etc., not qualified.--No credit shall be allowable under subsection (a) with respect to any property referred to in section 50(b)(1) or with respect to the portion of the cost of any property taken into account under section 179.
“(8) Recapture.--The Secretary shall, by regulations, provide for recapturing the benefit of any credit allowable under subsection (a) with respect to any property which ceases to be property eligible for such credit (including recapture in the case of a lease period of less than the economic life of a vehicle).
“(9) Election to not take credit.--No credit shall be allowed under subsection (a) for any vehicle if the taxpayer elects not to have this section apply to such vehicle.
“(10) Interaction with air quality and motor vehicle safety standards.--Unless otherwise provided in this section, a motor vehicle shall not be considered eligible for a credit under this section unless such vehicle is in compliance with--
“(A) the applicable provisions of the Clean Air Act for the applicable make and model year of the vehicle (or applicable air quality provisions of State law in the case of a State which has adopted such provision under a waiver under section 209(b) of the Clean Air Act), and
“(B) the motor vehicle safety provisions of sections 30101 through 30169 of title 49, United States Code.
“(e) Regulations.--
“(1) In general.--Except as provided in paragraph (2), the Secretary shall promulgate such regulations as necessary to carry out the provisions of this section.
“(2) Coordination in prescription of certain regulations.--The Secretary of the Treasury, in coordination with the Secretary of Transportation and the Administrator of the Environmental Protection Agency, shall prescribe such regulations as necessary to determine whether a motor vehicle meets the requirements to be eligible for a credit under this section.”.
(b) Coordination With Other Motor Vehicle Credits.--
(1) Electric drive motor vehicles.--Paragraph (1) of section 30(c) of the Internal Revenue Code of 1986 is amended by adding at the end the following new flush sentence:
“Such term shall not include any motor vehicle which is a new qualified plug-in electric drive motor vehicle (as defined by section 30D(c)).”
(2) New qualified fuel cell motor vehicles.--Paragraph (3) of section 30B(b) of such Code is amended by adding at the end the following new flush sentence: “Such term shall not include any motor vehicle which is a new qualified plug-in electric drive motor vehicle (as defined by section 30D(c)).”
(3) New qualified hybrid motor vehicles.--Paragraph (3) of section 30B(d) of such Code is amended by adding at the end the following new flush sentence:
“Such term shall not include any motor vehicle which is a new qualified plug-in electric drive motor vehicle (as defined by section 30D(c)).”
(c) Conforming Amendments.--
(1) Section 1016(a) of the Internal Revenue Code of 1986 is amended by striking “and” at the end of paragraph (36), by striking the period at the end of paragraph (37) and inserting “, and”, and by adding at the end the following new paragraph:
“(38) to the extent provided in section 30D(d)(5).”
(2) Section 6501(m) of such Code is amended by inserting “30D(d)(10)” after “30C(e)(5)”.
(3) The table of sections for subpart B of part IV of such Code is amended by adding at the end the following new item:
“Sec. 30D. Plug-in electric drive motor vehicle credit.”
(d) Conversion Kits.--
(1) In general.--Section 30B of the Internal Revenue Code of 1986 (relating to alternative motor vehicle credit) is amended by redesignating subsections (i) and (j) as subsections (j) and (k), respectively, and by inserting after subsection (h) the following new subsection:
“(i) Plug-in Conversion Credit.--
“(1) In general.--For purposes of subsection (a), the plug-in conversion credit determined under this subsection with respect to any motor vehicle which is converted to a qualified plug-in electric drive motor vehicle is the lesser of--
“(A) an amount equal to--
“(i) $2,000, plus
“(ii) $400 for each kilowatt hour of capacity of the plug-in traction battery module installed in such vehicle in excess of 2.5 kilowatt hours, or
“(B) 50 percent of the cost of the plug-in traction battery module installed in such vehicle as part of such conversion.
“(2) Limitations.--The amount of the credit allowed under this subsection shall not exceed $4,000 with respect to the conversion of any motor vehicle.
“(3) Definitions and special rules.--For purposes of this subsection--
“(A) Qualified plug-in electric drive motor vehicle.--The term ‘qualified plug-in electric drive motor vehicle' means any new qualified plug-in electric drive motor vehicle (as defined in section 30D(c), determined without regard to paragraphs (4) and (6) thereof).
“(B) Plug-in traction battery module.--The term ‘plug-in traction battery module' means an electro-chemical energy storage device which--
“(i) has a traction battery capacity of not less than 2.5 kilowatt hours,
“(ii) is equipped with an electrical plug by means of which it can be energized and recharged when plugged into an external source of electric power,
“(iii) consists of a standardized configuration and is mass produced,
“(iv) has been tested and approved by the National Highway Transportation Safety Administration as compliant with applicable motor vehicle and motor vehicle equipment safety standards when installed by a mechanic with standardized training in protocols established by the battery manufacturer as part of a nationwide distribution program, and
“(v) is certified by a battery manufacturer as meeting the requirements of clauses (i) through (iv).
“(C) Credit allowed to lessor of battery module.--In the case of a plug-in traction battery module which is leased to the taxpayer, the credit allowed under this subsection shall be allowed to the lessor of the plug-in traction battery module.
“(D) Credit allowed in addition to other credits.--The credit allowed under this subsection shall be allowed with respect to a motor vehicle notwithstanding whether a credit has been allowed with respect to such motor vehicle under this section (other than this subsection) in any preceding taxable year.
“(4) Termination.--This subsection shall not apply to conversions made after December 31, 2010.”.
(2) Credit treated as part of alternative motor vehicle credit.--Section 30B(a) of such Code is amended by striking “and” at the end of paragraph (3), by striking the period at the end of paragraph (4) and inserting “, and”, and by adding at the end the following new paragraph:
“(5) the plug-in conversion credit determined under subsection (i).”.
(3) No recapture for vehicles converted to qualified plug-in electric drive motor vehicles.--Paragraph (8) of section 30B(h) of such Code is amended by adding at the end the following: “, except that no benefit shall be recaptured if such property ceases to eligible for such credit by reason of conversion to a qualified plug-in electric drive motor vehicle.”
(e) Effective Date.--The amendments made by this section shall apply to property placed in service after December 31, 2007, in taxable years beginning after such date.
SEC. 22. CLASSIFICATION OF SMART METERS AS 5-YEAR PROPERTY.
(a) In General.--Subparagraph (B) of section 168(e)(3) of the Internal Revenue Code of 1986 (relating to 5-year property) is amended--
(1) by striking “and” at the end of clause (v),
(2) by redesignating clause (vi) as clause (vii), and
(3) by inserting after clause (v) the following new clause:
“(vi) any advanced electricity time-based meter that--
“(I) measures and records electricity usage data on a time differentiated basis,
“(II) has 2-way communications capability,
“(III) provides data that enables the electricity supplier to provide usage information to customers electronically, and
“(IV) is placed in service before January 1, 2014, and”.
(b) Conforming Amendment.--Paragraph (3) of section 168(e) of such Code (relating to classification of certain property) is amended by striking “clause (vi)(I)” in the last sentence and inserting “clause (vii)(I)”.
(c) Effective Date.--The amendments made by this section shall apply to taxable years beginning after December 31, 2007.
SEC. 23. ALTERNATIVE FUEL VEHICLE REFUELING PROPERTY CREDIT.
(a) Increase in Credit Amount.--Section 30C of the Internal Revenue Code of 1986 is amended--
(1) by striking “30 percent” in subsection (a) and inserting “50 percent”, and
(2) by striking “$30,000” in subsection (b)(1) and inserting “$50,000”.
(b) Expansion of Electric Property.--Subsection (c) of section 30C of the Internal Revenue Code of 1986 (relating to qualified alternative fuel vehicle refueling property) is amended--
(1) by striking “and” at the end of paragraph (1),
(2) by redesignating paragraph (2) as paragraph (3),
(3) by striking “Any mixture--” and all that follows in paragraph (3)(B), as so redesignated, and inserting “Any mixture of biodiesel (as defined in section 40A(d)(1)) and diesel fuel (as defined in section 4083(a)(3)), determined without regard to any use of kerosene and containing at least 20 percent biodiesel.”, and
(4) by inserting after paragraph (1) the following new paragraph:
“(2) paragraph (3)(B) of section 179A(d) applied to all electric property used to support the charging of electric vehicles, neighborhood electric vehicles, or plug-in hybrids, without regard to the gross vehicle weight rating of such vehicles, and”.
(c) Extension of Credit.--Section 30C(g) of the Internal Revenue Code of 1986 is amended--
(1) by inserting “electric property and” before “property relating to hydrogen” in paragraph (1), and
(2) by striking “December 31, 2009” in paragraph (2) and inserting “December 31, 2010”.
(d) Effective Date.--The amendments made by this section shall apply to property placed in service after the date of the enactment of this Act, in taxable years ending after such date.
SEC. 24. INCENTIVES FOR MANUFACTURING FACILITIES PRODUCING PLUG-IN ELECTRIC DRIVE MOTOR VEHICLE AND COMPONENTS.
(a) Deduction for Manufacturing Facilities.--Part VI of subchapter B of chapter 1 of the Internal Revenue Code of 1986 (relating to itemized deductions for individuals and corporations) is amended by inserting after section 179E the following new section:
“SEC. 179F. EXPENSING FOR MANUFACTURING FACILITIES PRODUCING PLUG-IN ELECTRIC DRIVE MOTOR VEHICLE AND COMPONENTS.
“(a) Treatment as Expenses.--A taxpayer may elect to treat the applicable percentage of the cost of any qualified plug-in electric drive motor vehicle manufacturing facility property as an expense which is not chargeable to a capital account. Any cost so treated shall be allowed as a deduction for the taxable year in which the qualified manufacturing facility property is placed in service.
“(b) Applicable Percentage.--For purposes of subsection (a), the applicable percentage is--
“(1) 100 percent, in the case of qualified plug-in electric drive motor vehicle manufacturing facility property which is placed in service before January 1, 2013, and
“(2) 50 percent, in the case of qualified plug-in electric drive motor vehicle manufacturing facility property which is placed in service after December 31, 2012, and before January 1, 2015.
“(c) Election.--
“(1) In general.--An election under this section for any taxable year shall be made on the taxpayer's return of the tax imposed by this chapter for the taxable year. Such election shall be made in such manner as the Secretary may by regulations prescribe.
“(2) Election irrevocable.--Any election made under this section may not be revoked except with the consent of the Secretary.
“(d) Qualified Plug-in Electric Drive Motor Vehicle Manufacturing Facility Property.--For purposes of this section--
“(1) In general.--The term ‘qualified plug-in electric drive motor vehicle manufacturing facility property' means any qualified property--
“(A) the original use of which commences with the taxpayer,
“(B) which is placed in service by the taxpayer after the date of the enactment of this section and before January 1, 2015, and
“(C) no written binding contract for the construction of which was in effect on or before the date of the enactment of this section.
“(2) Qualified property.--
“(A) In general.--The term ‘qualified property' means any property which is a facility or a portion of a facility used for the production of--
“(i) any new qualified plug-in electric drive motor vehicle (as defined by section 30D(c)), or
“(ii) any eligible component.
“(B) Eligible component.--The term ‘eligible component' means any battery, any electric motor or generator, or any power control unit which is designed specifically for use in a new qualified plug-in electric drive motor vehicle (as so defined).
“(e) Special Rule for Dual Use Property.--In the case of any qualified plug-in electric drive motor vehicle manufacturing facility property which is used to produce both qualified property and other property which is not qualified property, the amount of costs taken into account under subsection (a) shall be reduced by an amount equal to--
“(1) the total amount of such costs (determined before the application of this subsection), multiplied by
“(2) the percentage of property expected to be produced which is not qualified property.”.
(b) Refund of Credit for Prior Year Minimum Tax Liability.--Section 53 of the Internal Revenue Code of 1986 (relating to credit for prior year minimum tax liability) is amended by adding at the end the following new subsection:
“(f) Election To Treat Amounts Attributable to Qualified Manufacturing Facility.--
“(1) In general.--In the case of an eligible taxpayer, the amount determined under subsection (c) for the taxable year (after the application of subsection (e)) shall be increased by an amount equal to the applicable percentage of any qualified plug-in electric drive motor vehicle manufacturing facility property which is placed in service during the taxable year.
“(2) Applicable percentage.--For purposes of paragraph (1), the applicable percentage is--
“(A) 35 percent, in the case of qualified plug-in electric drive motor vehicle manufacturing facility property which is placed in service before January 1, 2013, and
“(B) 17.5 percent, in the case of qualified plug-in electric drive motor vehicle manufacturing facility property which is placed in service after December 31, 2012, and before January 1, 2015.
“(3) Eligible taxpayer.--For purposes of this subsection, the term ‘eligible taxpayer' means any taxpayer--
“(A) who places in service qualified plug-in electric drive motor vehicle manufacturing facility property during the taxable year,
“(B) who does not make an election under section 179F(c), and
“(C) who makes an election under this subsection.
“(4) Other definitions and special rules.--
“(A) Qualified plug-in electric drive motor vehicle manufacturing facility property.--The term ‘qualified plug-in electric drive motor vehicle manufacturing facility property' has the meaning given such term under section 179F(d).
“(B) Special rule for dual use property.--In the case of any qualified plug-in electric drive motor vehicle manufacturing facility property which is used to produce both qualified property (as defined in section 179F(d)) and other property which is not qualified property, the amount of costs taken into account under paragraph (1)shall be reduced by an amount equal to--
“(i) the total amount of such costs (determined before the application of this subparagraph), multiplied by
“(ii) the percentage of property expected to be produced which is not qualified property.
“(C) Election.--
“(i) In general.--An election under this subsection for any taxable year shall be made on the taxpayer's return of the tax imposed by this chapter for the taxable year. Such election shall be made in such manner as the Secretary may by regulations prescribe.
“(ii) Election irrevocable.--Any election made under this subsection may not be revoked except with the consent of the Secretary.
“(5) Credit refundable.--For purposes of this title (other than this section), the credit allowed by reason of this subsection shall be treated as if it were allowed under subpart C.”.
(c) Effective Date.--The amendments made by this section shall apply to taxable years beginning after the date of the enactment of this Act.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
July 24, 2008