S.Amdt. 5204
What it does: Adds SEC. ___. LIMITATION OF DEDUCTION FOR INCOME ATTRIBUTABLE TO DOMESTIC PRODUCTION OF OIL, GAS, OR PRIMARY PRODUCTS THEREOF at the end of S.Amdt. 5097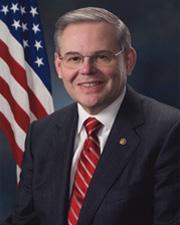 Sen. Robert Menendez (D-NJ)
What it changes
1 change to S.Amdt. 5097
Adds SEC. ___. LIMITATION OF DEDUCTION FOR INCOME ATTRIBUTABLE TO DOMESTIC PRODUCTION OF OIL, GAS, OR PRIMARY PRODUCTS THEREOF at the end of S.Amdt. 5097
Adds a sectionInserted: SEC. ___. LIMITATION OF DEDUCTION FOR INCOME ATTRIBUTABLE TO DOMESTIC PRODUCTION OF OIL, GAS, OR PRIMARY PRODUCTS THEREOF.
Inserted: (a) Denial of Deduction for Major Integrated Oil Companies for Income Attributable to Domestic Production of Oil, Gas, or Primary Products Thereof.--
Inserted: (1) In general.--Subparagraph (B) of section 199(c)(4) of the Internal Revenue Code of 1986 (relating to exceptions) is amended by striking "or" at the end of clause (ii), by striking the period at the end of clause (iii) and inserting ", or", and by inserting after clause (iii) the following new clause:
Inserted: "(iv) in the case of any major integrated oil company (as defined in section 167(h)(5)(B)), the production, refining, processing, transportation, or distribution of oil, gas, or any primary product thereof during any taxable year described in section 167(h)(5)(B).".
Inserted: (2) Primary product.--Section 199(c)(4)(B) of such Code is amended by adding at the end the following flush sentence: "For purposes of clause (iv), the term 'primary product' has the same meaning as when used in section 927(a)(2)(C), as in effect before its repeal.".
Inserted: (b) Limitation on Oil Related Qualified Production Activities Income for Taxpayers Other Than Major Integrated Oil Companies.--
Inserted: (1) In general.--Section 199(d) of the Internal Revenue Code of 1986 is amended by redesignating paragraph (9) as paragraph (10) and by inserting after paragraph (8) the following new paragraph:
Inserted: "(9) Special rule for taxpayers with oil related qualified production activities income.--
Inserted: "(A) In general.--If a taxpayer (other than a major integrated oil company (as defined in section 167(h)(5)(B))) has oil related qualified production activities income for any taxable year beginning after 2009, the amount of the deduction under subsection (a) shall be reduced by 3 percent of the least of--
Inserted: "(i) the oil related qualified production activities income of the taxpayer for the taxable year,
Inserted: "(ii) the qualified production activities income of the taxpayer for the taxable year, or
Inserted: "(iii) taxable income (determined without regard to this section).
Show 3 more inserted paragraphsShow less
Inserted: "(B) Oil related qualified production activities income.--The term 'oil related qualified production activities income' means for any taxable year the qualified production activities income which is attributable to the production, refining, processing, transportation, or distribution of oil, gas, or any primary product thereof during such taxable year.".
Inserted: (2) Conforming amendment.--Section 199(d)(2) of such Code (relating to application to individuals) is amended by striking "subsection (a)(1)(B)" and inserting "subsections (a)(1)(B) and (d)(9)(A)(iii)".
Inserted: (c) Effective Date.--The amendments made by this section shall apply to taxable years beginning after December 31, 2008.
Original wording
At the end add the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 5204. Mr. MENENDEZ submitted an amendment intended to be proposed to amendment SA 5097 submitted by Mr. Coleman and intended to be proposed to the bill S. 3268, to amend the Commodity Exchange Act, to prevent excessive price speculation with respect to energy commodities, and for other purposes; which was ordered to lie on the table; as follows:
At the end add the following:
SEC. ___. LIMITATION OF DEDUCTION FOR INCOME ATTRIBUTABLE TO DOMESTIC PRODUCTION OF OIL, GAS, OR PRIMARY PRODUCTS THEREOF.
(a) Denial of Deduction for Major Integrated Oil Companies for Income Attributable to Domestic Production of Oil, Gas, or Primary Products Thereof.--
(1) In general.--Subparagraph (B) of section 199(c)(4) of the Internal Revenue Code of 1986 (relating to exceptions) is amended by striking “or” at the end of clause (ii), by striking the period at the end of clause (iii) and inserting “, or”, and by inserting after clause (iii) the following new clause:
“(iv) in the case of any major integrated oil company (as defined in section 167(h)(5)(B)), the production, refining, processing, transportation, or distribution of oil, gas, or any primary product thereof during any taxable year described in section 167(h)(5)(B).”.
(2) Primary product.--Section 199(c)(4)(B) of such Code is amended by adding at the end the following flush sentence: “For purposes of clause (iv), the term ‘primary product' has the same meaning as when used in section 927(a)(2)(C), as in effect before its repeal.”.
(b) Limitation on Oil Related Qualified Production Activities Income for Taxpayers Other Than Major Integrated Oil Companies.--
(1) In general.--Section 199(d) of the Internal Revenue Code of 1986 is amended by redesignating paragraph (9) as paragraph (10) and by inserting after paragraph (8) the following new paragraph:
“(9) Special rule for taxpayers with oil related qualified production activities income.--
“(A) In general.--If a taxpayer (other than a major integrated oil company (as defined in section 167(h)(5)(B))) has oil related qualified production activities income for any taxable year beginning after 2009, the amount of the deduction under subsection (a) shall be reduced by 3 percent of the least of--
“(i) the oil related qualified production activities income of the taxpayer for the taxable year,
“(ii) the qualified production activities income of the taxpayer for the taxable year, or
“(iii) taxable income (determined without regard to this section).
“(B) Oil related qualified production activities income.--The term ‘oil related qualified production activities income' means for any taxable year the qualified production activities income which is attributable to the production, refining, processing, transportation, or distribution of oil, gas, or any primary product thereof during such taxable year.”.
(2) Conforming amendment.--Section 199(d)(2) of such Code (relating to application to individuals) is amended by striking “subsection (a)(1)(B)” and inserting “subsections (a)(1)(B) and (d)(9)(A)(iii)”.
(c) Effective Date.--The amendments made by this section shall apply to taxable years beginning after December 31, 2008.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
July 24, 2008