An amendment numbered 5 printed in part C of House Report 111-506 to allow small banks to amortize losses or write-downs on commercial real estate loans over a 10-year period, freeing up more capital for these small institutions to lend to small businesses.
What it does: Adds SEC. 14. TEMPORARY AMORTIZATION AUTHORITY at the end of title I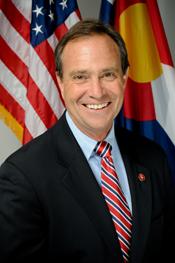 Rep. Ed Perlmutter (D-CO)
Description
Amendment allows small banks to amortize losses or write-downs on commercial real estate loans over a 10-year period, freeing up more capital for these small institutions to lend to small businesses.
What it changes
1 change to H.R. 5297
We couldn't match these changes to the text of H.R. 5297, so they're shown as written.
Adds SEC. 14. TEMPORARY AMORTIZATION AUTHORITY at the end of title I
Adds a sectionInserted: SEC. 14. TEMPORARY AMORTIZATION AUTHORITY.
Inserted: (a) Purpose.--The purpose this section is to address the ongoing effects of the financial crisis on small businesses by providing temporary authority to amortize losses or
Inserted: write-downs in order to increase the availability of credit for small businesses.
Inserted: (b) In General.--For purposes of capital calculation under the Financial Institutions Examination Council's Consolidated Reports of Condition, an eligible institution may choose to amortize any loss or write-down, on a quarterly straight line basis over a period determined under subsection (c), beginning with the month in which such loss or write-down occurs, resulting from the application of FASB Statement 114 or 144 to--
Inserted: (1) other real estate owned (as defined under section 34.81 of title 12, Code of Federal Regulation), or
Inserted: (2) an impared loan secured by real estate, provided that the institution discloses the difference in the amount of the institution's capital, when calculated taking into account the temporary amortization, from the amount of the institution's capital when calculated without taking into account the temporary amortization on the Financial Institutions Examination Council's Consolidated Reports of Condition.
Inserted: (c) Amortization Requirements.--During the initial 2-year period referred to in section 4(d)(4), an eligible institution's amortization period shall be adjusted to reflect the following schedule based on the institution's change in the amount of small business lending relative to the baseline:
Inserted: (1) If the amount of small business lending has increased by less than 2.5 percent, the amortization period shall be 6 years.
Inserted: (2) If the amount of small business lending has increased by 2.5 percent or greater, but by less than 5.0 percent, the amortization period shall be 7 years.
Inserted: (3) If the amount of small business lending has increased by 5.0 percent or greater, but by less than 7.5 percent, the amortization period shall be 8 years.
Inserted: (4) If the amount of small business lending has increased by 7.5 percent or greater, but by less than 10.0 percent, the amortization period shall be 9 years.
Inserted: (5) If the amount of small business lending has increased by 10 percent or greater, the amortization period shall be 10 years.
Show 2 more inserted paragraphsShow less
Inserted: (d) Minimum Underwriting Standards.--The appropriate Federal banking agency for an eligible institution that chooses to amortize any loss or write-down as permitted under subsection (b) shall, within 60 days of the date of the enactment of this title, issue regulations defining minimum underwriting standards that must be used for loans made by the eligible institution.
Inserted: (e) Effective Date.--The provisions of this section shall apply to loan origination that occurred on or after January 1, 2003, and before January 1, 2008.
Original wording
Add at the end of title I the following new section:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
Add at the end of title I the following new section:
SEC. 14. TEMPORARY AMORTIZATION AUTHORITY.
(a) Purpose.--The purpose this section is to address the ongoing effects of the financial crisis on small businesses by providing temporary authority to amortize losses or
write-downs in order to increase the availability of credit for small businesses.
(b) In General.--For purposes of capital calculation under the Financial Institutions Examination Council's Consolidated Reports of Condition, an eligible institution may choose to amortize any loss or write-down, on a quarterly straight line basis over a period determined under subsection (c), beginning with the month in which such loss or write-down occurs, resulting from the application of FASB Statement 114 or 144 to--
(1) other real estate owned (as defined under section 34.81 of title 12, Code of Federal Regulation), or
(2) an impared loan secured by real estate, provided that the institution discloses the difference in the amount of the institution's capital, when calculated taking into account the temporary amortization, from the amount of the institution's capital when calculated without taking into account the temporary amortization on the Financial Institutions Examination Council's Consolidated Reports of Condition.
(c) Amortization Requirements.--During the initial 2-year period referred to in section 4(d)(4), an eligible institution's amortization period shall be adjusted to reflect the following schedule based on the institution's change in the amount of small business lending relative to the baseline:
(1) If the amount of small business lending has increased by less than 2.5 percent, the amortization period shall be 6 years.
(2) If the amount of small business lending has increased by 2.5 percent or greater, but by less than 5.0 percent, the amortization period shall be 7 years.
(3) If the amount of small business lending has increased by 5.0 percent or greater, but by less than 7.5 percent, the amortization period shall be 8 years.
(4) If the amount of small business lending has increased by 7.5 percent or greater, but by less than 10.0 percent, the amortization period shall be 9 years.
(5) If the amount of small business lending has increased by 10 percent or greater, the amortization period shall be 10 years.
(d) Minimum Underwriting Standards.--The appropriate Federal banking agency for an eligible institution that chooses to amortize any loss or write-down as permitted under subsection (b) shall, within 60 days of the date of the enactment of this title, issue regulations defining minimum underwriting standards that must be used for loans made by the eligible institution.
(e) Effective Date.--The provisions of this section shall apply to loan origination that occurred on or after January 1, 2003, and before January 1, 2008.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
House amendment offered
June 16, 2010
View full timeline
House amendment offered
June 16, 2010
House amendment agreed to: On agreeing to the Perlmutter amendment (A004) Agreed to by voice vote.
June 16, 2010 • 11:57 AM
Amendment agreed to Committee of the Whole
June 16, 2010 • 11:57 AM
House amendment offered/reported by : Amendment (A004) offered by Mr. Perlmutter.(consideration: CR H4531-4533; text: CR H4531-4532)
June 16, 2010 • 11:49 AM
Amendment (A004) offered by Mr. Perlmutter. (consideration: CR H4531-4533; text: CR H4531-4532)
June 16, 2010 • 11:49 AM
On agreeing to the Perlmutter amendment (A004) Agreed to by voice vote.
June 16, 2010 • 11:57 AM