An amendment numbered 1 printed in House Report 111-92 to allow issuers to charge consumers for expedited payments by telephone when consumers request such an expedited payment, and would make technical corrections; would require that all credit card offers notify prospective applicants that excessive credit applications can adversely affect their credit rating; would direct the Board of Governors of the Federal Reserve to suggest appropriate guidelines for creditors to supply cardholders with information regarding the availability of legitimate and accredited credit counseling services; would require all written information, provisions, and terms in or on any application, solicitation, contract, or agreement for any credit card account under an open end consumer credit to appear in no less than 12 point font; and would require that stores who are self-issuers of credit cards display a large visible sign at counters with the same information that is required to be disclosed on the application itself.
What it does: 2 changes: inserts text, rewrites a provision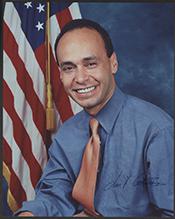 Rep. Luis V. Gutierrez (D-IL)
Description
Amendment allows issuers to charge consumers for expedited payments by telephone when consumers request such an expedited payment; makes technical corrections; requires that all credit card offers notify prospective applicants that excessive credit applications can adversely affect their credit rating; directs the Board of Governors of the Federal Reserve to suggest appropriate guidelines for creditors to supply cardholders with information regarding the availability of legitimate and accredited credit counseling services; requires all written information, provisions, and terms in or on any application, solicitation, contract, or agreement for any credit card account under an open end consumer credit to appear in no less than 12 point font; and requires that stores who are self-issuers of credit cards display a large visible sign at counters with the same information that is required to be disclosed on the application itself.
What it changes
2 changes to H.R. 627
We couldn't match these changes to the text of H.R. 627, so they're shown as written.
Change 1: Inserts new text at the end of section 3
InsertsInserted: (i) Availability of Legitimate and Accredited Credit Counseling.--The Board of Governors of the Federal Reserve System shall suggest appropriate guidelines for creditors to follow with respect to credit card accounts under open end consumer credit plans to supply consumer cardholders with information regarding the availability of legitimate and accredited credit counseling services.
Original wording
At the end of section 3, insert the following new subsection:
Change 2: Rewrites section 8
ReplacesRemoves section 8.
Inserted: SEC. 8. PROHIBIT FEES FOR PAYMENT ON CREDIT CARD ACCOUNTS BY TELEPHONE OR ELECTRONIC FUND TRANSFERS.
Inserted: Section 164 of the Truth in Lending Act (15 U.S.C. 1666c) is amended--
Inserted: (1) by striking "Payments received" and inserting "(a) In General.--Payments received"; and
Inserted: (2) by adding at the end the following new subsection:
Inserted: "(b) Payment Fees.--
Inserted: "(1) Prohibition on fee based on mode of payment.--Except as provided in paragraph (2), in the case of a credit card account under an open end consumer credit plan, a creditor may not impose a fee on the obligor based on the particular manner in which the obligor makes a payment on such account.
Inserted: "(2) Exception.--If the obligor requests to make an expedited payment on a credit card account under an open end consumer credit plan by telephone on the date that a payment is due, or the day immediately preceding such date, the creditor may assess a fee for crediting the payment to the obligor's account on or by such date.".
Inserted: SEC. 9. SOLICITATIONS REQUIRED TO INCLUDE WARNING ON ADVERSE EFFECTS OF EXCESSIVE CREDIT INQUIRIES.
Inserted: Section 127(c)(1)(B) of the Truth in Lending Act (15 U.S.C. 1637(c)(1)(B)) is amended by adding at the end the following new clause:
Inserted: "(iv) Excessive credit inquiries.--A warning that excessive credit inquiries, which occur in connection with credit applications and solicitations and under other circumstances, can have an adverse effect on a consumer credit score.".
Inserted: SEC. 10. READABILITY REQUIREMENT.
Inserted: Section 122 of the Truth in Lending Act (U.S.C. 1632) is amended by adding at the end the following new subsection:
Show 12 more inserted paragraphsShow less
Inserted: "(d) Minimum Type-Size and Font Requirement for Credit Card Applications and Disclosures.--All written information, provisions, and terms in or on any application, solicitation, contract, or agreement for any credit card account under an open end consumer credit plan, and all written information included in or on any disclosure required under this chapter with respect to any such account, shall appear--
Inserted: "(1) in not less than 12-point type; and
Inserted: "(2) in any font other than a font which the Board has designated, in regulations under this section, as a font that inhibits readability.".
Inserted: Insert at the end the following new section:
Inserted: SEC. 13. DISCLOSURE REQUIREMENT FOR STORES ACCEPTING CREDIT CARD ACCOUNT APPLICATIONS.
Inserted: (a) In General.--Section 122 of the Truth in Lending Act (15 U.S.C. 1632) is amended by adding at the end the following:
Inserted: "(d) Signs Required on Certain Premises Where Credit Card Account Applications Accepted.--
Inserted: "(1) In general.--A person who sells personal property to consumers on a business premises and makes available to consumers on such premises any application to open a credit card account under an open end consumer credit plan, and where such person is the issuer of such account, shall display in the premises on a sign any information that is subject to subsection (c) and that is required to be disclosed by the person on that application.
Inserted: "(2) Format.--Such information shall be displayed on the sign in the form and manner which the Board shall prescribe by regulations and which, to the extent practicable and appropriate, shall be consistent with the form and manner required for the disclosure of such information on the credit card application.
Inserted: "(3) Sign placement.--Such signs shall be conspicuously placed at each location on the premises where the credit card application may be submitted by the consumer.".
Inserted: (b) Conforming Amendment.--Section 111(e) of the Truth in Lending Act (15 U.S.C. 1610(e)) is amended by adding at the end the following:
Inserted: "Section 122(d) shall supersede State laws relating to store display of the information that is subject to the requirements of such section, except that any State may employ or establish State laws for the purpose of enforcing the requirements of such section.".
Original wording
Strike section 8 of the bill and insert the following new sections (and redesignate succeeding sections accordingly):
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
At the end of section 3, insert the following new subsection:
(i) Availability of Legitimate and Accredited Credit Counseling.--The Board of Governors of the Federal Reserve System shall suggest appropriate guidelines for creditors to follow with respect to credit card accounts under open end consumer credit plans to supply consumer cardholders with information regarding the availability of legitimate and accredited credit counseling services.
Strike section 8 of the bill and insert the following new sections (and redesignate succeeding sections accordingly):
SEC. 8. PROHIBIT FEES FOR PAYMENT ON CREDIT CARD ACCOUNTS BY TELEPHONE OR ELECTRONIC FUND TRANSFERS.
Section 164 of the Truth in Lending Act (15 U.S.C. 1666c) is amended--
(1) by striking “Payments received” and inserting “(a) In General.--Payments received”; and
(2) by adding at the end the following new subsection:
“(b) Payment Fees.--
“(1) Prohibition on fee based on mode of payment.--Except as provided in paragraph (2), in the case of a credit card account under an open end consumer credit plan, a creditor may not impose a fee on the obligor based on the particular manner in which the obligor makes a payment on such account.
“(2) Exception.--If the obligor requests to make an expedited payment on a credit card account under an open end consumer credit plan by telephone on the date that a payment is due, or the day immediately preceding such date, the creditor may assess a fee for crediting the payment to the obligor's account on or by such date.”.
SEC. 9. SOLICITATIONS REQUIRED TO INCLUDE WARNING ON ADVERSE EFFECTS OF EXCESSIVE CREDIT INQUIRIES.
Section 127(c)(1)(B) of the Truth in Lending Act (15 U.S.C. 1637(c)(1)(B)) is amended by adding at the end the following new clause:
“(iv) Excessive credit inquiries.--A warning that excessive credit inquiries, which occur in connection with credit applications and solicitations and under other circumstances, can have an adverse effect on a consumer credit score.”.
SEC. 10. READABILITY REQUIREMENT.
Section 122 of the Truth in Lending Act (U.S.C. 1632) is amended by adding at the end the following new subsection:
“(d) Minimum Type-Size and Font Requirement for Credit Card Applications and Disclosures.--All written information, provisions, and terms in or on any application, solicitation, contract, or agreement for any credit card account under an open end consumer credit plan, and all written information included in or on any disclosure required under this chapter with respect to any such account, shall appear--
“(1) in not less than 12-point type; and
“(2) in any font other than a font which the Board has designated, in regulations under this section, as a font that inhibits readability.”.
Insert at the end the following new section:
SEC. 13. DISCLOSURE REQUIREMENT FOR STORES ACCEPTING CREDIT CARD ACCOUNT APPLICATIONS.
(a) In General.--Section 122 of the Truth in Lending Act (15 U.S.C. 1632) is amended by adding at the end the following:
“(d) Signs Required on Certain Premises Where Credit Card Account Applications Accepted.--
“(1) In general.--A person who sells personal property to consumers on a business premises and makes available to consumers on such premises any application to open a credit card account under an open end consumer credit plan, and where such person is the issuer of such account, shall display in the premises on a sign any information that is subject to subsection (c) and that is required to be disclosed by the person on that application.
“(2) Format.--Such information shall be displayed on the sign in the form and manner which the Board shall prescribe by regulations and which, to the extent practicable and appropriate, shall be consistent with the form and manner required for the disclosure of such information on the credit card application.
“(3) Sign placement.--Such signs shall be conspicuously placed at each location on the premises where the credit card application may be submitted by the consumer.”.
(b) Conforming Amendment.--Section 111(e) of the Truth in Lending Act (15 U.S.C. 1610(e)) is amended by adding at the end the following:
“Section 122(d) shall supersede State laws relating to store display of the information that is subject to the requirements of such section, except that any State may employ or establish State laws for the purpose of enforcing the requirements of such section.”.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
House amendment offered
April 30, 2009
View full timeline
House amendment offered
April 30, 2009
House amendment agreed to: On agreeing to the Gutierrez amendment (A001) Agreed to by voice vote.
April 30, 2009 • 11:51 AM
Amendment agreed to Committee of the Whole
April 30, 2009 • 11:51 AM
House amendment offered/reported by : Amendment (A001) offered by Mr. Gutierrez.(consideration: CR H5016-5018; text: CR H5016-5017)
April 30, 2009 • 11:40 AM
Amendment (A001) offered by Mr. Gutierrez. (consideration: CR H5016-5018; text: CR H5016-5017)
April 30, 2009 • 11:40 AM
On agreeing to the Gutierrez amendment (A001) Agreed to by voice vote.
April 30, 2009 • 11:51 AM