An amendment numbered 3 printed in House Report 111-92 to set underwriting standards for students' credit cards, including limiting credit lines to the greater of 20 percent of a student's annual income or $500, without a co-signer and requiring creditors to obtain a proof of income, income history, and credit history from college students before approving credit applications.
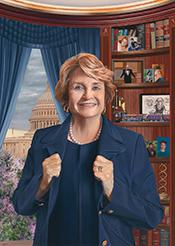 Rep. Louise McIntosh Slaughter (D-NY)
Description
Amendment sets underwriting standards for student credit cards, including limiting credit lines to the greater of 20 percent of a students' annual income or $500 without a co-signer and requiring creditors to obtain a proof of income, income history, and credit history from college students before approving credit applications.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
House amendment offered
April 30, 2009
View full timeline
House amendment offered
April 30, 2009
Amendment agreed to Committee of the Whole
April 30, 2009 • 2:39 PM
Roll call votes on amendments in House
April 30, 2009 • 2:39 PM
House amendment agreed to: On agreeing to the Slaughter amendment (A003) Agreed to by recorded vote: 276 - 154 (Roll no. 225).
April 30, 2009 • 2:39 PM
House amendment offered/reported by : Amendment (A003) offered by Ms. Slaughter.(consideration: CR H5019-5021, H5037-5038; text: CR H5019)
April 30, 2009 • 12:01 PM
Amendment (A003) offered by Ms. Slaughter. (consideration: CR H5019-5021, H5037-5038; text: CR H5019)
April 30, 2009 • 12:01 PM
On agreeing to the Slaughter amendment (A003) Agreed to by recorded vote: 276 - 154 (Roll no. 225).
April 30, 2009 • 2:39 PM
Votes
1 roll call on this amendment
Text
Offered
CREDIT CARDHOLDERS' BILL OF RIGHTS ACT OF 2009
The SPEAKER pro tempore. Pursuant to House Resolution 379 and rule
XVIII, the Chair declares the House in the Committee of the Whole House
on the State of the Union for the further consideration of the bill,
H.R. 627.
{time} 1140
In the Committee of the Whole
Accordingly, the House resolved itself into the Committee of the
Whole House on the State of the Union for the further consideration of
the bill (H.R. 627) to amend the Truth in Lending Act to establish fair
and transparent practices relating to the extension of credit under an
open end consumer credit plan, and for other purposes, with Mrs.
Tauscher (Acting Chair) in the chair.
The Clerk read the title of the bill.
The Acting CHAIR. When the Committee of the Whole House rose on
Wednesday, April 29, 2009, all time for general debate, pursuant to the
order of the House of April 28, 2009, had expired.
Pursuant to House Resolution 379, no further general debate is in
order. The amendment in the nature of a substitute printed in the bill
shall be considered as an original bill for the purpose of amendment
under the 5-minute rule and shall be considered read.
The text of the committee amendment is as follows:
H.R. 627
Be it enacted by the Senate and House of Representatives of
the United States of America in Congress assembled,
SECTION 1. SHORT TITLE.
This Act may be cited as the ``Credit Cardholders' Bill of
Rights Act of 2009''.
SEC. 2. CREDIT CARDS ON TERMS CONSUMERS CAN REPAY.
(a) Retroactive Rate Increases and Universal Default
Limited.--Chapter 2 of the Truth in Lending Act (15 U.S.C.
1631 et seq.) is amended by inserting after section 127A the
following new section:
``Sec. 127B. Additional requirements for credit card accounts
under an open end consumer credit plan
``(a) Retroactive Rate Increases and Universal Default
Limited.--
``(1) In general.--Except as provided in subsection (b), no
creditor may increase any annual percentage rate of interest
applicable to the existing balance on a credit card account
of the consumer under an open end consumer credit plan.
``(2) Existing balance defined.--For purposes of this
subsection and subsections (b) and (c), the term `existing
balance' means the amount owed on a consumer credit card
account as of the end of the 14th day after the creditor
provides notice of an increase in the annual percentage rate
in accordance with subsection (c).
``(3) Treatment of existing balances following rate
increase.--If a creditor increases any annual percentage rate
of interest applicable to the credit card account of a
consumer under an open end consumer credit plan and there is
an existing balance in the account to which such increase may
not apply, the creditor shall allow the consumer to repay the
existing balance using a method provided by the creditor
which is at least as beneficial to the consumer as 1 of the
following methods:
``(A) An amortization period for the existing balance of at
least 5 years starting from the date on which the increased
annual percentage rate went into effect.
``(B) The percentage of the existing balance that was
included in the required minimum periodic payment before the
rate increase cannot be more than doubled.
``(4) Limitation on certain fees.--If--
``(A) a creditor increases any annual percentage rate of
interest applicable on a credit card account of the consumer
under an open end consumer credit plan; and
``(B) the creditor is prohibited by this section from
applying the increased rate to an existing balance,
the creditor may not assess any fee or charge based solely on
the existing balance.''.
(b) Exceptions to the Amendment Made by Subsection (a).--
Section 127B of the Truth in Lending Act is amended by
inserting after subsection (a) (as added by subsection (a))
the following new subsection:
``(b) Exceptions.--
``(1) In general.--A creditor may increase any annual
percentage rate of interest applicable to the existing
balance on a credit card account of the consumer under an
open end consumer credit plan only under the following
circumstances:
``(A) Change in index.--The increase is due solely to the
operation of an index that is not
[[Page H5014]]
under the creditor's control and is available to the general
public.
``(B) Expiration of promotional rate.--The increase is due
solely to the expiration of a promotional rate.
``(C) Failure to comply with workout plan.--The increase is
due solely to the fact the consumer failed to comply with a
negotiated workout plan with the creditor.
``(D) Payment not received during 30-day grace period after
due date.--The increase is due solely to the fact that any
consumer's minimum payment has not been received within 30
days after the due date for such minimum payment.
``(2) Limitation on increases due to failure to comply with
workout plan.--Notwithstanding paragraph (1)(C), the annual
percentage rate in effect with respect to each category of
transactions for a credit card account under an open end
consumer credit plan after the increase permitted under such
subsection due to the failure of a consumer to comply with a
workout plan may not exceed the annual percentage applicable
to such category of transactions on the day before the
effective date of the workout plan.
``(3) Standards required.--The Board shall prescribe, by
regulation, standards--
``(A) for entering into any workout plan applicable to any
credit card account under an open end consumer credit plan;
and
``(B) governing any such workout plan.''.
(c) Advance Notice of Rate Increases and Significant
Contract Changes.--Section 127B of the Truth in Lending Act
is amended by inserting after subsection (b) (as added by
subsection (b)) the following new subsections:
``(c) Advance Notice of Rate Increases.--
``(1) In general.--In the case of any credit card account
under an open end consumer credit plan, no increase in any
annual percentage rate of interest (other than an increase
described in subsection (b)(1)(A)) may take effect unless the
creditor provides a written notice to the consumer at least
45 days before the increase takes effect which fully
describes the changes in the annual percentage rate, in a
complete and conspicuous manner, and the extent to which such
increase would apply to an existing balance.
``(2) Limitation on rate increase notices within first
year.--Except in the case of an increase described in
subparagraph (B), (C), or (D) of subsection (b)(1), no
written notice under paragraph (1) of an increase in any
annual percentage rate of interest on any credit card account
under an open end consumer credit plan (for which notice is
required under such paragraph) shall be effective before the
end of the 1-year period beginning when the account is
opened.
``(d) Advance Notice of Significant Contract Changes.--In
the case of any credit card account under an open end
consumer credit plan, no significant change to the contract
(such as any fee) may take effect unless the creditor
provides a written notice of at least 45 days before the
change takes effect which fully describes the changes in the
contract, in a complete and conspicuous manner.''.
(d) Clerical Amendment.--The table of sections for chapter
2 of the Truth in Lending Act (15 U.S.C. 1631 et seq.) is
amended by inserting after the item relating to section 127A
the following new item:
``127B. Additional requirements for credit card accounts under an open
end consumer credit plan.''.
SEC. 3. ADDITIONAL PROVISIONS REGARDING ACCOUNT FEATURES,
TERMS, AND PRICING.
(a) Double Cycle Billing Prohibited.--Section 127B of the
Truth in Lending Act is amended by inserting after subsection
(d) (as added by section 2(c)) the following new subsection:
``(e) Double Cycle Billing.--
``(1) In general.--No finance charge may be imposed by a
creditor with respect to any balance on a credit card account
under an open end consumer credit plan that is based on
balances for days in billing cycles preceding the most recent
billing cycle as a result of the loss of any grace period.
``(2) Exceptions.--Paragraph (1) shall not apply so as to
prohibit a creditor from--
``(A) adjusting finance charges following the return of a
payment for insufficient funds; or
``(B) adjusting finance charges following resolution of a
billing error dispute.
``(3) Grace period.--For purposes of this subsection, the
term `grace period' means, with respect to any credit card
account under an open end consumer credit plan, the time
period, if any, provided by the creditor within which any
credit extended under such credit plan for purchases of goods
or services may be repaid by the consumer without incurring a
finance charge.''.
(b) Limitations Relating to Account Balances Attributable
Only to Accrued Interest.--Section 127B is amended by
inserting after subsection (e) (as added by subsection (a))
the following new subsection:
``(f) Limitations Relating to Account Balances Attributable
Only to Accrued Interest.--
``(1) In general.--If the outstanding balance on a credit
card account under an open end consumer credit plan at the
end of a billing period represents an amount attributable
only to interest accrued during the preceding billing period
on an outstanding balance that was fully repaid during the
preceding billing period--
``(A) no fee may be imposed or collected in connection with
such balance attributable only to interest before such end of
the billing period; and
``(B) any failure to make timely repayments of the balance
attributable only to interest before such end of the billing
period shall not constitute a default on the account.
Such balance remains a legally binding debt obligation.
``(2) Rule of construction.--Paragraph (1) shall not be
construed as affecting--
``(A) the consumer's obligation to pay any accrued interest
on a credit card account under an open end consumer credit
plan; or
``(B) the accrual of interest on the outstanding balance on
any such account in accordance with the terms of the account
and this title.''.
(c) Access to Payoff Balance Information.--Section 127B of
the Truth in Lending Act is amended by inserting after
subsection (f) (as added by subsection (b)) the following new
subsection:
``(g) Payoff Balance Information.--
``(1) In general.--Each periodic statement provided by a
creditor to a consumer with respect to a credit card account
under an open end consumer credit plan shall contain the
toll-free telephone number, Internet address, and website at
which the consumer may request the payoff balance on the
account.
``(2) Small issuers.--Notwithstanding paragraph (1), in the
case of any credit card issuer which issues fewer than 50,000
credit cards in conjunction with credit card accounts under
open end consumer credit plans, each periodic statement
provided by such a creditor to a consumer with respect to any
such credit card account shall contain the toll-free
telephone number, Internet address, or website at which the
consumer may request the payoff balance on the account.''.
(d) Consumer Right To Reject Card Before Notice Is Provided
of Open Account.--Section 127B of the Truth in Lending Act is
amended by inserting after subsection (g) (as added by
subsection (c)) the following new subsection:
``(h) Consumer Right To Reject Card Before Notice of New
Account Is Provided to Consumer Reporting Agency.--
``(1) In general.--A creditor may not furnish any
information to a consumer reporting agency (as defined in
section 603) concerning the establishment of a newly opened
credit card account under an open end consumer credit plan
until the credit card has been used or activated by the
consumer.
``(2) Rule of construction.--Paragraph (1) shall not be
construed as prohibiting a creditor from furnishing
information about any application for a credit card account
under an open end consumer credit plan or any inquiry about
any such account to a consumer reporting agency (as so
defined).''.
(e) Use of Terms Clarified.--Section 127B of the Truth in
Lending Act is amended by inserting after subsection (h) (as
added by subsection (d)) the following new subsection:
``(i) Use of Terms.--The following requirements shall apply
with respect to the terms of any credit card account under
any open end consumer credit plan:
``(1) `Fixed' rate.--The term `fixed', when appearing in
conjunction with a reference to the annual percentage rate or
interest rate applicable with respect to such account, may
only be used to refer to an annual percentage rate or
interest rate that will not change or vary for any reason
over the period clearly and conspicuously specified in the
terms of the account.
``(2) Prime rate.--The term `prime rate', when appearing in
any agreement or contract for any such account, may only be
used to refer to the bank prime rate published in the Federal
Reserve Statistical Release on selected interest rates (daily
or weekly), and commonly referred to as the H.15 release (or
any successor publication).
``(3) Due date.--
``(A) In general.--Each periodic statement for any such
account shall contain a date by which the next periodic
payment on the account must be made to avoid a late fee or be
considered a late payment, and any payment received by 5
p.m., local time at the location specified by the creditor
for the receipt of payment, on such date shall be treated as
a timely payment for all purposes.
``(B) Certain electronic fund transfers.--Any payment with
respect to any such account made by a consumer online to the
website of the credit card issuer or by telephone directly to
the credit card issuer before 5 p.m., local time at the
location specified by the creditor for the receipt of
payment, on any business day shall be credited to the
consumer's account that business day.
``(C) Presumption of timely payment.--Any evidence provided
by a consumer in the form of a receipt from the United States
Postal Service or other common carrier indicating that a
payment on a credit card account was sent to the issuer not
less than 7 days before the due date contained in the
periodic statement under subparagraph (A) for such payment
shall create a presumption that such payment was made by the
due date, which may be rebutted by the creditor for fraud or
dishonesty on the part of the consumer with respect to the
mailing date.''.
(f) Payment Allocations.--Section 127B of the Truth in
Lending Act is amended by inserting after subsection (i) (as
added by subsection (e)) the following new subsection:
``(j) Payment Allocations.--
``(1) In general.--If 2 or more different annual percentage
rates apply to different portions of an outstanding balance
on a credit card account under an open end consumer credit
plan, the amount of any periodic payment in excess of the
required minimum payment shall be applied using 1 of the
following methods:
``(A) High-to-low method.--The excess amount is allocated
first to the balance with the highest annual percentage rate
and any remaining portion is allocated to any other balance
in descending order, based on the applicable annual
percentage rate each portion of such balance bears, from the
highest such rate to the lowest.
``(B) Pro rata method.--The excess amount is allocated
among each of the portions of such
[[Page H5015]]
balance which bear different rates of interest in the same
proportion as each such portion of the outstanding balance
bears to the total outstanding balance.
``(2) Clarification relating to certain deferred interest
arrangements.--A creditor may allocate the entire amount paid
by the consumer in excess of the required minimum periodic
payment to a balance on which interest is deferred during the
2 billing cycles immediately preceding the expiration of the
period during which interest is deferred.
``(3) Prohibition on restricted grace periods under certain
circumstances.--If, with respect to any credit card account
under an open end consumer credit plan, a creditor offers a
time period in which to repay credit extended without
incurring finance charges to cardholders who pay the balance
in full, the creditor may not deny a consumer who takes
advantage of a promotional rate balance or deferred interest
rate balance offer with respect to such an account any such
time period for repaying credit without incurring finance
charges.''.
(g) Timely Provision of Periodic Statements.--Section 127B
of the Truth in Lending Act is amended by inserting after
subsection (j) (as added by subsection (f)) the following new
subsection:
``(k) Timely Provision of Periodic Statements.--Each
periodic statement with respect to a credit card account
under an open end consumer credit plan shall be sent by the
creditor to the consumer not less than 21 calendar days
before the due date identified in such statement for the next
payment on the outstanding balance on such account, and
section 163(a) shall be applied with respect to any such
account by substituting `21' for `fourteen'.''.
(h) Due Dates.--Section 127B of the Truth in Lending Act is
amended by inserting after subsection (k) (as added by
subsection (g)) the following new subsection:
``(l) Due Dates.--If the date established by a creditor as
the date on which a periodic payment on a credit card account
under an open end consumer credit plan is due is a day on
which mail is either not delivered to such creditor or is not
accepted by the creditor for processing on such day, the
creditor may not treat the receipt by the creditor of any
such periodic payment by mail as of the next business day of
the creditor as late for any purpose.''.
SEC. 4. CONSUMER CHOICE WITH RESPECT TO OVER-THE-LIMIT
TRANSACTIONS.
Section 127B of the Truth in Lending Act is amended by
inserting after subsection (l) (as added by section 3(h)) the
following new subsections:
``(m) Opt-Out of Creditor Authorization of Over-the-Limit
Transactions if Fees Are Imposed.--
``(1) In general.--In the case of any credit card account
under an open end consumer credit plan under which an over-
the-limit-fee may be imposed by the creditor for any
extension of credit in excess of the amount of credit
authorized to be extended under such account, the consumer
may elect to prohibit the creditor, with respect to such
account, from completing any transaction involving the
extension of credit, with respect to such account, in excess
of the amount of credit authorized by notifying the creditor
of such election in accordance with paragraph (2).
``(2) Notification by consumer.--A consumer shall notify a
creditor under paragraph (1)--
``(A) through the notification system maintained by the
creditor under paragraph (4); or
``(B) by submitting to the creditor a signed notice of
election, by mail or electronic communication, on a form
issued by the creditor for purposes of this subparagraph.
``(3) Effectiveness of election.--An election by a consumer
under paragraph (1) shall be effective beginning 3 business
days after the creditor receives notice from the consumer in
accordance with paragraph (2) and shall remain effective
until the consumer revokes the election.
``(4) Notification system.--
``(A) In general.--Each creditor that maintains credit card
accounts under an open end consumer credit plan shall
establish and maintain a notification system, including a
toll-free telephone number, Internet address, and website,
which permits any consumer whose credit card account is
maintained by the creditor to notify the creditor of an
election under this subsection in accordance with paragraph
(2).
``(B) Small issuers.--Notwithstanding subparagraph (A), any
credit card issuer which issues fewer than 50,000 credit
cards in conjunction with credit card accounts under open end
consumer credit plans shall establish and maintain a
notification system, which shall include a toll-free
telephone number, Internet address, or website, which permits
any consumer whose credit card account is maintained by the
creditor to notify the creditor of an election under this
subsection in accordance with paragraph (2).
``(5) Annual notice to consumers of availability of
election.--In the case of any credit card account under an
open end consumer credit plan, the creditor shall include a
notice, in clear and conspicuous language, of the
availability of an election by the consumer under this
paragraph as a means of avoiding over-the limit fees and a
higher amount of indebtedness, and the method for providing
such notice--
``(A) on the periodic statement required under section
127(b) with respect to such account at least once each
calendar year; and
``(B) on any such periodic statement which includes a
notice of the imposition of an over-the-limit fee during the
period covered by the statement.
``(6) No fees if consumer has made an election.--If a
consumer has made an election under paragraph (1), no over-
the-limit fee may be imposed on the account for any reason
that has caused the outstanding balance in the account to
exceed the credit limit.
``(7) Regulations.--
``(A) In general.--The Board shall issue regulations
allowing for the completion of over-the-limit transactions
that for operational reasons exceed the credit limit by a de
minimis amount, even where the cardholder has made an
election under paragraph (1).
``(B) Subject to no fee limitation.--The regulations
prescribed under subparagraph (A) shall not allow for the
imposition of any fee or any rate increase based on the
permitted over-the-limit transactions.
``(n) Over-the-Limit Fee Restrictions.--With respect to a
credit card account under an open end consumer credit plan,
an over-the-limit fee may be imposed only once during a
billing cycle if, on the last day of such billing cycle, the
credit limit on the account is exceeded, and an over-the-
limit fee, with respect to such excess credit, may be imposed
only once in each of the 2 subsequent billing cycles, unless
the consumer has obtained an additional extension of credit
in excess of such credit limit during any such subsequent
cycle or the consumer reduces the outstanding balance below
the credit limit as of the end of such billing cycle.
``(o) Over-the-Limit Fees Prohibited in Conjunction With
Certain Credit Holds.--Notwithstanding subsection (n), an
over-the-limit fee may not be imposed if the credit limit was
exceeded due to a hold unless the actual amount of the
transaction for which the hold was placed would have resulted
in the consumer exceeding the credit limit.''.
SEC. 5. STRENGTHEN CREDIT CARD INFORMATION COLLECTION.
Section 136(b) of the Truth in Lending Act (15 U.S.C.
1646(b)) is amended--
(1) in paragraph (1)--
(A) by striking ``Collection required.--The Board shall''
and inserting ``Collection required.--
``(A) In general.--The Board shall''.
(B) by adding at the end the following new subparagraph:
``(B) Information to be included.--The information under
subparagraph (A) shall include, for the relevant semiannual
period, the following information with respect each creditor
in connection with any consumer credit card account:
``(i) A list of each type of transaction or event during
the semiannual period for which 1 or more creditors has
imposed a separate interest rate upon a consumer credit card
accountholder, including purchases, cash advances, and
balance transfers.
``(ii) For each type of transaction or event identified
under clause (i)--
``(I) each distinct interest rate charged by the card
issuer to a consumer credit card accountholder during the
semiannual period; and
``(II) the number of cardholders to whom each such interest
rate was applied during the last calendar month of the
semiannual period, and the total amount of interest charged
to such accountholders at each such rate during such month.
``(iii) A list of each type of fee that 1 or more of the
creditors has imposed upon a consumer credit card
accountholder during the semiannual period, including any fee
imposed for obtaining a cash advance, making a late payment,
exceeding the credit limit on an account, making a balance
transfer, or exchanging United States dollars for foreign
currency.
``(iv) For each type of fee identified under clause (iii),
the number of accountholders upon whom the fee was imposed
during each calendar month of the semiannual period, and the
total amount of fees imposed upon cardholders during such
month.
``(v) The total number of consumer credit card
accountholders that incurred any finance charge or any other
fee during the semiannual period.
``(vi) The total number of consumer credit card accounts
maintained by each creditor as of the end of the semiannual
period.
``(vii) The total number and value of cash advances made
during the semiannual period under a consumer credit card
account.
``(viii) The total number and value of purchases involving
or constituting consumer credit card transactions during the
semiannual period.
``(ix) The total number and amount of repayments on
outstanding balances on consumer credit card accounts in each
month of the semiannual period.
``(x) The percentage of all consumer credit card
accountholders (with respect to any creditor) who--
``(I) incurred a finance charge in each month of the
semiannual period on any portion of an outstanding balance on
which a finance charge had not previously been incurred; and
``(II) incurred any such finance charge at any time during
the semiannual period.
``(xi) The total number and amount of balances accruing
finance charges during the semiannual period.
``(xii) The total number and amount of the outstanding
balances on consumer credit card accounts as of the end of
such semiannual period.
``(xiii) Total credit limits in effect on consumer credit
card accounts as of the end of such semiannual period and the
amount by which such credit limits exceed the credit limits
in effect as of the beginning of such period.
``(xiv) Any other information related to interest rates,
fees, or other charges that the Board deems of interest.'';
and
(2) by adding at the end the following new paragraph:
``(5) Report to congress.--The Board shall, on an annual
basis, transmit to Congress and make public a report
containing estimates by the Board of the approximate,
relative percentage of
[[Page H5016]]
income derived by the credit card operations of depository
institutions from--
``(A) the imposition of interest rates on cardholders,
including separate estimates for--
``(i) interest with an annual percentage rate of less than
25 percent; and
``(ii) interest with an annual percentage rate equal to or
greater than 25 percent;
``(B) the imposition of fees on cardholders;
``(C) the imposition of fees on merchants; and
``(D) any other material source of income, while specifying
the nature of that income.''.
SEC. 6. STANDARDS APPLICABLE TO INITIAL ISSUANCE OF SUBPRIME
OR ``FEE HARVESTER'' CARDS.
Section 127B of the Truth in Lending Act is amended by
inserting after subsection (o) (as added by section 4) the
following new subsection:
``(p) Standards Applicable to Initial Issuance of Subprime
or `Fee Harvester' Cards.--
``(1) In general.--In the case of any credit card account
under an open end consumer credit plan the terms of which
require the payment of any fee (other than any late fee, any
over-the-limit fee, or any fee for a payment returned for
insufficient funds) by the consumer in the first year the
account is opened in an amount in excess of 25 percent of the
total amount of credit authorized under the account when the
account is opened, no payment of any fee (other than any late
fee, any over-the-limit fee, or any fee for a payment
returned for insufficient funds) may be made from the credit
made available by the card.
``(2) Rule of construction.--No provision of this
subsection may be construed as authorizing any imposition or
payment of advance fees otherwise prohibited by any provision
of law.''.
SEC. 7. EXTENSIONS OF CREDIT TO UNDERAGE CONSUMERS.
Section 127(c) of the Truth in Lending Act (15 U.S.C.
1637(c)) is amended by adding at the end the following new
paragraph:
``(8) Extensions of credit to underage consumers.--
``(A) In general.--No credit card may be knowingly issued
to, or open end credit plan established on behalf of, a
consumer who has not attained the age of 18, unless the
consumer is emancipated under applicable State law.
``(B) Rule of construction.--For the purposes of
determining the age of an applicant, the submission of a
signed application by a consumer stating that the consumer is
over 18 shall be considered sufficient proof of age.''.
SEC. 8. PROHIBIT FEES FOR PAYMENT ON CREDIT CARD ACCOUNTS BY
ELECTRONIC FUND TRANSFERS.
(a) In General.--Section 127 of the Truth in Lending Act
(15 U.S.C. 1637) is amended by adding at the end the
following new subsection:
``(i) Payments by EFT.--In the case of a credit card
account under an open end consumer credit plan, a creditor
may not impose a fee based on the manner in which payment on
the account is made, including a fee for making any such
payment by electronic fund transfer (as defined in section
903).''.
(b) Effective Date.--The amendment made by subsection (a)
shall apply to all payments made after the date of the
enactment of this Act and any fee imposed after such date in
contravention of the amendment shall be promptly credited to
the consumer's account.
SEC. 9. REPORT TO CONGRESS ON REDUCTIONS OF CONSUMER CREDIT
CARD LIMITS BASED ON CERTAIN INFORMATION AS TO
EXPERIENCE OR TRANSACTIONS OF THE CONSUMER.
(a) Report on Creditor Practices Required.--Before the end
of the 6-month period beginning on the date of the enactment
of this Act, the Board of Governors of the Federal Reserve
System, in consultation with the Comptroller of the Currency,
the Director of the Office of Thrift Supervision, the Federal
Deposit Insurance Corporation, the National Credit Union
Administration Board, and the Federal Trade Commission, shall
report to the Committee on Financial Services of the House of
Representatives and the Committee on Banking, Housing, and
Urban Affairs of the Senate on the extent to which, during
the 3-year period ending on such date of enactment, creditors
have reduced credit limits or raised interest rates
applicable to credit card accounts under open end consumer
credit plans based on--
(1) the geographical location where a credit transaction
with the consumer takes place or the identity of the merchant
involved in the transaction;
(2) the consumer's credit transactions, including the type
of credit transaction, the type of items purchased in such
transaction, the price of items purchased in such
transaction, any change in the type or price of items
purchased in such transactions, and other data pertaining to
the consumer's use of such credit card account; and
(3) the identity of the mortgage creditor which extended or
holds the mortgage loan secured by the consumer's primary
residence.
(b) Other Information.--The report required under
subsection (a) shall also include--
(1) the number and identity of creditors that have engaged
in the practices described in subsection (a);
(2) the extent to which the practices described in
subsection (a) have an adverse impact on minority or low-
income consumers;
(3) any other relevant information regarding such
practices; and
(4) recommendations to the Congress on regulatory or
statutory changes that may be needed to restrict or prevent
such practices.
SEC. 10. EFFECTIVE DATE.
(a) In General.--Except as provided in subsection (c) for
the period described in such subsection, the amendments made
by this Act shall apply to all credit card accounts under
open end consumer credit plans after the earlier of--
(1) the end of the 12-month period beginning on the date of
the enactment of this Act; or
(2) June 30, 2010.
(b) Regulations.--Except as provided in subsection (c) for
the period described in such subsection, the Board of
Governors of the Federal Reserve System, in consultation with
the Comptroller of the Currency, the Director of the Office
of Thrift Supervision, the Federal Deposit Insurance
Corporation, the National Credit Union Administration Board,
and the Federal Trade Commission, shall prescribe
regulations, in final form, implementing the amendments made
by this Act before the earlier of--
(1) the end of the 5-month period beginning on the date of
the enactment of this Act; or
(2) June 1, 2010.
(c) Interim Effective Period for Advance Notices of Rate
Increases.--
(1) In general.--During the period beginning 90 days after
the date of the enactment of this Act and ending on the
effective date of all the amendments under this Act as
determined pursuant to subsection (a), no increase in any
annual percentage rate of interest on any credit card account
under an open end consumer credit plan (as such terms are
defined in the Truth in Lending Act) may take effect unless
the creditor provides a written notice to the consumer at
least 45 days before the increase would otherwise take effect
which fully describes the changes in the annual percentage
rate, in a complete and conspicuous manner, and the extent to
which such increase would apply to an existing balance.
(2) Exceptions.--A notice shall not be required under
paragraph (1) for an increase in an annual percentage rate
described in subparagraph (A), (B), or (C) of section
127B(b)(1) (as added by section 2).
(3) Regulations.--The Board of Governors of the Federal
Reserve System shall prescribe regulations implementing the
amendment referred to in paragraph (1), for purposes of this
subsection, before the end of the 60-day period beginning on
the date of the enactment of this Act.
The Acting CHAIR. No amendment to the committee amendment is in order
except those printed in House Report 111-92. Each amendment may be
offered only in the order printed in the report, by a Member designated
in the report, shall be considered read, shall be debatable for the
time specified in the report, equally divided and controlled by the
proponent and an opponent of the amendment, shall not be subject to
amendment, and shall not be subject to a demand for division of the
question.
Amendment No. 1 Offered by Mr. Gutierrez
The Acting CHAIR. It is now in order to consider amendment No. 1
printed in House Report 111-92.
Mr. GUTIERREZ. I have an amendment at the desk made in order under
the rule.
The Acting CHAIR. The Clerk will designate the amendment.
The text of the amendment is as follows:
Amendment No. 1 offered by Mr. Gutierrez:
At the end of section 3, insert the following new
subsection:
(i) Availability of Legitimate and Accredited Credit
Counseling.--The Board of Governors of the Federal Reserve
System shall suggest appropriate guidelines for creditors to
follow with respect to credit card accounts under open end
consumer credit plans to supply consumer cardholders with
information regarding the availability of legitimate and
accredited credit counseling services.
Strike section 8 of the bill and insert the following new
sections (and redesignate succeeding sections accordingly):
SEC. 8. PROHIBIT FEES FOR PAYMENT ON CREDIT CARD ACCOUNTS BY
TELEPHONE OR ELECTRONIC FUND TRANSFERS.
Section 164 of the Truth in Lending Act (15 U.S.C. 1666c)
is amended--
(1) by striking ``Payments received'' and inserting ``(a)
In General.--Payments received''; and
(2) by adding at the end the following new subsection:
``(b) Payment Fees.--
``(1) Prohibition on fee based on mode of payment.--Except
as provided in paragraph (2), in the case of a credit card
account under an open end consumer credit plan, a creditor
may not impose a fee on the obligor based on the particular
manner in which the obligor makes a payment on such account.
``(2) Exception.--If the obligor requests to make an
expedited payment on a credit card account under an open end
consumer credit plan by telephone on the date that a payment
is due, or the day immediately preceding such date, the
creditor may assess a fee for crediting the payment to the
obligor's account on or by such date.''.
SEC. 9. SOLICITATIONS REQUIRED TO INCLUDE WARNING ON ADVERSE
EFFECTS OF EXCESSIVE CREDIT INQUIRIES.
Section 127(c)(1)(B) of the Truth in Lending Act (15 U.S.C.
1637(c)(1)(B)) is amended by adding at the end the following
new clause:
``(iv) Excessive credit inquiries.--A warning that
excessive credit inquiries, which occur in connection with
credit applications and solicitations and under other
circumstances, can have an adverse effect on a consumer
credit score.''.
[[Page H5017]]
SEC. 10. READABILITY REQUIREMENT.
Section 122 of the Truth in Lending Act (U.S.C. 1632) is
amended by adding at the end the following new subsection:
``(d) Minimum Type-Size and Font Requirement for Credit
Card Applications and Disclosures.--All written information,
provisions, and terms in or on any application, solicitation,
contract, or agreement for any credit card account under an
open end consumer credit plan, and all written information
included in or on any disclosure required under this chapter
with respect to any such account, shall appear--
``(1) in not less than 12-point type; and
``(2) in any font other than a font which the Board has
designated, in regulations under this section, as a font that
inhibits readability.''.
Insert at the end the following new section:
SEC. 13. DISCLOSURE REQUIREMENT FOR STORES ACCEPTING CREDIT
CARD ACCOUNT APPLICATIONS.
(a) In General.--Section 122 of the Truth in Lending Act
(15 U.S.C. 1632) is amended by adding at the end the
following:
``(d) Signs Required on Certain Premises Where Credit Card
Account Applications Accepted.--
``(1) In general.--A person who sells personal property to
consumers on a business premises and makes available to
consumers on such premises any application to open a credit
card account under an open end consumer credit plan, and
where such person is the issuer of such account, shall
display in the premises on a sign any information that is
subject to subsection (c) and that is required to be
disclosed by the person on that application.
``(2) Format.--Such information shall be displayed on the
sign in the form and manner which the Board shall prescribe
by regulations and which, to the extent practicable and
appropriate, shall be consistent with the form and manner
required for the disclosure of such information on the credit
card application.
``(3) Sign placement.--Such signs shall be conspicuously
placed at each location on the premises where the credit card
application may be submitted by the consumer.''.
(b) Conforming Amendment.--Section 111(e) of the Truth in
Lending Act (15 U.S.C. 1610(e)) is amended by adding at the
end the following:
``Section 122(d) shall supersede State laws relating to
store display of the information that is subject to the
requirements of such section, except that any State may
employ or establish State laws for the purpose of enforcing
the requirements of such section.''.
The Acting CHAIR. Pursuant to House Resolution 379, the gentleman
from Illinois (Mr. Gutierrez) and a Member opposed each will control 10
minutes.
The Chair recognizes the gentleman from Illinois.
Mr. GUTIERREZ. I yield myself 3\1/2\ minutes.
Madam Chairwoman, this amendment contains several provisions that
both sides have either agreed to or believe are noncontroversial.
First, it amends section 8 of the bill, which prohibits credit card
issuers from charging consumers who choose to pay their bill by phone,
over the Internet, or by other means of electronic funds transfer. It
allows credit card companies to charge consumers for expedited payments
by telephone when consumers request such an expedited payment.
In current practice, many credit card issuers charge their customers
a substantial fee to pay their monthly bill over the phone or online.
These fees, known as pay-to-pay fees, are assessed regardless of
whether a customer's payment is made on time.
Pay-to-pay fees don't exist to recoup the costs incurred through
processing phone or online payments. Processing an electronic payment
certainly does not cost as much as the $15 fee which some credit card
companies assess to their customers.
This bill would end the discrimination against payment methods by
prohibiting the companies from charging a consumer to pay their bill.
This amendment retains that prohibition, but permits an exception to
the ban when the consumer wishes to have the convenience of an
expedited payment. This would include any expedited payments made by
the consumers within 24 hours of when the bill is due.
I want to thank Mr. Ackerman for his efforts in getting the pay-to-
pay prohibition added to the bill and for working with the committee to
find a bipartisan compromise to carve out expedited payments from the
ban.
I also want to thank the gentleman from Delaware (Mr. Castle) for his
work on this compromise.
This amendment contains several other provisions, including a
provision drafted by Mr. Hastings directing the Federal Reserve to
suggest appropriate guidelines for creditors to supply consumers with
information regarding the availability of credit counseling services; a
provision sponsored by Mr. Castle requiring that all credit card offers
notify prospective applicants that excess credit applications can
adversely affect their credit rating; a provision authored by the
gentlelady from New York, Congresswoman Slaughter, to require all
written information and terms in any application, solicitation,
contract or agreement for a credit card account to appear in no less
than 12-point font; and a provision sponsored by Mr. Weiner requiring
stores that are self-issuers of credit cards to display a large visible
sign at counters with the same information that is required to be
disclosed on the credit card information itself.
I urge my colleagues to support this amendment.
{time} 1145
I reserve the balance of my time.
Mr. NEUGEBAUER. Madam Chair, I claim time in opposition, but I am not
opposed to the amendment.
The Acting CHAIR. Without objection, the gentleman from Texas is
recognized for 5 minutes.
There was no objection.
Mr. NEUGEBAUER. I want to thank the gentleman.
We had a tremendous amount of discussion about the pay-to-pay
provision in this bill. One of the things that we don't want to do is
to prevent the cardholders' ability to be able to make payments by
telephone or by other means. However, a number of these companies have
invested a lot of money in the technology to allow consumers to be able
to pay their credit cards in different ways and thereby avoid late
fees.
A concern that many of us had was, if we somehow regulated and denied
the ability completely of credit card companies to be able to charge a
fee for this service, that they would discontinue it. We felt like that
might even cost consumers more money because they would be charged late
fees and interest.
I also appreciate the gentleman in that, I think, all of us believe
that disclosure is an important part of making credit card use a better
tool for consumers, and I'm glad to see that the gentleman also has
some additional disclosure provisions in here as to the size of the
type. So I think this particular amendment makes the overall bill
better, and I thank the gentleman for his amendment.
I reserve the balance of my time.
Mr. GUTIERREZ. Madam Chair, I yield 1\1/2\ minutes to the author and
architect of the bill, the gentlewoman from New York, Carolyn Maloney.
Mrs. MALONEY. I thank the chairman for yielding and for his
leadership.
Madam Chair, I rise in support of this manager's amendment. It makes
a number of commonsense additions to this legislation, such as
requiring all written materials from credit card companies to be in at
least a 12-point font. Gone will be the days of too-small-to-read fine,
fine print disclosures and contracts. It requires the better disclosure
of credit card terms when potential customers are offered credit cards
in retail stores. It warns customers that constant credit applications
can have an adverse effect on one's credit score, and it makes a
clarification that Congressman Ackerman sought and achieved somewhat in
committee with his amendment that was accepted that will ban fees for
paying your credit card bill. No more fees for paying your bills. These
are all very good and important things.
I support this amendment and urge its adoption.
Mr. NEUGEBAUER. Madam Chair, it is my privilege at this time to yield
so much time as he may consume to my good friend from Texas (Mr.
Hensarling).
Mr. HENSARLING. Madam Chairman, the part of this amendment that I,
perhaps, do not support is one more mandate; but on balance, I wanted
to compliment the ranking member, and I wanted to compliment the
gentlelady from New York because the approach of this amendment is to
provide consumers with tools that they can use to better understand the
provisions of their credit card agreements. To me, that's at the crux
of the argument.
What we should do is not take consumer choice away. We shouldn't take
credit opportunities away, particularly
[[Page H5018]]
in a national credit crunch, but we have got to end misleading,
deceptive and confusing disclosures where consumers do not have the
opportunity or the ability to understand the options that are before
them.
So as I look down here, being able to notify customers as to how a
credit application can adversely affect their credit rating, this is a
good thing. Increasing font sizes, in certain instances where needed,
is a good thing. Requiring signage in stores that offer credit cards in
order to help consumers to know their terms, this is a good thing.
I have said before--and I don't know if the gentlelady from New York
was on the floor--that I applaud her for that portion of her bill that
helps empower consumers with greater disclosure. I think that is a huge
step forward.
As she well knows, I think her bill takes several steps backwards. I
think it ends up eroding risk-based pricing. I believe there are some
price controls within the bill. We've had a debate on that, and I
assume we will continue to have a debate.
Overall, this amendment is a very good amendment, and it will help
empower consumers. I am concerned about some of the pay-to-pay fees. I
don't quite understand what's being accomplished there; but otherwise,
it's a good amendment, and I applaud the authors for it.
Mr. GUTIERREZ. I want to thank the gentleman from Texas (Mr.
Hensarling) for his words. It's the second time we'll have a manager's
amendment that we're going to be together on. I look forward to working
with him more.
Mr. NEUGEBAUER. I have no further speakers, and I yield back my time.
Mr. GUTIERREZ. I yield back the balance of my time.
The Acting CHAIR. The question is on the amendment offered by the
gentleman from Illinois (Mr. Gutierrez).
The amendment was agreed to.
Amendment No. 2 Offered by Mr. Frank of Massachusetts
The Acting CHAIR. It is now in order to consider amendment No. 2
printed in House Report 111-92.
Mr. FRANK of Massachusetts. Madam Chair, I rise to offer the
amendment.
The Acting CHAIR. The Clerk will designate the amendment.
The text of the amendment is as follows:
Amendment No. 2 offered by Mr. Frank of Massachusetts:
After section 8, insert the following new section (and
redesignate subsequent sections accordingly):
SEC. 9. BOARD REVIEW OF CONSUMER CREDIT PLANS AND
REGULATIONS.
(a) Required Review.--Not later than 2 years after the
effective date of this Act and every 2 years thereafter,
except as provided in subsection (c)(2), the Board shall
conduct a review, within the limits of its existing resources
available for reporting purposes, of the consumer credit card
market including--
(1) the terms of credit card agreements and the practices
of credit card issuers;
(2) the effectiveness of disclosure of terms, fees, and
other expense of credit card plans;
(3) the adequacy of protections against unfair or deceptive
acts or practices relating to credit card plans, and
(4) whether or not, and to what extent, the Credit
Cardholders' Bill of Rights Act of 2009 has resulted in--
(A) higher annual percentage rates of interest, on average,
for credit card users than the average of such rates of
interest in effect before the effective date of the Act;
(B) the imposition of annual fees or other credit card
fees--
(i) that did not exist before such effective date;
(ii) at a higher average rate of applicability than existed
before such effective date; or
(iii) with higher average costs to the consumer than were
in effect before such effective date;
(C) an increase in the rate of denial of--
(i) new credit card accounts for consumers; or
(ii) new extensions of credit, or additional lines of
credit, for existing credit accounts established before such
effective date; or
(D) any other adverse or negative condition or effect on
consumers.
(b) Solicitation of Public Comment.--In connection with
conducting the review required by subsection (a), the Board
shall solicit comment from consumers, credit card issuers,
and other interested parties, such as through hearings or
written comments.
(c) Regulations.--
(1) Notice.--Following the review required by subsection
(a) the Board shall publish a notice in the Federal Register
that--
(A) summarizes the review, the comments received from the
public solicitation, and other evidence gathered by the Board
such as through consumer testing or other research; and
(B) either--
(i) proposes new or revised regulations or interpretations
to update or revise disclosures and protections for consumer
credit cards as appropriate; or
(ii) states the reason for the Board's determination that
new or revised regulations are not proposed.
(2) Revision of review period following material revision
of regulations.--In the event the Board materially revises
regulations on consumer credit card plans, a review need not
be conducted until 2 years following the effective date of
the revised regulations, which thereafter shall become the
new date for the biennial review required by subsection (a).
(d) Board Report to the Congress.--The Board shall report
to the Congress no less frequently than every 2 years, except
as provided in subsection (c)(2), on the status of its most
recent review, its efforts to address any issues identified
from the review, and any recommendations for legislation.
(e) Additional Reporting.--The Federal banking agencies and
the Federal Trade Commission shall provide annually to the
Board, and the Board shall include in its annual report to
Congress under section 10 of the Federal Reserve Act,
information about the supervisory and enforcement activities
of the agencies with respect to credit card issuers'
compliance with applicable Federal consumer protection
statutes and regulations including--
(1) this Act, the amendments made by this Act, and
regulations prescribed under this Act and such amendments;
and
(2) section 5 of the Federal Trade Commission Act, and
regulations prescribed under the Federal Trade Commission
Act, such as part 227 of title 12 of the Code of Federal
Regulations as prescribed by the Board (Regulation AA).
The Acting CHAIR. Pursuant to House Resolution 379, the gentleman
from Massachusetts (Mr. Frank) and a Member opposed each will control 5
minutes.
The Chair recognizes the gentleman from Massachusetts.
Mr. FRANK of Massachusetts. I yield myself 2 minutes.
Madam Chair, at the committee, the gentleman from Texas (Mr.
Hensarling) offered a proposal for a study. I did not agree with it at
the time because it seemed to me to be talking about the potential
negative. Subsequently, the administration asked us to support a study
which seemed to me to be incomplete because it was only talking about
potential positives.
So what I decided made the most sense was to amalgamate the two and
to offer a study which asked the Federal Reserve to do both sides of
this. I am sometimes skeptical of studies. I will say that I have, from
time to time, thought about an amendment that said that any Member who
moved to create a study should be required to take a public test on the
results of that study once it was completed because we too easily put
in the extra work here; but I do think, in this case, it is a new area
of policy. It is entirely reasonable to have both the potential pluses
and minuses studied, and that is why I offer this amendment.
I reserve the balance of my time.
Mr. NEUGEBAUER. Madam Chair, I rise to claim time in opposition, but
I'm not opposed to the amendment.
The Acting CHAIR. Without objection, the gentleman from Texas is
recognized for 5 minutes.
There was no objection.
Mr. NEUGEBAUER. At this time, I would like to yield such time as he
may consume to my good friend from Texas (Mr. Hensarling).
Mr. HENSARLING. I thank the gentleman for yielding.
Madam Chair, I want to rise in support of the Frank amendment. I
appreciate the distinguished chairman of the Financial Services
Committee working with me on this.
I do believe that it is an important study to have, and again, I
don't know what the results of the study will be. I'll take the
chairman up on his challenge. I'll be prepared to take the pop quiz
once the study comes out.
The only thing that is a little bit disappointing to me, if I recall
right, is I offered a second-degree amendment to the Waters amendment
in markup, which I believe was a 6-month study after implementation.
This is a 2-year. I wish we didn't have to wait quite that long for the
results.
Madam Chairman, one of the big debates that we're having within this
body today is ultimately what will the impact be of this legislation.
There are those on the other side of the aisle who have maintained that
this will have no
[[Page H5019]]
adverse impact on credit availability or that there will be no bailout
effect with those who have good credit ratings and good practices who
ultimately end up bailing out others. Now, some on the other side
admitted they just believe there are more benefits to be derived from
the legislation than the cost. I do not feel that way.
Number one, the Congressional Research Service, in response to a
question regarding this legislation, said: ``Credit card issuers could
respond in a variety of ways. They may increase loan rates across the
board on all borrowers, making it more expensive for both good and
delinquent borrowers to use revolving credit. Issuers may also increase
minimum monthly payments, reduce credit limits or reduce the number of
credit cards issued to people with impaired credit.''
That was the opinion of the Congressional Research Service. Again, it
may prove to be true. It may not prove to be true. I believe it will
prove to be true, and I believe that the Federal Reserve study could at
least be helpful in determining this.
I've heard from community bankers within my district. They believe,
if this legislation is passed, that ultimately smaller banks will be
driven out of the market and that only the larger banks will be left
offering these cards. If so, that, again, is fewer choices for
consumers and reduced credit options.
We've heard from academics on the subject, like Professor Todd
Zywicki of George Mason University, who said, ``The increased use of
credit cards has been a substitution from other types of consumer
credit. If individuals are unable to get access to credit cards,
experience and empirical evidence indicates they will turn elsewhere
for credit--such as to pawn shops, payday lenders, rent-to-own or even
loan sharks.''
Again, I think that, given the expertise of the Federal Reserve--and
certainly, I don't agree with everything they come out with, but they
are a relevant party. They do have expertise, and I think it is an
important portion of the chairman's amendment that they study the
phenomena. We know about the experience of the U.K. When a couple of
years ago they passed legislation, they ordered that the credit card
default fees had to be cut or legal action would be taken. What
happened is that two of the three biggest issuers imposed annual fees
on their cardholders. Nineteen of the largest raised interest rates.
Sixty percent fewer applicants were being able to receive credit.
So we have, number one, historical experience. We have academic
testimony. We have testimony from the Congressional Research Service.
So I hope there is an acknowledgment that there is at least a chance
that those of us who argue the adverse consequences of the legislation
may be proven right. I don't think the Federal Reserve are the only
people who should study this phenomenon. I'm happy to invite a GAO
study and other independent studies.
Again, I think it's a very important point, and although I think the
gentlelady from New York's legislation takes a huge step forward with
respect to disclosure, with respect to fighting misleading and really
deceptive practices, I also fear that those who need credit the most in
a credit crunch will be denied those opportunities. I fear that those
who pay their bills on time or at least pay the minimum on time, which
is over half of America, will end up having to bail out the other half,
and we will have more bailout legislation.
So I appreciate the chairman in working with me and at least studying
the phenomenon to see if it has any validity. I'm sorry we have to wait
2 years, but it's certainly better than nothing. Again, I appreciate
the chairman of the full committee working with me on this.
{time} 1200
Mr. FRANK of Massachusetts. I reserve the balance of my time.
Mr. NEUGEBAUER. Madam Chairman, I just want to reiterate what my
friend from Texas said is that we do need to make sure we understand
the intended and unintended consequences of this legislation and how
it's going to impact consumers who use credit cards.
Like the gentleman from Texas, I'm disappointed that we're going to
wait for 2 years to get those results, but I do think it's important
that the agencies involved here make sure that if we have gone down a
road that has a negative impact on the people that use our credit cards
and depend on them, we need to know about that.
With that, I yield back.
Mr. FRANK of Massachusetts. Madam Chair, I am very pleased to be able
to say today that the gentlewoman from New York, the author of the
bill, and the gentleman from Illinois, the chairman of the
subcommittee, are doing an excellent job.
I yield back the balance of my time.
The Acting CHAIR. The question is on the amendment offered by the
gentleman from Massachusetts (Mr. Frank).
The amendment was agreed to.
Amendment No. 3 Offered by Ms. Slaughter
The Acting CHAIR (Mr. Pastor of Arizona). It is now in order to
consider amendment No. 3 printed in House Report 111-92.
Ms. SLAUGHTER. Mr. Chairman, I offer an amendment.
The Acting CHAIR. The Clerk will designate the amendment.
The text of the amendment is as follows:
Amendment No. 3 offered by Ms. Slaughter:
In that portion of section 7 that precedes the amendment
adding a new paragraph (8), strike ``paragraph'' and insert
``paragraphs''.
At the end of the paragraph (8) added by the amendment made
by section 7, strike the closing quotation marks and the 2nd
period.
After paragraph (8) of section 127(c) of the Truth in
Lending Act (as added by the amendment made by section 7),
insert the following new paragraph:
``(9) Provisions applicable with regard to the issuance of
credit cards to full-time, traditional-aged college
students.--
``(A) Definitions.--For purposes of this paragraph, the
following definitions shall apply:
``(i) College student credit card account defined.--The
term `college student credit card account' means a credit
card account under an open end consumer credit plan
established or maintained for or on behalf of any college
student.
``(ii) College student.--The term `college student' means
an individual--
``(I) who is a full-time student attending an institution
of higher education; and
``(II) who has attained the age of 18 and has not yet
attained the age of 21.
``(iii) Institution of higher education.--The term
`institution of higher education' has the same meaning as in
section 101(a) of the Higher Education Act of 1965 (20 U.S.C.
1001(a)).
``(B) Maximum amount limitation as a percentage of gross
income.--Unless a parent, legal guardian, or spouse of a
college student assumes joint liability for debts incurred by
the student in connection with a college student credit card
account--
``(i) the amount of credit which may be extended by any one
creditor to the full-time college student may not exceed,
during any full calendar year, the greater of--
``(I) 20 percent of the annual gross income of the student;
or
``(II) $500; and
``(ii) no creditor shall grant a student a credit card
account, if the credit limit for that credit card account,
combined with the credit limits of any other credit card
accounts held by the student, would exceed 30 percent of the
annual gross income of the student in the most recently
completed calendar year.
``(C) Parental approval required to increase credit lines
for accounts for which parent is jointly liable.--No increase
may be made in the amount of credit authorized to be extended
under a college student credit card account for which a
parent, legal guardian, or spouse of the consumer has assumed
joint liability for debts incurred by the consumer in
connection with the account, before the consumer attains the
age of 21, with respect to such consumer, unless the parent,
guardian, or spouse of the consumer, as applicable, approves
in writing, and assumes joint liability for, such increase.
``(D) Income verification.--For purposes of this paragraph,
a creditor shall require adequate proof of income, income
history, and credit history, subject to the rules of the
Board, before any college student credit card account may be
opened by or on behalf of a student.
``(E) Prohibition on more than 1 credit card account for
any college student.--No creditor may open a credit card
account for, or issue any credit card to, any college student
who--
``(i) has no verifiable annual gross income; and
``(ii) already maintains a credit card account under an
open end consumer credit plan with that creditor, or any
affiliate thereof.
``(F) Exemption authority.--The Board may, by rule, provide
for exemptions to the provisions of this paragraph, as deemed
necessary or appropriate by the Board, consistent with the
purposes of this paragraph.''.
The Acting CHAIR. Pursuant to House Resolution 379, the gentlewoman
[[Page H5020]]
from New York (Ms. Slaughter) and a Member opposed each will control 5
minutes.
The Chair recognizes the gentlewoman from New York.
Ms. SLAUGHTER. Mr. Chairman, I rise in strong support of my amendment
to protect college students from the hardship of excessive credit card
debt and bankruptcy, and I am pleased to share my time with Congressman
Duncan of Tennessee, with whom I have labored for at least 10 years to
try to see this day come. And I appreciate him for his constant help
and support.
According to Sallie Mae, the average undergraduate has $2,200 in
credit card debt, and that figure jumps to $5,800 for graduate
students. And according to Sallie Mae, 84 percent of undergraduates
have at least one credit card, up from 76 percent in 2004. On average,
students have 4.6 credit cards, and half of college students have more
than four, which would be fine if the students were able to pay off the
credit card debt.
Only 17 percent have said that they regularly pay that debt. Most of
them have parents or simply let it go. A 2005 study--which is very
important for us to know--indicated that many university administrators
believe that credit card debt leads to a higher drop-out rate than
their academic failure. Now, I don't think any of us ever expected that
in our lifetime, that more students would drop out of college because
of credit card debt than because of their academics. Indeed, the
Indiana University administrator was quoted in the Chicago Tribune
warning incoming freshmen that the school ``loses more students to
credit card debt than to academic failure.''
And we all know the ramifications of what happens when they become
delinquent on their credit card debt. They can ruin their credit scores
and end up paying higher rates on all future loans, and even more
seriously they may be forced to declare bankruptcy and may not have
enough credit rating to have credit cards again.
Over the past 10 years the number of young people filing for
bankruptcy has increased. If credit card companies applied the same
scrutiny to college students as they do to adults when approving them
for credit cards, college students would not be able to maintain the
balances which they are incapable of paying.
This is not merely smart business practice, it's good public policy,
and our amendment will do just that by requiring the credit card
companies to take responsibility for their lending practices to reduce
the number of young people carrying excessive debt and filing for
bankruptcy. We would ensure that credit card companies cannot provide
students with extravagant limits and require the creditors to obtain a
proof of income, income history and credit history from the students
before approving the application.
It would also encourage financial responsibility from students by
limiting those without income to one credit card and set a limit by
allowing increases over time if prompt payments have been made.
Credit cards can be a useful tool to help students; however, it can
also be a card to failure.
I urge my colleagues to support this amendment.
I reserve the balance of my time.
Mr. NEUGEBAUER. Mr. Chairman, I rise to claim time in opposition.
The Acting CHAIR. The gentleman from Texas is recognized for 5
minutes.
Mr. NEUGEBAUER. Mr. Chairman, at this time, I am pleased to yield 2
minutes to the distinguished ranking member, the gentleman from Alabama
(Mr. Bachus).
Mr. BACHUS. Mr. Chairman, there is nothing more controversial than
students with credit cards and young people with credit cards. I think
we all, as Members of Congress, have heard complaints from our
constituents, and this is a response to some of that unease or anger.
But what we're doing here is two things. There are two provisions of
this bill that I am opposed to. One is that you cannot have a credit
card or someone under the age of 18 cannot have a credit card unless
they have been emancipated by the State of residence, which means
you're eliminating anyone under the age of 18. That includes a lot of
students. And there are those who are saying no credit card under any
circumstances unless you have been emancipated, which I disagree with.
Secondly, here you're saying to a group of students, 77 percent,
according to GAO, use their credit cards for most of their personal
expenses, a lot of their lodging, a lot of their books, a lot of their
fees, and make large purchases from time to time.
You're saying you can only have a credit card in two cases: $500--
which is not going to be sufficient for many of them--or 20 percent of
your income. Some of them are students. They have no income.
Now, you say to get around this, their parents can cosign and, number
two, you do a complete credit history, which is pretty intrusive.
You're really making decisions for every family and every student. Do
you want to do that? What if their parents won't sign? But what if they
need a credit card to go to school and they need to charge over $500?
You're really beginning to micromanage. And sometimes it will prevent
some injustices, sometimes it will prevent some financial difficulties,
like Ms. Slaughter said, but oftentimes, it will result in students not
having the use of a credit card.
Ms. SLAUGHTER. Mr. Speaker, I would like to yield the remainder of my
time to Mr. Duncan.
The Acting CHAIR. The gentleman from Tennessee is recognized for 1\1/
2\ minutes.
Mr. DUNCAN. Mr. Chairman, I will be very brief.
First, I want to commend my colleague, the gentlelady from New York,
for her hard work on this over many years, as she has mentioned.
The college student loan program has resulted in many thousands and
thousands of college graduates, graduated from college or even before
graduation incurring huge, huge debts. And when you add credit card
debts on top of that, now the average graduating college student has a
combined credit card and student loan debt of $20,402. Many, many
thousands have much, much more than that.
And I think this amendment, some of what my friend, the gentleman
from Alabama, has discussed, doesn't really pertain to the specific
amendment that Ms. Slaughter and I have done.
This amendment applies only to full-time, traditional-age college
students, defined as a full-time student and in an institution of
higher education who has not reached the age of 21. So this amendment
does not apply to anyone over the age of 21.
I think it's a very reasonable amendment and a very minimal
limitation or restriction on credit cards. Some universities, many
universities across this country have entered into deals with credit
card companies, and now they are not only encouraging students to incur
huge student loan debts, they're encouraging students to incur credit
card debts.
And I just think this amendment will send a message to parents and
college students that they at least need to think about. We passed a
resolution a couple of days ago encouraging a financial literacy
program recognizing the fact that many people don't have the financial
literacy they need.
Mr. NEUGEBAUER. Mr. Chairman, I am pleased to yield 1\1/2\ minutes to
the gentleman from Texas (Mr. Hensarling).
Mr. HENSARLING. Mr. Chairman, I certainly appreciate the intent
behind the legislation, but I am fearful of what its adverse impact
could be.
Like many people across this Nation, probably many people in this
institution, I worked my way through undergraduate school. I worked a
couple of different jobs in Texas A&M University back in the mid-
seventies to get through college. To get to those jobs, I somehow had
to keep an old 1965 Mustang running, and it didn't want to run.
For some reason, a credit card company sent me a solicitation, and I
got a credit card. And whether I had a transmission problem that I
couldn't pay for, I had a water pump go out, that credit card tided me
over, made sure I had transportation to get to my job to pay for my
undergraduate studies. And I hate to think about all of the college
students in America who may be denied that opportunity. I used it the
way it was supposed to be used. I used it for emergency purposes. I
used it to tide me over until that next paycheck came in.
[[Page H5021]]
We're talking about folks over 18 who can vote, who can go to war, in
most States can marry, own real property. We shouldn't be paternalistic
towards them. We shouldn't deny them what could be an incredibly
valuable tool to get them through college in the first place.
So I urge the rejection of this amendment.
Mr. NEUGEBAUER. Mr. Chairman, I yield myself the balance of my time.
I think one of the concerns I have is this is a road we seem to be
going down every day in these first hundred days, and that is the
Federal Government telling people what they can and cannot do. I was
shocked this week when the EPA administrator Lisa Jackson told public
radio that it was time for America to have a single roadmap and for the
government to tell Americans what kind of cars they ought to be
driving. Now we have an amendment here that's going to tell college
students whether they can have a credit card or not.
This is not the America that our Founding Fathers founded. They
founded this Nation on empowerment and they founded it on the basis of
freedom of choice, and now we're taking choices away. And like the
gentleman from Texas just said, my wife and I put ourselves through
college. We felt like we were fairly responsible. We weren't getting
student loans, we were working. From time to time we needed a little
extra help, and we were able to use our gasoline credit card or our
credit card for unforeseen expenses. Now we're telling people 18-21 the
government doesn't think you ought to have a credit card or you're not
responsible enough to have a credit card.
So now we have an amendment that says, By the way, we're not going to
teach you how to use your credit appropriately. We're just going to
take your credit away.
Anybody that knows what challenges that young people in college are
facing today would know that this is not a good thing for these young
people. Many of them are working their way through school and they use
this credit card as a valuable tool. Ranking Member Bachus said 77
percent of students and universities are using these cards. Not all of
them are using them irresponsibly.
So now for those people that feel like that somehow there's predatory
activities going on, we're going to take that right away.
The Acting CHAIR. The question is on the amendment offered by the
gentlewoman from New York (Ms. Slaughter).
The question was taken; and the Acting Chair announced that the ayes
appeared to have it.
Mr. NEUGEBAUER. Mr. Chairman, I demand a recorded vote.
The Acting CHAIR. Pursuant to clause 6 of rule XVIII, further
proceedings on the amendment offered by the gentlewoman from New York
will be postponed.
Amendment No. 4 Offered by Mr. Gutierrez
The Acting CHAIR. It is now in order to consider amendment No. 4
printed in House Report 111-92.
Mr. GUTIERREZ. I have an amendment at the desk.
The Acting CHAIR. The Clerk will designate the amendment.
The text of the amendment is as follows:
Amendment No. 4 offered by Mr. Gutierrez:
In paragraph (1) of subsection (j) of section 127B of the
Truth in Lending Act (as added by section 3(f) of the bill)
strike ``minimum payment shall be applied'', where such term
appears in the matter preceding subparagraph (A), and all
that follows through the end of subparagraph (B) of such
paragraph and insert ``minimum payment shall be allocated
first to the balance with the highest annual percentage rate
and any remaining portion is allocated to any other balance
in descending order, based on the applicable annual
percentage rate each portion of such balance bears, from the
highest such rate to the lowest''.
{time} 1215
The Acting CHAIR. Pursuant to House Resolution 379, the gentleman
from Illinois (Mr. Gutierrez) and a Member opposed each will control 5
minutes.
The Chair recognizes the gentleman from Illinois.
Mr. GUTIERREZ. Mr. Chairman, I yield myself 3 minutes.
Mr. Chairman, this amendment, which includes language that was
requested by the White House, addresses how credit card companies
allocate payments when a consumer is carrying balances on their credit
cards at several different interest rates.
Under existing law, when different portions of a consumer's credit
card balance have different interest rates, the credit card insurer may
allocate payments in excess of the minimum payment in any manner they
choose. Many insurers allocate these excess payments to the portion of
the balance with the lowest interest rate, ensuring that the highest
interest portions remain on the debtor's account longer.
H.R. 627, as reported, requires payments in excess of the minimum
payment to be allocated either, one, to the portion with the highest
interest rate first and then other portions based on descending order
of APR, or, two, on a pro rata basis. The Gutierrez-Peters-Edwards
amendment would eliminate the pro rata option in H.R. 627 and require
credit card insurers to allocate payments in excess of the minimum
payment to the portion of the consumer's remaining balance with the
highest interest rate first, and then by any remaining balances in
descending order. This amendment would prevent the credit card insurers
from abusing the introductory rates they offer by allocating payments
to the lowest rate balance first, while the industry makes their
profits from keeping the highest interest rates balance on the
consumer's account, which is common practice today.
Our consumers need every tool we can give them to pay down their
existing credit card debt and avoid getting caught in the cycle of
debt. This amendment would dramatically shift the balance of power from
credit card companies to our consumers.
I thank the two wonderful freshmen Members who cosponsored this
amendment, Mr. Peters from Michigan and Ms. Edwards from Maryland. I
strongly urge my colleagues to support this amendment.
Mr. Chairman, I reserve the balance of my time.
Mr. NEUGEBAUER. Mr. Chairman, I rise to claim time in opposition to
the amendment.
The Acting CHAIR. The gentleman from Texas is recognized for 5
minutes.
Mr. NEUGEBAUER. Mr. Chairman, the bill itself I think reached a
compromise on this issue as well as the Federal regulations that came
out about this, and basically it allows it to prorate that. So if there
were an introductory period where the interest rate was lower and then
later on that introductory period passed, it was fair to prorate the
payments between the two rates, the old rate and the new rate. This one
now allows the payment to be applied to the introductory rate. And
thereby, I think what it is going to do--and again, we talk about
choice. It is going to continue to restrict the kinds of cards and
choices that the American people are going to be able to use and look
at and be given from the various credit card companies. And so I am
opposed to this.
At this time, I yield 2 minutes to the gentleman from Texas (Mr.
Hensarling).
Mr. HENSARLING. I thank the gentleman for yielding.
I fear that what we have here is another form of price controls being
applied to credit card availability.
You know, what is going to happen here, as we attempt to protect the
consumer, I think we are about to protect him right out of having any
opportunity to have an introductory rate. I mean, what is going to end
up happening here is, instead of, say, enjoying a 10 percent rate for 3
months and then a 15 percent rate kicks in for the next 9 months, you
are going to end up with 15 percent for the whole year.
Again, the answer here is to allow the consumer to have choice.
People can understand this if we will write the disclosure in the right
way. Yes, there are deceptive practices, but don't hurt the consumer as
you clean up deceptive practices, but let the consumer choose. Let the
consumer choose. And particularly for those who pay their bill on time
at the end of each month, they are going to be hurt every time you take
away just a little bit and chip away at the ability for people to have
their risk priced because those who are good risk are going to end up
subsidizing those who aren't.
I fear, again, that this will be an amendment that has untold,
unintended consequences that are going to
[[Page H5022]]
ultimately hurt the consumer. I mean, there are a lot of different
things that I would love for Congress to do. You know, I don't like to
pay extra for the cheese on a cheeseburger; maybe we can somehow pass a
law that they can't charge me extra for that. But you know what's going
to happen? Either, one, they are going to quit offering me the
cheeseburger, or number two, everybody who doesn't offer it is going to
have to pay more. If you poke in on one end of the balloon, it pokes
out somewhere else.
I know the intention is good, but we are going to protect consumers
out of having any opportunity to have introductory rates if they wish
them. So we need to reject this amendment.
Mr. GUTIERREZ. Mr. Chairman, I would inquire as to the time remaining
on our side.
The Acting CHAIR. The gentleman has 3 minutes remaining.
Mr. GUTIERREZ. Mr. Chairman, I yield 2 minutes to the wonderful
gentlewoman and cosponsor from Maryland (Ms. Edwards).
Ms. EDWARDS of Maryland. Mr. Chairman, I rise today in support of the
Gutierrez-Peters-Edwards amendment. I am a proud sponsor of the
amendment. And thank you to Chairman Gutierrez for his leadership on
this issue, and also to Representatives Frank and Maloney for their
stellar work on behalf of consumers and protecting consumers.
This amendment is such common sense that it almost seems unnecessary
to explain, and it is supported by the White House. It would simply
require credit card issuers to allocate payments in excess of the
minimum payment to the portion of the remaining balance with the
highest outstanding annual percentage rate.
Today, most credit card companies put the high-interest charges at
the bottom of your balance. So even if you are making a payment every
month, none of that payment will go to the highest interest debt until
your payment covers the entire balance of the low-interest debt as
well. This is costing consumers thousands of dollars that could be put
back into the economy.
The current system makes it difficult, if not impossible, for people
to pay off their debt, and it is really designed to make consumers
prisoners of the credit card company, forever indebted to them because
you could never pay off the highest interest debt. The practice has to
be changed, and this is the vehicle to change it.
Mr. Chairman, the underlying bill and this amendment are about doing
the right thing for American consumers and potentially saving them
thousands of dollars that can be put straight back into our economy. I
urge my colleagues to support this amendment and the underlying bill.
Mr. NEUGEBAUER. Mr. Chairman, I yield back the balance of my time.
Mr. GUTIERREZ. Mr. Chairman, I yield myself the remaining time.
The Acting CHAIR. The gentleman from Illinois is recognized for 1\1/
2\ minutes.
Mr. GUTIERREZ. First of all, this is really a simple, commonsense
practice for consumers. It says, you had an interest rate of 10 percent
on the first $100 you took, and then the credit card company raises it
to 20 percent when you take another $100. And the minimum payment is
$30 on that $200, but you make a payment of $50. What happens with that
extra $20 over the minimum payment? It goes to reduce the debt on the
highest interest rate first. So, therefore, the consumer is protected
from the hike.
I just want to say that this amendment comes after conversations with
the President and the White House and the credit card industry. It was
sent over here to the House. I am proud to join the gentlelady from
Maryland in proposing this commonsense amendment to protect consumers.
Just think, you have a chance to put consumers first by allowing them
to pay down the debt at the highest interest rate after the credit card
company changed the rate on you. That is all this really does. It is
very consumer-oriented, and that is what I think we should be all about
here today.
Mr. PETERS. Mr. Chair, I rise today in support of this Amendment and
the underlying bill, which provides important protections for consumers
against unfair credit card billing practices. This amendment, which I
am proud to be cosponsoring, simply states that when a credit card
holder makes a payment it has to be allocated to the balance with the
highest interest rate first.
Like many of my colleagues, I meet regularly with constituents who
are struggling. In Michigan, unemployment is rising, home prices are
falling, and many families are struggling with increased debts and
financial insecurity. While I am new to the Congress, I am not new to
the business of advising families on what's in their financial best
interest. For twenty-two years I was a financial adviser, and my advice
to anyone attempting to pay off outstanding debt was clear: pay off the
highest interest accounts first. But current credit card billing
practices don't always make that possible.
This straight forward, common sense amendment protects consumers by
requiring any payment beyond the minimum payment to be applied to the
highest interest balance, thus ensuring that families that are working
hard to pay their bills and get out from under their credit card debt
are not stuck in a hole paying off low interest debt while the compound
interest on their higher interest debt keeps piling up.
Mr. Chair, this amendment and this bill provide important protections
for America's families during this time of economic uncertainty. I urge
my colleagues to adopt the Gutierrez/Peters Amendment and vote in favor
of the Credit Cardholders' Bill of Rights.
Mr. GUTIERREZ. Mr. Chairman, I yield back the balance of my time.
The Acting CHAIR. The question is on the amendment offered by the
gentleman from Illinois (Mr. Gutierrez).
The amendment was agreed to.
Amendment No. 5 Offered by Ms. Pingree of Maine
The Acting CHAIR. It is now in order to consider amendment No. 5
printed in House Report 111-92.
Ms. PINGREE of Maine. Mr. Chair, I have an amendment at the desk.
The Acting CHAIR. The Clerk will designate the amendment.
The text of the amendment is as follows:
Amendment No. 5 offered by Ms. Pingree of Maine:
After section 9, insert the following new section (and
redesignate the subsequent section accordingly):
SEC. 10. INTERIM IMPLEMENTATION REPORTS TO THE CONGRESS.
The Chairman of the Board of Governors of the Federal
Reserve System shall submit a report each 90 days after the
date of the enactment of this Act on the level of
implementation of the regulations required to be prescribed
under this Act to the Committee on Financial Services of the
House of Representatives and the Committee on Banking,
Housing, and Urban Affairs of the Senate until the Chairman
can report full industry implementation.
The Acting CHAIR. Pursuant to House Resolution 379, the gentlewoman
from Maine (Ms. Pingree) and a Member opposed each will control 5
minutes.
The Chair recognizes the gentlewoman from Maine.
Ms. PINGREE of Maine. Mr. Chair, I yield myself such time as I may
consume.
First I need to thank Chairman Frank, Chairman Gutierrez, and my
colleague, Representative Maloney, for their tireless leadership on
this very important bill before us today. This bill takes real steps to
curb the unfair, unreasonable, and deceptive practices that nearly 175
million Americans with credit cards are subject to.
Late fees, over-the-limit fees, arbitrary interests, increases in
interest rates, the credit card companies have gotten away with far too
much for far too long. It is time we level the playing field now for
small businesses, families and individuals.
In Maine, like so many places across the country, this is one of the
most important issues on the minds of hardworking men and women. If
they have not themselves been the victim of arbitrary rate increases,
double-cycle billing, and deceptive fees buried in pages of
indecipherable terms, then they know someone who has.
While these deceptive and misleading practices have always been
unfair, they have devastating financial consequences during this time
of economic difficulty when more and more people are using their credit
cards to buy gasoline, to pay for their health care bills, or put food
on the table.
In Maine, not only have we been customers, but we are also employees
of a credit card company. And as employees, we have seen firsthand the
pervasive and unethical methods that these companies employ. When
MBNA--now Bank of America--came into our community, people who had
traditionally
[[Page H5023]]
built homes or been fishermen found themselves using deceptive company
practices to sell their neighbors credit they couldn't afford, and it
took its toll.
Last fall, Nightline profiled Cate Columbo and Jerry Young of Camden,
Maine, who worked 10-hour shifts at MBNA pushing customers into taking
huge cash advances that they couldn't afford. The company urged
employees to take advantage of parents sending their kids to college,
homeowners, even veterans. In the Nightline piece, Cate said, ``I would
come home, and I would literally be crying in the sink doing dishes.''
The deceptive and misleading practices that Cate, Jerry and thousands
of others were pressured to enforce ran squarely counter to the core
values that Mainers and those across this country live by every day.
That is why it is so important to pass this landmark bill today.
I strongly support the bill before us, but I want to be sure that it
is implemented as soon and as well as possible. It is very important
that we, as Congress, should be diligent about making sure that the
industry and the regulators hold up their end of the legislation. My
amendment simply requires that the Chairman of the Board of Governors
of the Federal Reserve System reports on the level of implementation
every 90 days until he can report full industry adoption.
Mr. Chairman, consumers have demanded that Congress act to stop the
egregious practices of credit card companies, and it is our
responsibility to provide the accountability and oversight that is
necessary to ensure this happens. As we move to rebuild our economy in
a way that is honest and fair, this commonsense legislation will allow
cardholders to responsibly manage their finances.
Today, this body has the opportunity to change course by fixing a
broken credit card system. I urge a ``yes'' vote on the amendment and
the underlying bill.
I reserve the balance of my time.
Mr. NEUGEBAUER. We do not claim any time in opposition to the
amendment.
Ms. PINGREE of Maine. I yield back my time and I urge a ``yea'' vote.
The Acting CHAIR. The question is on the amendment offered by the
gentlewoman from Maine (Ms. Pingree).
The amendment was agreed to.
Amendment No. 6 Offered by Mr. Polis
The Acting CHAIR. It is now in order to consider amendment No. 6
printed in House Report 111-92.
Mr. POLIS. Mr. Chairman, I have an amendment at the desk.
The Acting CHAIR. The Clerk will designate the amendment.
The text of the amendment is as follows:
Amendment No. 6 offered by Mr. Polis:
In subparagraph (A) of the new paragraph (8) added to
section 127(c) of the Truth in Lending Act by section 7 of
the bill, insert ``or the parent or legal guardian of such
consumer is designated as the primary account holder'' before
the period at the end.
The Acting CHAIR. Pursuant to House Resolution 379, the gentleman
from Colorado (Mr. Polis) and a Member opposed each will control 5
minutes.
The Chair recognizes the gentleman from Colorado.
Mr. POLIS. Mr. Chairman, I rise in support of my amendment to ensure
that young Americans can continue to access credit and begin to
establish a credit history and learn financial literacy.
I would like to thank Congresswoman Maloney and her staff and
Chairman Frank and his staff for bringing this important consumer
protection bill to the floor and for consideration of my amendment.
In my district of Colorado, financially responsible families who have
paid their bills and been careful with credit have had the added insult
of skyrocketing interest rates imposed by the very banks who caused the
injury of this recession through their mismanagement.
We need available credit and fair borrowing terms in order to restore
our Nation's economic health. This bill is good for consumers and, by
reducing defaults and increasing consumer confidence, it is also good
for the financial services industry. Equitable terms will result in on-
time payments, making bank balance sheets healthier.
Management of credit is a matter of personal responsibility; however,
to be truly accountable, the rules must be clear. The Credit
Cardholders' Bill of Rights gives Americans the tools to be responsible
with credit, and I urge its swift passage.
Furthermore, Mr. Chairman, it is important to recognize the
professionals in the lending industry who have been the champions of
their customers. In Colorado, we have the Young Americans Center for
Financial Education. This bank for young people is teaching the next
generation how to use credit wisely and teaches about business
development and investment. Many other banks and credit unions,
realizing that the informed customer is the best customer, have offered
financial literacy and counseling courses, and these efforts are to be
applauded.
{time} 1230
Across the country, brokerage firms and even employers have taken
action to inform people about financial services. I want to commend
these efforts and encourage the entire industry to follow the example
of these leaders.
While regulatory reform is important, the blame for our economic woes
does not rest solely on the shoulders of the finance industry or
government regulation. We must also aggressively address our culture of
financial illiteracy. According to the consumer financial literacy
survey report released this week, 41 percent of American adults would
give themselves a C or below for financial literacy. More troubling is
the lack of knowledge about credit among younger Americans. We all know
that the credit mistakes of youth can carry serious long-term
consequences. If we expect the next generation of Americans to use
credit responsibly, we must ensure that they are exposed to the tools
of financial literacy at an early age.
It's for this reason that I have offered this amendment that will
continue to allow minors to have a credit card in their name under the
supervision of their parent or guardian. Not only is the practical
firsthand experience of credit critical to financial literacy and
establishing credit and personal responsibility, but for many families
it's also an important safeguard in emergency situations. The Credit
Cardholders' Bill of Rights is the beginning of what needs to be a
thorough discussion of making financial literacy universal. This
economic crisis has created a new awareness of the importance of
financial literacy, and I urge this Congress to support reforms not
only in regulation but in education to ensure that familiarity of
financial instruments give Americans of all ages access to increased
credit, homeownership, higher education, and are able to build wealth.
Today as we recognize the importance of financial literacy here on
Capitol Hill, let's put words to action for young people back in our
districts by protecting their ability to be introduced to credit.
I ask my colleagues to support my amendment to ensure age-appropriate
access to credit continues to be the law of the land, and I further ask
my fellow Members of Congress to pass this bill to give our
constituents the needed relief and reforms of the Credit Cardholders'
Bill of Rights.
I once again thank Congresswoman Maloney and Chairman Frank.
Mr. Chairman, I reserve the balance of my time.
Mr. NEUGEBAUER. Mr. Chairman, we have no opposition to this
amendment.
Mr. POLIS. Mr. Chairman, I yield back the balance of my time.
The Acting CHAIR. The question is on the amendment offered by the
gentleman from Colorado (Mr. Polis).
The amendment was agreed to.
Amendment No. 7 Offered by Mr. Jones
The Acting CHAIR. It is now in order to consider amendment No. 7
printed in House Report 111-92.
Mr. JONES. Mr. Chairman, I have an amendment at the desk.
The Acting CHAIR. The Clerk will designate the amendment.
The text of the amendment is as follows:
Amendment No. 7 offered by Mr. Jones:
After section 9, insert the following new section (and
redesignate the subsequent sections accordingly):
SEC. 9. PROCEDURE FOR TIMELY SETTLEMENTS OF DECEDENT
OBLIGORS' ESTATES.
(a) In General.--Chapter 2 of the Truth in Lending Act (
U.S.C. 1631 et seq.) is amended
[[Page H5024]]
by adding at the end the following new section:
``Sec. 140A Procedure for timely settlements of decedent
obligors' estates
``The Board, in consultation with the Federal Trade
Commission and each other agency referred to in section
108(a), shall prescribe regulations to require any creditor,
with respect to any credit card account under an open end
consumer credit plan, to establish procedures to ensure that
any administrator of an estate of any deceased obligor with
respect to such account can resolve outstanding credit
balances in a timely manner.''.
(b) Clerical Amendment.--The table of sections for chapter
2 of the Truth in Lending Act is amended by inserting after
the item relating to section 140 the following new item:
``140A. Procedure for timely settlements of decedent obligors'
estates.''.
The Acting CHAIR. Pursuant to House Resolution 379, the gentleman
from North Carolina (Mr. Jones) and a Member opposed each will control
5 minutes.
The Chair recognizes the gentleman from North Carolina.
Mr. JONES. Mr. Chairman, I first would like to thank Chairman Frank
and Mrs. Maloney for permitting me to bring this amendment to the
floor. This amendment today reflects a personal story that I would like
to tell in just a very few minutes.
A childhood friend of mine, Ben Monk, died of cancer in January. His
brother, J.Y. Monk, is also a very close and dear friend of mine. As
the estate executor, J.Y. Monk had a difficult time resolving the
outstanding balance of Ben's account. He sent four separate letters to
the credit card company, Capital One, requesting the account balance
amount. He called Capital One on four different occasions. He
repeatedly faxed and mailed Capital One his brother's death certificate
and letters of testimony. He was never contacted in return and was
unable to gain access to the account balance due. Meanwhile, Capital
One was collecting very high interest payments on the account.
This was unacceptable. It is already difficult enough for families to
take up the practical matter that must be dealt with soon after a loved
one dies. They should not have to chase after creditors and get the
runaround from poor customer service.
This amendment is very simple. It would require the Federal Reserve
Board to establish regulations to allow estate administrators to
resolve outstanding credit balances on credit card accounts in a timely
manner. This amendment would allow a deceased person's estate to
quickly settle their account and pay off the remaining debt.
According to the Congressional Research Service, there is no current
standard for credit card companies to follow to wind down estates in a
timely manner when a deceased person's estate is trying to be settled.
This amendment would help estate administrators to quickly and without
hassle be able to bring a resolution to the estate.
Again, I would like to thank the chairman and Mrs. Maloney. I would
like to thank my side for permitting me to bring this to the floor of
the House.
Mr. Chairman, I reserve the balance of my time.
Mr. FRANK of Massachusetts. Mr. Chairman, I rise in very nominal
opposition to the amendment.
The Acting CHAIR. The gentleman is recognized for 5 minutes.
Mr. FRANK of Massachusetts. Mr. Chairman, I am opposed only in that
by bringing forth this amendment, the gentleman from North Carolina has
revealed the imperfection of our product. We should have included this
in the first place.
But it is a very good idea, and I congratulate him for his diligence.
And this is the process at its best, a specific issue which was called
to the attention of a Member in a concrete way, and he responds not
simply in terms of that specific situation but with a broader solution.
With that, Mr. Chairman, I now yield such time as she may consume to
the gentlewoman from California (Ms. Lee).
Ms. LEE of California. First, let me thank the chairman for yielding
and for his tremendous leadership in bringing this very important bill
to the floor today.
Mr. Chairman, I believe that the critical protections contained in
this legislation will strengthen the regulations issued by the Federal
Reserve, and I strongly support its passage.
However, Mr. Chairman, I am concerned that during these incredibly
difficult and challenging economic times, our constituents are
increasingly being squeezed with egregious fees and dubious business
practices by the very banks that their tax dollars have been bailing
out. The newspapers are rife with stories about consumers being gouged,
mind you, gouged by banks that have been suddenly jacking up their
interest rates on their credit cards or imposing new monthly service
charges or reducing credit limits with little or no explanation. In
most cases these tactics are being used on consumers, although they
carry a balance from month to month, they pay their bills on time,
they're playing by the rules, and they make at least their minimum
payment. We've heard countless, countless stories of bait-and-switch
tactics by credit card issuers who suddenly raise interest rates
because a consumer is a few days late in paying another creditor. This
is just downright wrong. It's outrageous.
Years ago I worked with now-Senator Sanders on legislation, and this
was when I was on the Financial Services Committee, to address this
practice of universal default. I am pleased that this language is
included in this bill, but it's critical that the protections banning
this practice are put into place immediately.
Mr. Chairman, the Federal Reserve has already determined that the use
of these unfair bait-and-switch profit-maximizing tactics must end. I
believe that we can and we should end these practices at the earliest
possible date, like now.
Mr. FRANK of Massachusetts. I will reclaim my time to say the
gentlewoman has been a staunch advocate of this. She was thinking about
an amendment. I regret that we were in a situation where we weren't
able to move the date up for a variety of reasons.
I will say this: if the banks, the credit card issuers, use the time
between now and the effective date in a way that is abusive of
customers, if they use the time not simply to get ready for the change
that they say they need, but if they use the interim period to raise
rates on people retroactively and to do other things that are abusive,
to me that will be a very strong argument for speeding up the date.
Now, the Senate hasn't acted on this bill yet, and it doesn't become
law until they do and we go to conference. If we see a pattern of the
credit card companies using the time lag to engage in practices that
this bill seeks to stop in an excessive way, then I will urge my Senate
colleagues to speed up the date and we will acquiesce.
Mr. Chairman, I now yield on this issue to one of the main advocates
here, the gentleman from North Carolina (Mr. Watt).
Mr. WATT. I thank the gentleman for yielding, and I think he's
yielding to me because I made this point in the committee markup that
credit card companies were engaging in negative conduct in the interim
before this bill gets implemented, and Mr. Frank made exactly the same
commitment to me at that point, and we're certainly going to push them
on that.
Mr. FRANK of Massachusetts. Mr. Chairman, I will yield again to the
gentlewoman from California.
Ms. LEE of California. I certainly thank you for your very strong
statement.
I just want to mention that originally, as I understand it, this bill
did contain a 3-month window following the date of enactment. And I
want to thank Congresswoman Carolyn Maloney from New York for her
leadership on this bill, who really understands the need to do this as
quickly as possible.
The fact is, as the chairman noted, the banks know that the
handwriting is on the wall. They're boosting up fees and rates on
consumers now, and we have a lot of evidence of that. And the longer we
wait to ban these practices, the more our constituents will suffer.
Mr. FRANK of Massachusetts. Reclaiming my time, Mr. Chairman, if the
handwriting on the wall becomes graffiti, in our view, then out comes
the whitewash brush. So we'll be very clear. We were told they needed
time to get things ready. If it appears that that time is being used to
take advantage of consumers and to try to get in some
[[Page H5025]]
last licks before the rule goes into effect, then I and I believe the
overwhelming majority of the committee and of the House will urge our
colleagues in the Senate to speed up the date in their version and we
will acquiesce with that.
Mr. JONES. Mr. Speaker, I would like to close by thanking them again
for this opportunity to bring this to the floor of the House, and I
hope that the House will pass this amendment and also pass this bill.
It's much needed.
Mr. WATT. Will the gentleman yield?
Mr. JONES. I yield to the gentleman from North Carolina.
Mr. WATT. I neglected to address the gentleman's amendment, Mr.
Chairman.
I want to urge my strong support for the gentleman's amendment from a
personal experience. I was the administrator of my brother's estate
after he died more than 2 years ago. I'm still getting bills that I
have paid off to credit card companies out of that estate. So it's a
serious problem and I am glad he's addressing it.
Mr. JONES. Mr. Chairman, I thank the gentleman from North Carolina.
Mr. Chairman, I yield back the balance of my time.
The Acting CHAIR. The question is on the amendment offered by the
gentleman from North Carolina (Mr. Jones).
The amendment was agreed to.
Amendment No. 8 Offered by Mrs. Maloney
The Acting CHAIR. It is now in order to consider amendment No. 8
printed in House Report 111-92.
Mrs. MALONEY. Mr. Chairman, I have an amendment at the desk.
The Acting CHAIR. The Clerk will designate the amendment.
The text of the amendment is as follows:
Amendment No. 8 offered by Mrs. Maloney:
Strike out subsection (m) of section 127B of the Truth in
Lending Act (as added by section 4 of the bill) and insert
the following new subsection:
``(m) Opt-in Required for Over-the-Limit Transactions if
Fees Are Imposed.--
``(1) In general.--In the case of any credit card account
under an open end consumer credit plan under which an over-
the-limit-fee may be imposed by the creditor for any
extension of credit in excess of the amount of credit
authorized to be extended under such account, no such fee
shall be charged unless the consumer has elected to permit
the creditor, with respect to such account, to complete
transactions involving the extension of credit, with respect
to such account, in excess of the amount of credit
authorized.
``(2) Disclosure by creditor.--No election by a consumer
under paragraph (1) shall take effect unless the consumer,
before making such election, received a notice from the
creditor of any over-the-limit fee in the form and manner,
and at the time, determined by the Board.
``(3) Form of election.--A consumer may make the election
referred to in paragraph (1) orally or in writing.
``(4) Time of election.--A consumer may make the election
referred to in paragraph (1) at any time and it shall be
effective until the election is revoked by the consumer
orally or in writing.
``(5) Regulations.--
``(A) In general.--The Board shall issue regulations
allowing for the completion of over-the-limit transactions
that for operational reasons exceed the credit limit by a de
minimis amount, even where the cardholder has not made an
election under paragraph (1).
``(B) Subject to no fee limitation.--The regulations
prescribed under subparagraph (A) shall not allow for the
imposition of any fee or any rate increase based on the
permitted over-the-limit transactions with respect to the
account of any cardholder who has not made the election in
paragraph (1).
``(C) Disclosures.--The Board shall prescribe regulations
governing any disclosure under this subsection.''.
The Acting CHAIR. Pursuant to House Resolution 379, the gentlewoman
from New York (Mrs. Maloney) and a Member opposed each will control 5
minutes.
The Chair recognizes the gentlewoman from New York.
Mrs. MALONEY. Mr. Chairman, I yield myself 2\1/2\ minutes.
Last week when the President met with executives of the card
companies, he said that credit cards had become unnecessarily
complicated for consumers, often leading them to pay more than they
reasonably expect. After his meeting, his administration reached out to
Congress to offer their support of the credit cardholders' bill of
rights but also to offer additional amendments and provisions. The one
that we are considering now is one put forth by the administration, and
this would require cardholders to opt into any over-the-limit coverage
on their credit card.
Our constituents are faced with a multitude of fees and penalties
that can be assessed to their credit card accounts. In many cases they
do not even know the fees exist because disclosure agreements can be
confusing and hard to understand. A recent editorial in the New York
Times called ``Over the Limit'' detailed one of the so-called ``worst
tricks'' used by credit card companies, ``allowing a consumer to
overcharge on his or her account but when the bill arrives, the
consumer has been assessed an over-the-limit fee.''
I would like to place this editorial in the Record.
[From the New York Times, Apr. 25, 2009]
Over the Limit
President Obama told banking executives this week to clean
up their credit card business. He made clear that he
understands the billowing anger and the huge strains placed
on millions of American cardholders who face sudden interest
rate spikes, hidden fees and tricky contracts that no one
without a law degree and a magnifying glass can hope to
master.
His promises will amount to little unless he follows
through quickly to strengthen bills in Congress designed to
protect credit card customers.
The president said after meeting credit card executives on
Thursday that he and his economic team recognize the need for
credit cards, especially in a tough economy. Small businesses
often depend on the cards to order goods or meet the payroll.
And consumers have learned to enjoy instant credit at the
checkout counter. But as a longtime user of credit cards
himself, Mr. Obama told banking executives that it is time to
reform this area of their business.
He demanded stronger protections against unfair rate
increases and abusive fees along with more oversight and
enforcement. He called for clarity. He wants contracts
written in plain language, minus fine print or ``anytime, any
reason rate hikes.'' He wants people to be able to comparison
shop online, with one option being ``a plain-vanilla, easy-
to-understand, simplest-terms-possible'' card for the average
user.
Credit card operators have long resisted such reforms, and
earlier experiments with self-policing resulted in very
spotty improvements. After complaints from cardholders who
felt tricked by their banks, the Federal Reserve last year
proposed several useful changes that will not, unfortunately,
take effect until July 2010.
There's a better way to help consumers. A credit card bill
of rights proposed by Democratic Representatives Barney Frank
of Massachusetts and Carolyn Maloney of New York would codify
many of the Fed's rules into law. It would ban interest rate
increases on existing balances unless payment is more than 30
days late, and it would forbid ``double-cycle billing,''
which means charging interest on debts paid off the previous
month.
It would also require 45 days' notice for a rate increase
in most cases. An even stronger bill by Senator Christopher
Dodd of Connecticut would make it harder for people under the
age of 21 to get cards, far too many of whom now think
plastic is simply another form of cash. It would also require
creditors to apply a cardholder's payment to the balance with
the highest interest rate. So far, these reforms face fierce
Republican opposition, especially in the Senate.
If the president is really serious about credit card
relief, he could pressure Congress to end some of the
industry's worst tricks right now. Remember when credit card
limits caused great embarrassment at the restaurant? These
days, many cards allow the overcharge, sparing the
embarrassment but socking the customer with a large fee at
billing time. One solution would be to offer consumers the
choice if a real ceiling that renders cards unusable above
that limit.
Mr. Obama has spent a lot of time and energy trying to save
the banks. He and Congress must also do more to spare their
customers.
Our amendment would require credit cardholders to opt in to receive
over-the-limit protection on their credit card in order for a credit
card company to charge an over-the-limit fee. Additionally, the
amendment allows for transactions that go over the limit to be
completed for operational reasons as long as they are of a small
amount. But the credit card company is not allowed to charge a fee.
{time} 1245
For far too long, credit cardholders have been alone in the fight to
bring reasonable standards back to credit card practices. With the
passage of this amendment and the underlying bill, the Credit
Cardholders' Bill of Rights, consumers will be treated more fairly by
credit card issuers and will be better able to manage their accounts.
I urge a ``yes'' vote on this amendment.
I reserve the balance of my time.
[[Page H5026]]
Mr. NEUGEBAUER. Mr. Chairman, I claim time in opposition.
The Acting CHAIR. The gentleman from Texas is recognized for 5
minutes.
Mr. NEUGEBAUER. Mr. Chairman, here we go again taking choices away
from the people that use credit cards, a very valuable tool for their
personal finances. Just imagine, you are at a banquet or someplace and
you give the maitre d' your credit card. Now you go over there and they
put the credit card in, and it comes back rejected.
And you face the embarrassment of that, and you have called the
credit company and you find out, well, you didn't opt into a service
that we provide, and so we don't provide you the opportunity to go over
your line of credit. You said, Well, how much was I over my line of
credit? Well, I was over by $4.
What we find today, according to the American Bankers Association, 99
percent of the people opt in or avoid opting out because they like that
valuable service that they have.
So, again, what we would have here is a situation where people may
not even know that this service is available to them. Maybe they are
making their utility bill payment and they find out that their card was
rejected because they didn't have this service. It's 2 or 3 weeks
before they get a notice from their utility company and find out that
their utilities are about to be shut off.
Now, this is a system that is really not broken. In fact, the Federal
Reserve, in their study, when they looked at these regulations, looked
at that issue, decided to leave it alone, found out it was working
extremely well.
Again, we are micromanaging this process. And the big losers aren't
going to be the credit card companies, who, I think, as a lot of people
are trying to attack with this bill, the big losers are going to be the
consumers that rely on that very valuable service.
So I am in strong opposition to the gentlewoman's amendment and urge
my colleagues to vote ``no.''
I reserve the balance of my time.
Mrs. MALONEY. I yield the balance of my time to my good friend and
colleague and coauthor of this amendment, along with the
administration, Diane Watson.
The Acting CHAIR. The gentlewoman from California is recognized for 3
minutes.
Ms. WATSON. Mr. Chairman, I rise today in enthusiastic support for
the Maloney-Watson amendment to H.R. 627.
I would like to thank her deeply for her leadership on the bill and
for allowing me to join with her in her amendment.
This amendment will increase the level of fairness in the
relationship between constituents and their credit card companies by
limiting the ability of credit card companies to authorize transactions
in excess of a consumer's credit limit.
Without this amendment, consumers have to go out of their way to opt
into an election program to stop their credit card company from
authorizing over-the-limit transactions, which incur additional fees
and indebtedness. This amendment will strengthen the bill by only
allowing credit card companies to authorize over-the-limit transactions
for consumers who specifically request the ability to do so.
I urge my colleagues to vote ``yes'' on this amendment to ensure
American consumers are spared from additional unwanted fees and debts.
Mr. NEUGEBAUER. May I inquire how much time I have remaining.
The Acting CHAIR. The gentleman has 3 minutes.
Mr. NEUGEBAUER. I yield the balance of my time to the gentleman from
Texas (Mr. Hensarling).
Mr. HENSARLING. I thank the gentleman for yielding.
I listened to the gentlelady from New York, who sponsored the bill,
talk about this is a trick that credit card companies use.
Well, we don't want credit card companies to use tricks. But, you
know what, Mr. Chairman? They can't use tricks if we will strengthen
the competitive market and ensure consumer choice. They can't use
tricks if we have an elective disclosure and we police it.
Again, I congratulate the gentlelady for that title in her bill,
which, I believe, roughly parallels the rules that the Federal Reserve
has promulgated after their 3-year study. Indeed, we need better
disclosure.
It's better disclosure we need. We need greater consumer choice. We
need strength in markets.
Also, tricks can't be used if consumers, who have effective
disclosure, will take some, some responsibility to know the terms that
they are agreeing to. By definition, if they agreed to accept a credit
card, they are opting into terms.
Now, that's not effective today because we don't have effective
disclosure. But ostensibly we have a title in this legislation, which I
assume will soon be passed. If not, we have the regulations of the
Federal Reserve that will ensure that we have effective disclosure,
that we empower consumers.
But let's not take their choices away from them, especially when all
the evidence we have seen, anecdotal, statistical, tells us that
consumers overwhelmingly want this option. They want it.
So if we are already admitting today in some respects that the
disclosure isn't there, you know, I don't want to have to tell them
that, I am sorry, they wouldn't accept your credit card, but, you know,
Congress passed a law that said you had to go read the fine print
before you could go get this particular service. Again, I think that we
are taking away consumer choice by doing this.
As the gentleman from Texas said, we are trying to micromanage the
terms that ought to be managed within the framework of a competitive
marketplace, with consumer choice, with informed consumers, with
effective disclosure.
But quit protecting consumers from their choices. Quit protecting
them from competition. You are making their lot worse, not better, when
you do this.
So I would urge rejection of this amendment.
The Acting CHAIR. The question is on the amendment offered by the
gentlewoman from New York (Mrs. Maloney).
The question was taken; and the Acting Chair announced that the ayes
appeared to have it.
Mr. NEUGEBAUER. Mr. Chairman, I demand a recorded vote.
The Acting CHAIR. Pursuant to clause 6 of rule XVIII, further
proceedings on the amendment offered by the gentlewoman from New York
will be postponed.
Amendment No. 9 Offered by Mr. Hensarling
The Acting CHAIR. It is now in order to consider amendment No. 9
printed in House Report 111-92.
Mr. HENSARLING. Mr. Chairman, I have an amendment at the desk.
The Acting CHAIR. The Clerk will designate the amendment.
The text of the amendment is as follows:
Amendment No. 9 offered by Mr. Hensarling:
In subsection (b) of section 127B of the Truth in Lending
Act (as added by section 2(b) of the bill), insert after
subparagraph (D) the following new subparagraph:
``(E) Transparent advanced notice of rate increase.--
Notification of the increase is provided to the consumer in
writing, in clear and conspicuous language, at least 90 days
before the increase is scheduled to take effect, provided
that the applicability of this exception is fully described
to the consumer in their contract and at least once annually
thereafter, in a clear and conspicuous manner.''.
The Acting CHAIR. Pursuant to House Resolution 379, the gentleman
from Texas (Mr. Hensarling) and a Member opposed each will control 5
minutes.
The Chair recognizes the gentleman from Texas.
Mr. HENSARLING. Mr. Chairman, I yield myself such time as I may
consume.
Mr. Chairman, this is a fairly simple amendment that is aimed, again,
at a form of embedded price controls within this legislation.
The underlying legislation would permit interest rates to rise on
existing balances under four narrow options. This amendment would say,
again, within the framework that we hope to achieve of protecting the
competitive marketplace, of assuring that we have effective disclosure,
this amendment would say that interest rates can vary as long as,
number one, the issuer has specifically reserved the right to raise
rates in its contract and has communicated that to the consumer.
Number two, the issuer communicates this fact to the consumer at
[[Page H5027]]
least once a year, and the issuer provides the consumer clear
notification 90 days in advance.
Again, this is a facet of risk-based pricing. Now, many of us believe
that this has been a good thing. It has empowered consumers who
previously didn't have access to credit to have access to credit.
As their circumstances change, if you do not allow risk-based
pricing, you are going to take credit opportunities away from them in
the middle of a credit crunch when they need it most.
Now, this gives a reasonable time period of 90 days to say, you know
what? If you don't want to have this card, you have got 90 days under
the old interest rate to pay off this balance and either get rid of the
card, find a new card, shop for a new card, do something.
But, ultimately, if we don't pass this amendment one of three things
is going to happen. Again, we are going to have a bailout, yet another
bailout from Congress. And that is the 50 percent of Americans who are
paying their bill on time, making at least the minimum payment at the
end of each month, they are going to be punished. They are going to
have to subsidize the rates for all.
Again, it's a facet of eroding risk-based pricing that takes us back
to an era where interest rates were 25 percent higher, everybody had to
pay the same rate. The good credit risk had to subsidize the bad credit
risk and everybody had this dreaded annual fee of 20 to $50.
We don't want to go back to that era. Assuming a competitive
marketplace, and, unfortunately, this legislation, I believe, in some
respects will result in a less competitive marketplace, I fear that
some of the smaller issuers will be driven out of the market.
But if we can have a competitive marketplace, and if we can assure
effective disclosure, then let's have the full benefits of risk-based
pricing. I think some people just don't want it. They want to force
those who pay their bill on time to somehow subsidize those who don't.
I fear, Mr. Chairman, that there is a lot at stake here. I mean, I
hear from my constituents about how important the credit cards are to
their lives, their small businesses.
I hear from a group, the family, Baker family of Rowlett, who said,
``Congressman, credit cards have been my main source of financing for
my small businesses for the past 13 years. Without access to this type
of instant credit, I would not be able to timely meet payroll.''
I mean, we have to help the small businesses.
I heard from the Weldon family of Garland. ``I use my credit card
just about everywhere. When I receive my monthly credit card bill, I
pay the full balance. I feel this legislation concerning credit cards
would be unfair to me and others who prefer to pay off their credit
cards each month. Why should we be punished for having good credit?''
Indeed, Mr. Chairman, it is a good question. Allow risk-based
pricing. Don't take credit away.
I reserve the balance of my time.
Mrs. MALONEY. Mr. Chairman, I claim time in opposition to the
amendment.
The Acting CHAIR. The gentlewoman from New York is recognized for 5
minutes.
Mrs. MALONEY. Mr. Chairman, I yield myself such time as I may
consume.
The amendment seeks to gut all of the consumer protections of the
bill as long as the credit card company gives the cardholder 90 days'
notice that they are going to do it. This is the exact same amendment
that was defeated in the committee with unanimous opposition from the
Democrats on the committee, and even a few Republicans voting in
opposition.
Allowing issuers to raise interest rates retroactively for a new
reason is just creating a loophole for issuers.
The bill allows issuers to impose retroactive interest rates if the
cardholder fails to pay or pays 30 days late, which is the time
commercial contracts deem late.
So if an issuer is harmed, they have a remedy. In the absence of
harm, it's hard to see why we would give the issuer the unilateral
right with 90 days' notice to raise the rate retroactively and change
the deal with the cardholder.
A deal should be a deal. They shouldn't have these opportunities to
change them.
As the Federal Reserve found, and this is important, this is a
Federal regulator, the Federal Reserve found most retroactive rate
increases are, and I quote, from the Federal Reserve, ``unfair and
deceptive.''
In our current mortgage reform discussions, we are trying to mitigate
losses by making sure borrowers can repay their loans. Retroactive rate
increases do the opposite. They slam borrowers with increased debt and
make it less likely that they will be able to repay and pay down the
balance.
I believe the best defense against the concerns raised by my
colleague is the use of sound underwriting standards by the issuers.
Additionally, nothing in the bill prohibits an issuer from lowering
the credit line or canceling the card if they are worried that the
cardholder will not repay.
{time} 1300
The bill also allows for fees if a customer does not pay on time, for
30 days, or has their check returned. Sound underwriting and these risk
mitigation tools will be far more effective in fighting the concerns
the gentleman is talking about.
I would say this amendment basically guts the protections that are in
the bill that have been endorsed by 54 editorial boards and endorsed by
numerous regulators, including the Federal Reserve, and this simply
creates a new loophole. I am deeply opposed to it, as was the committee
in the committee vote with Republicans' votes.
Mr. Chairman, I reserve the balance of my time.
Mr. HENSARLING. Mr. Chairman, I yield myself the balance of my time.
The Acting CHAIR. The gentleman is recognized for 1 minute.
Mr. HENSARLING. Mr. Chairman, I tried to listen very closely to the
gentlelady from New York, and what I think I heard was she would rather
credit card companies cancel credit cards than allow my constituents to
voluntarily agree to increases in their interest rate. That is not what
the people of the Fifth District want to achieve. When she says, well,
the credit card people are changing the deal, if it is in the
agreement, that is the deal. That is the deal that allows many people
to get credit in the first place and allows other people to have lower-
priced credit.
Again, I believe this legislation is changing the deal on the
American people, taking away their credit card options and
opportunities.
I heard from the Juarez family in Mesquite. ``I oppose this
legislation, as I have utilized my credit cards to pay for costly oral
surgeries. I do not want to get penalized by this legislation for
making my payments on time.''
Taking away risk-based pricing, which is disclosed, disclosed in the
agreement, is punishing, punishing people like the Juarez family in
Mesquite. I urge adoption of the amendment.
Mrs. MALONEY. The Federal Reserve's report on the rule they proposed,
which was very similar to the bill, in it they said that disclosure in
their studies was not enough; that the practices were so deceptive it
was hard for many consumers to understand them and the contract is so
complicated and the fine print so small that most people don't even
read it. So to build in another loophole undermines the whole purpose
of the bill.
This amendment was killed in the committee, and I urge my colleagues
to kill it again. It should be Black Flag dead, because it guts the
bill and the protections that we are trying to put in place to protect
America's consumers.
I yield back the balance of my time, and I urge a ``no'' vote on this
amendment.
The Acting CHAIR. The question is on the amendment offered by the
gentleman from Texas (Mr. Hensarling).
The amendment was rejected.
Amendment No. 10 Offered by Mr. Hensarling
The Acting CHAIR. It is now in order to consider amendment No. 10
printed in House Report 111-92.
Mr. HENSARLING. Mr. Chairman, I have an amendment at the desk.
The Acting CHAIR. The Clerk will designate the amendment.
[[Page H5028]]
The text of the amendment is as follows:
Amendment No. 10 offered by Mr. Hensarling:
In subsection (b) of section 127B of the Truth in Lending
Act (as added by section 2(b) of the bill), insert the
following new paragraph after paragraph (1) (and redesignate
the subsequent paragraphs accordingly):
``(2) Nonapplicability to certain creditors who make
available alternative card options.--The limitations on
retroactive rate increases and universal default shall not
apply to any creditor that offers a credit card account to
consumers under an open end consumer credit plan to the
extent such creditor--
``(A) makes at least 1 credit card option available to 100
percent of the creditor's existing consumers that does not
feature retroactive rate increases or universal default
billing practice; and
``(B) provides clear and conspicuous notice of the
availability of a credit card option referred to in
subparagraph (A) to the consumer customers of such creditor
at least once annually.''.
In subsection (e) of section 127B of the Truth in Lending
Act (as added by section 3(a) of the bill), insert after
paragraph (3) the following new paragraph:
``(4) Nonapplicability to certain creditors who make
available alternative card options.--The limitation on double
cycle billing shall not apply to any creditor that offers a
credit card account to consumers under an open end consumer
credit plan to the extent such creditor--
``(A) makes at least 1 credit card option available to 100
percent of the creditor's existing consumers that does not
feature double cycle billing; and
``(B) provides clear and conspicuous notice of the
availability of a credit card option referred to in
subparagraph (A) to the consumer customers of such creditor
at least once annually.''.
The Acting CHAIR. Pursuant to House Resolution 379, the gentleman
from Texas (Mr. Hensarling) and a Member opposed each will control 5
minutes.
The Chair recognizes the gentleman from Texas.
Mr. HENSARLING. Mr. Chairman, I yield myself such time as I may
consume.
Mr. Chairman, the underlying legislation here again seeks to erode
the ability of consumers to access credit, especially those who may
have checkered pasts, especially those who may be of low income. It
does it by trying to restrict risk-based pricing.
Again, there was an era in our country's history where a third fewer
people had access to consumer credit through credit cards. Everybody
had to pay the same universal high rate, 25 percent more than what we
are seeing today. We had the dreaded annual fees. There was no such
thing as airline miles, cash back, any of this.
The ability for creditors to price for what they view the risk of the
consumer has opened a market for people to have credit cards who
previously couldn't have them, people who might have had to turn to
pawn shops or payday lenders, who, again, serve very valuable functions
in our society, but people ought to have options.
The underlying bill functionally outlaws a practice called universal
default and a practice called double-cycle billing. Universal default
doesn't offend me. Double-cycle billing offends me. But I don't feel a
need to outlaw every practice in America that offends me personally,
because it may not offend somebody else.
Mr. Chairman, if there is an option out there in the marketplace with
14,000 different issuers, and through every hearing, every markup,
there was not one shred of evidence that we didn't have a competitive
market and that consumers had choices. Now, they may not understand
their choices, and that is the disclosure issue, but they have choices.
So I don't like double-cycle billing. I don't think it is
particularly fair and I wouldn't choose a credit card with it. But, Mr.
Chairman, you know, out there in the marketplace, people ought to have
options. Somebody ought to be able to say I prefer to have a credit
card with a 10 percent interest rate that has universal default and
double-cycle billing in it as opposed to paying a 13 percent interest
rate that doesn't have universal default, doesn't have double-cycle
billing.
Why are we taking consumer choices away from them and why do we
continue to contract credit when it is already being contracted in this
economic recession? I just don't understand that, Mr. Chairman. I do
not think it is good practice. Now, universal default, some cards use
it, some cards don't. It is a risk management tool for some.
I am not in the credit card business. I don't know what works. I just
want consumers to have choices. I want there to be a competitive
marketplace. I want there to be effective, fair disclosure, and I want
our Federal Government to police it. And there needs to be
repercussions for credit card companies that defraud, that mislead,
that use deceptive practices. But for us to come in and say
subjectively, well, we don't like that practice, we think it is unfair,
we think it is offensive. Well, maybe it is unfair and offensive to
you, but if it allows somebody a lower interest rate, shouldn't in the
land of the free they have that option? They should have that option.
So my amendment is a simple one. It simply says if a credit card
company has a credit card and they want to offer this credit card that
features either universal default or double-cycle billing, as long as
they offer a card that doesn't have these features, which many consider
to be unfair, unjust, then they can offer it. As long as all of their
customers are offered a card without the feature, then a consumer, if
they want to, can opt in to the card with these features if they think
the trade-offs benefit them and their family. That is all it says. This
is a consumer choice amendment, pure and simple. I urge its adoption.
I reserve the balance of my time.
Mr. GUTIERREZ. Mr. Chairman, I rise in opposition to the amendment.
The Acting CHAIR. The gentleman from Illinois is recognized for 5
minutes.
Mr. GUTIERREZ. I yield myself such time as I may consume.
I oppose this amendment because it would essentially allow credit
card insurers to circumvent most of the consumer protections in this
bill, such as double-cycle billing and retroactive pricing increases,
by simply making available one card that does not have these practices.
The key to this amendment is that credit card companies will not be
required to offer the cards to consumers that do not include predatory
practices. In other words, consumers with the highest credit scores,
those that have the ability to pay and the greatest assets and income,
will get the good card, the one without double billing, without
retroactive price increases, and those with low credit scores will get
the subprime cards that include the very deceptive practices that this
bill was intended to stop. That is why I have to be in opposition to
this.
It is almost as though we went through this for nothing. Allow this
amendment to pass, and most of the work we have done in protecting
consumers is undone.
I reserve the balance of my time.
Mr. HENSARLING. Mr. Chairman, I yield myself the balance of my time.
The Acting CHAIR. The gentleman is recognized for 45 seconds.
Mr. HENSARLING. Mr. Chairman, again what I see is we are trying to
protect consumers from their choices. We are trying to protect
consumers from their freedom. The consumer has the option. But I do
thank my friend, the distinguished chairman of the subcommittee, for
adding some clarity to the debate when he says the people with the good
credit ratings will get the better interest rate. That pretty well
makes my bailout argument.
That is what is happening. Half of America pays their bill on time at
the end of each month. Another 20 to 25 percent at least make the
minimum payment. Why should they be punished? Why should they be
punished with higher interest rates? Why do they have to be
homogenized?
We are getting away from risk-based pricing, and what will happen if
we don't pass this amendment is, number one, we will achieve the
bailout, and many people who would have received credit will no longer
receive credit. I urge adoption of the amendment.
Mr. GUTIERREZ. I yield 2 minutes to the gentlewoman from New York
(Mrs. Maloney).
Mrs. MALONEY. I thank the gentleman for yielding.
This is an amendment that Congressman Hensarling offered both at the
subcommittee and the full committee markups, and it was defeated both
times by unanimous Democratic opposition, with even a few Republican
votes in opposition to it.
[[Page H5029]]
Essentially what this amendment attempts is to create significant
exceptions to the consumer protections offered by the underlying
legislation and the final rule that was adopted by the Federal Reserve,
the Office of Thrift Supervision and the National Credit Union
Administrator. These three regulators have called the practices that my
colleague would attempt to exempt unfair, deceptive and
anticompetitive. Why would anyone in this body want to continue unfair,
deceptive and anticompetitive practices? Even competition of the free
market, they are saying it is anticompetitive.
I would like to point out during some of the many hearings and
meetings and seven hearings that we held on the topic in the last
several years, we frequently heard from academics, from regulators,
that disclosure is not enough. It is too confusing. It is deceptive.
Most consumers do not read the contract, they do not understand the
contract, and it is worded in a way that is deceptive.
The President called for a plain vanilla card that people could
understand. What this card would be that he is proposing is toxic. It
would continue the bad practices and defeat the whole purpose of the
bill. This amendment would create a subclass of credit cardholders who
would have little to no rights.
The bill provides baseline consumer protections that everyone should
enjoy. The last thing we should be doing is creating exceptions or
subsets that would allow these abusive practices to continue.
It is abusive. It is wrong. This amendment should be killed Black
Flag dead.
Mr. GUTIERREZ. Mr. Chairman, I yield myself the balance of my time.
The Acting CHAIR. The gentleman is recognized for 1\1/2\ minutes.
Mr. GUTIERREZ. First of all, let me suggest to the gentleman from
Texas (Mr. Hensarling) that this bill is not going to prohibit credit
card companies, once it is passed, to extend lines of credit at lower
interest rates to those who have higher credit scores. It is just not
going to do it. They will still be able to do that.
When he suggests to us that this is a choice, this is an option,
there are some options and some choices we should stand up against, and
this is one of those choices and one of those options, because it is
going to affect those that cannot read. I am sure the gentleman would
never suggest that consumers understand every point of the fine print
on that credit card. It is going to be hidden there. And the Federal
Reserve Board has said to us it is bad practices. It is predatory. It
is not fair to simply give notice.
Lastly, look, all we are saying is, yes, we are stopping credit card
companies and we are stopping consumers from having the ``choice,'' we
like to suggest the ``harm'' of a credit card company being able to
give you 90 days' notice and say, you know the $1,000 you took last
year at 18 percent? They can say, for the whole last year that you have
paid it, we are going to go retroactively and double that interest
rate, and we want the money, although you have made all of the payments
all year long on time, we are going to double the interest rate. Give
me more money.
That is fundamentally unfair, to retroactively go back and claim
money just because you can, just because you sent somebody a 90-day
notice.
I urge everybody to vote against this amendment.
The Acting CHAIR. The question is on the amendment offered by the
gentleman from Texas (Mr. Hensarling).
The amendment was rejected.
{time} 1315
Amendment No. 11 Offered by Mr. Minnick
The Acting CHAIR. It is now in order to consider amendment No. 11
printed in House Report 111-92.
Mr. MINNICK. Mr. Chairman, I have an amendment at the desk.
The Acting CHAIR. The Clerk will designate the amendment.
The text of the amendment is as follows:
Amendment No. 11 offered by Mr. Minnick:
In paragraph (2) of section 127B(a) of the Truth in Lending
Act (as added by section 2(a) of the bill, strike ``14th''
and insert ``7th''.
The Acting CHAIR. Pursuant to House Resolution 379, the gentleman
from Idaho (Mr. Minnick) and a Member opposed each will control 5
minutes.
The Chair recognizes the gentleman from Idaho.
Mr. MINNICK. Mr. Chairman, I yield myself as much time as I may
consume.
Mr. Chair, H.R. 627 requires a creditor to provide a consumer at
least 45 days' notice before increasing the consumer's credit card
rate. However, in this bill the higher interest rate taking effect on
day 45 applies only to the extent that the consumer's balance is more
than it was at the end of 14 days after receiving the notice.
However, determining the protected balance as of day 14 may still
provide enough time for consumers to incur higher overall debt than may
be appropriate for them by inflating the balance that will be protected
from the rate increase and, in the process, allow consumers to game the
system at the expense of creditors.
This amendment would provide that the amount of the balance protected
from the higher interest rate be set at the 7-day mark, instead of at
14 days. This change would still give consumers the full 45 days to
shop for an alternative source of credit for a better deal, but it
would reduce their ability to inappropriately inflate their balances to
avoid the application of the higher rate in the event that they do not
transfer their balances to another card by that time.
I reserve the balance of my time.
Mr. HENSARLING. Mr. Chairman, we have no one to claim time in
opposition.
Mr. MINNICK. Mr. Chairman, I ask that my colleagues support this
amendment. I yield back the balance of my time.
The Acting CHAIR. The question is on the amendment offered by the
gentleman from Idaho (Mr. Minnick).
The amendment was agreed to.
Amendment No. 12 Offered by Mr. Price of North Carolina
The Acting CHAIR. It is now in order to consider amendment No. 12
printed in House Report 111-92.
Mr. PRICE of North Carolina. Mr. Chairman, I have an amendment at the
desk.
The Acting CHAIR. The Clerk will designate the amendment.
The text of the amendment is as follows:
Amendment No. 12 offered by Mr. Price of North Carolina:
After section 8, insert the following new section (and
redesignate subsequent sections accordingly):
SEC. 9. ENHANCED MINIMUM PAYMENT DISCLOSURES.
Paragraph (11) of section 127(b) of the Truth in Lending
Act (15 U.S.C. 1637(b)(11)) is amended to read as follows:
``(11) Minimum payment disclosures.--
``(A) Minimum payment warning.--A written statement in the
following form: `Minimum Payment Warning: Making only the
minimum payment will increase the interest you pay and the
time it takes to repay your balance.'.
``(B) Information on outstanding balance.--Not less than
once per calendar quarter, such billing statement shall also
include repayment information that would apply to the
outstanding balance of the consumer under the credit plan,
including--
``(i) the number of months (rounded to the nearest month)
that it would take to pay the entire amount of that balance,
if the consumer pays only the required minimum monthly
payments and if no further advances are made;
``(ii) the total cost to the consumer, including interest
payments, of paying that balance in full, if the consumer
pays only the required minimum monthly payments and if no
further advances are made;
``(iii) the monthly payment amount that would be required
for the consumer to eliminate the outstanding balance in 12
months, 24 months, and 36 months, if no further advances are
made, and the total cost to the consumer, including interest
and principal payments, of paying that balance in full if the
consumer pays the balance over 12, 24, or 36 months,
respectively; and
``(iv) a toll-free telephone number at which the consumer
may receive information about accessing credit counseling and
debt management services.
``(C) Exception to requirements of subsection (b).--The
quarterly disclosure requirements in subsection (B) shall not
apply with respect to--
``(i) a calendar quarter if, in the 2 consecutive billing
cycles preceding the end of such quarter, a consumer has paid
the entire balance of the bill in full;
``(ii) a calendar quarter if, at the end of the calendar
quarter, a consumer has an outstanding credit balance of zero
or has a positive credit; or
``(iii) any class of consumers for which the Board has
determined will not benefit substantially from additional
disclosures.
[[Page H5030]]
``(D) Applicable rates to be used in disclosures.--
``(i) In general.--Subject to clause (ii), in making the
disclosures under subparagraph (B), the creditor shall apply
the interest rate or rates in effect on the date on which the
disclosure is made until the date on which the balance would
be paid in full.
``(ii) Special rule in case of temporary rate.--If the
interest rate in effect on the date on which the disclosure
is made is a temporary rate that will change under a
contractual provision applying an index or formula for
subsequent interest rate adjustment, the creditor shall apply
the interest rate in effect on the date on which the
disclosure is made for as long as that interest rate will
apply under that contractual provision, and then apply an
interest rate based on the index or formula in effect on the
applicable billing date.
``(E) Form and prominence of disclosure.--All of the
information described in subparagraph (B) shall--
``(i) be disclosed in the form and manner which the Board
shall prescribe, by regulation, and in a manner that avoids
duplication; and
``(ii) be placed in a conspicuous and prominent location on
the billing statement in conspicuous typeface.
``(F) Tabular format.--In the regulations prescribed under
subparagraph (D), the Board shall require that the disclosure
of such information shall be in the form of a table that--
``(i) contains clear and concise headings for each item of
such information; and
``(ii) provides a clear and concise form stating each item
of information required to be disclosed under each such
heading.
``(G) Location and order of table.--In prescribing the form
of the table under subparagraph (E), the Board shall require
that--
``(i) all of the information in the table, and not just a
reference to the table, be placed on the billing statement,
as required by this paragraph; and
``(ii) the items required to be included in the table shall
be listed in the order in which such items are described in
subparagraph (B).
``(H) Substitution of terminology.--In prescribing the form
of the table under subparagraph (D), the Board may employ
terminology which is different than the terminology used in
subparagraph (B), if such terminology is more easily
understood and conveys substantially the same meaning.
``(I) `Rounding' regulations.--For purposes of determining
whether an error in the disclosures required by subparagraph
(B) constitutes a legal cause of action against a creditor or
any other party, the standard referred to under the heading
`Rounding assumed payments, current balance and interest
charges to the nearest cent' in the publication by the Board
in the Federal Register (74 F.R. 5385) on January 29, 2009,
of the final regulation revising part 226 of title 12 of the
Code of Federal Regulations (Regulation Z), or a standard
that affords substantially similar protections as determined
by the Board, shall apply for purposes of the determination
with regard to such disclosures.''.
The Acting CHAIR. Pursuant to House Resolution 379, the gentleman
from North Carolina (Mr. Price) and a Member opposed each will control
5 minutes.
The Chair recognizes the gentleman from North Carolina.
Mr. PRICE of North Carolina. Mr. Chairman, I yield myself 1 minute.
Minimum payment practices, which often are deceptive at best and
abusive at worst, clearly contribute to the problem of unmanageable
debt. And they need to be reined in. That's exactly what the Price-
Miller of North Carolina-Moran of Virginia-Quigley-Stupak-Sutton-Lowey
amendment will do. Our amendment would ensure that consumers receive a
warning of the risks of making only the minimum monthly payment and
information on the total cost of paying only monthly minimum payments
on their balance.
It would also require issuers to provide quarterly assessments of the
monthly payments that must be made to pay off the current balance of
the consumer in 1, 2 or 3 years. And it would establish consumer credit
counseling and debt management services through a toll-free telephone
number.
Let me assure colleagues, we've sought to ensure that these
requirements are not too onerous for credit card companies. For
example, disclosure requirements target only consumers who regularly
have not paid their balances in full. Our amendment will help consumers
regain control of cascading credit card debt.
So I urge colleagues to support this amendment to provide American
families with the tools they need to help them manage their money
effectively.
I reserve the balance of my time.
Mr. HENSARLING. Mr. Chairman, we have no one to claim time in
opposition.
Mr. PRICE of North Carolina. Mr. Chairman, I yield 1 minute to my
colleague from North Carolina, who has served with distinction on the
Banking Committee, Brad Miller.
Mr. MILLER of North Carolina. Mr. Chairman, about 35 million
Americans just pay their monthly payment, the minimum monthly payment
on their credit card every year. And some of the opponents of this bill
may have very little sympathy for families that are deep in debt. But
as our economy has produced billionaires who have done nothing of any
conspicuous value to society, there are millions of American families
that are working very hard and struggling to get by, and it is very
tempting when they're doing triage with their bills and they know they
can't pay everything, for their eye to skip down to the minimum monthly
payment and just pay that. This bill makes sure they know what the
consequences of that are. This amendment makes sure. It informs them of
what kind of debt they're going to be in, how much it's going to cost
them in interest, how long they're going to be in debt, how deep the
hole will be, and what it is going to take to get out.
I applaud Mr. Price for his efforts. And I urge all Members to vote
for this amendment.
Mr. PRICE of North Carolina. I thank my colleague. I would like at
this point to yield 1 minute to a new colleague, Representative
Quigley, who is already distinguishing himself as a protector of the
consumer.
Mr. QUIGLEY. I rise in strong support of this amendment because today
the average American can apply for a credit card anywhere, at a grocery
store, at an airport, a ballpark, even college campuses. It all seems
so easy.
Unfortunately, the terms of the agreements aren't so easy. In some
cases, terms have become so complicated that the average consumer
cannot always know what they've gotten themselves into.
Now more than ever, Americans are turning to their credit cards to
get them through the end of the month, and in turn, the U.S. credit
card debt has reached an all-time high.
Meanwhile, almost half of Americans carry a balance and have no idea
how long it'll take to pay that down. The Credit Cardholders' Bill of
Rights will protect consumers from predatory practices, and this
specific amendment will give them the ability to pay down their debts.
I urge my colleagues to vote ``yes'' on this amendment and the
underlying bill.
Mrs. LOWEY. Mr. Chair, I rise in strong support of the amendment, of
which I am a cosponsor.
The amendment would require additional disclosure information on
credit card statements. While most cardholders know it takes a great
deal of time to pay off a balance by making only the minimum payment,
most do not understand the total additional costs they will pay. This
amendment would change that.
Based on industry norms of an 18 percent APR and 4 percent minimum
payment requirement, a cardholder will spend 87 months and $1,515
paying off a balance of $1,000 if making only the minimum payments. The
finance charges are more than 50 percent of the actual balance.
Our amendment would require that each statement have a warning on
minimum payments and that every quarter, cardholders receive a
statement that lists the number of months it would take to pay the
entire balance if only the minimum payments are made, along with the
total cost of doing so. Those statements would also have to list the
necessary payment to pay off the balance in 12, 24, and 36 months, as
well as a toll-free number to receive information about accessing
credit counseling and debt management services.
Credit cardholders have a right to know the real cost of making only
minimum payments. For that reason, I urge your support for the
amendment.
I would also like to voice my strong support for the underlying bill.
In recent months, Congress has been dominated by rescue and economic
recovery legislation. But there are few better ways to instantly help
hard-working Americans than to end costly, abusive credit card
practices.
For too long, banks have saddled cardholders with deceptive marketing
and fine print. The New York Consumer Protection Board reports that
credit card complaints comprise more than a quarter of those it
receives, and cards with debt have an average balance of $5,700.
Because of unfair practices, one hidden fee snowballs into ballooning
interest rates and thousand dollar balances that many families
struggling to get by with today's economic challenges cannot afford.
[[Page H5031]]
I regret that the Rules Committee did not make in order an amendment
I submitted that would have applied the protections in the bill to
credit cards issued to small businesses. However, this is an excellent
bill that I am proud to cosponsor, and I urge your support.
Mr. MORAN of Virginia. Mr. Chair, I am pleased to be a cosponsor of
Representative Price's amendment to H.R. 627. This is an issue on which
I have worked for a number of years, so I am honored to be able to join
my friend and colleague, and to urge adoption of this critical consumer
protection amendment. This provision is a valuable disclosure amendment
which would call for card issuers to provide three very important
pieces of information to cardholders at least once per calendar quarter
on their billing statements.
First, the statement would report how long it would take the
cardholder to pay off the entire balance if only the minimum monthly
payment is paid.
Second, the statement would report the total cost to the consumer of
only making the required minimum payments, with a breakdown of the
resulting principal and interest shares of the total cost.
Third, the statement would report the estimated monthly payments
required for the consumer to pay off the entire balance in a period of
12, 24 and 36 months.
This is important for the more than 100 million households with
revolving loan credit of nearly $1 trillion according to the Federal
Reserve, who have average credit card debt of $7,430--particularly
middle- and low-income families, who are carrying record amounts of
debt--both in absolute value and as a share of their total income--and
who often don't realize they are digging themselves further into debt
as they make their minimum monthly payments. With the average credit
card debt per card-holding household carrying a balance of $17,103,
some 49.7 million do not pay their balance in full every month. We need
to make sure there is simple and clear information for these families.
In 2007 alone, there were 5.2 billion credit card solicitations
mailed, a average of 36 per household. Just plain truth in disclosure
warrants this important change to ensure that any family fully
understands what is at stake.
I stand in support of both H.R. 627 and this amendment to it, which
will require the disclosure of information to consumers that will help
them to make more informed choices and to better plan their finances
and thus their futures.
Mr. PRICE of North Carolina. Mr. Chairman, I yield back my time.
The Acting CHAIR. The question is on the amendment offered by the
gentleman from North Carolina (Mr. Price).
The amendment was agreed to.
Amendment No. 13 Offered by Mr. Gutierrez
The Acting CHAIR. It is now in order to consider amendment No. 13
printed in House Report 111-92.
Mr. GUTIERREZ. Mr. Chairman, on behalf of the gentlewoman from
California (Mrs. Davis) I offer the amendment at the desk.
The Acting CHAIR. The Clerk will designate the amendment.
The text of the amendment is as follows:
Amendment No. 13 offered by Mr. Gutierrez:
Insert after section 127B(c) of the Truth in Lending Act
(as added by section 2(c) of the bill) the following new
subsection (and redesignate succeeding subsections
accordingly):
``(d) Advance Notice of Account Closure.--
``(1) In general.--In the case of any credit card account
under an open end consumer credit plan, a creditor may not
close such account unless the creditor provides a written
notice to the consumer at least 30 days before the closure
takes place, and which notifies the consumer--
``(A) of the reason the account is being closed;
``(B) of any recourse that the consumer may take to prevent
the account from being closed;
``(C) of any program under which the consumer may repay the
balance on the account over a period of time; and
``(D) that if the consumer's account is closed, it may have
an impact on the consumer's credit score.
``(2) Exception.--The requirements of paragraph (1) shall
not apply in the case of a consumer request that the creditor
close such account.''.
The Acting CHAIR. Pursuant to House Resolution 379, the gentleman
from Illinois (Mr. Gutierrez) and a Member opposed each will control 5
minutes.
The Chair recognizes the gentleman from Illinois.
Mr. GUTIERREZ. It's a pretty simple amendment. It would require that
credit card issuers notify credit cardholders 30 days before closing
their accounts, the reason that the account was closed. They put it in
writing; options to keep the account open; programs available to repay
the balance, and the resulting impact on their credit score that this
might have. It's a pretty simple amendment. It's very consumer-
oriented. It allows for more transparency between those that issue the
credit card and those that receive it.
I reserve the balance of my time.
Mr. HENSARLING. Mr. Chairman, I claim time in opposition.
The Acting CHAIR. The gentleman from Texas is recognized for 5
minutes.
Mr. HENSARLING. Mr. Chairman, I'm somewhat uncertain, frankly,
whether I am actually opposed to the underlying amendment. I think the
intention is good. I just hope there's not an unintended consequence
here. And so, if my friend from Illinois, the chairman of the
subcommittee, would yield for a question, my concern would be this: We
all know from our constituents how much identity theft is taking place
in our society. I, myself, at one time have been victimized by identity
theft; and many of our constituents have.
So if there is fraudulent activity, if identity theft is suspected,
it at least would appear to me, in a reading of the amendment, that the
credit card issuer would have to keep the account open for at least 30
days, and so I was concerned about its impact in trying to combat
identity theft. That was my reading of the amendment.
And I'd be happy to yield to the gentleman from Illinois just to see
if he could help explain how this would work.
Mr. GUTIERREZ. Well, let me just suggest the following: number one, I
understand the gentleman's concern. And I think the amendment is a
pretty good amendment, and I understand your concern.
I think we can kind of predict that you and I are probably going to
the conference report once we get this, should this bill be successful,
which, given precedent of last year, it looks very, very likely we're
going to pass this bill here today. I've worked with you, I think, very
well in the past, and obviously, I look forward to the coming years and
working with you. Why don't we work out that in conference to make sure
that that just doesn't happen and the consumer isn't harmed.
Mr. HENSARLING. Reclaiming my time, I certainly respect the gentleman
from Illinois (Mr. Gutierrez). We do have an excellent working
relationship. I don't know that this is a problem. I fear it may be a
problem. Given his commitment that we can work on this at our
conference, Mr. Chairman, I no longer oppose the amendment.
And I yield back the balance of my time.
Mr. GUTIERREZ. I yield to one of the sponsors of the bill, Mr. Carney
from Pennsylvania, 2 minutes.
Mr. CARNEY. Mr. Chairman, I'm very glad to be able to offer this
amendment with the gentlelady from California. It really is a
commonsense amendment, and I do want to address the gentleman from
Texas's concern that in the Truth in Lending Act it does protect banks
from being victim to fraudulent accounts being opened. It doesn't cover
that, but we will certainly work with the gentleman from Texas on
language that would make him feel better about what we're talking about
now.
Now, I've heard from a number of my constituents regarding credit
card companies closing accounts in good standing for no reason other
than inactivity. I'm sure many of us have constituents in the same
position.
Despite the fact that you can use your credit card on just about
anything anywhere, many people do that, but many people prefer to use
cash. The part of Pennsylvania where I live is not a young area and
it's not an urban area. We have traditional folks who like to use cash
and don't like to put a lot of credit on their cards. They use the card
for emergencies. They don't use it for sort of day-to-day expenses.
So not only were constituents and neighbors of mine surprised to be
losing their credit card privileges, but they were concerned over
potential harm to their otherwise great credit ratings due to card
companies' desire to wipe inactive accounts from their books.
This amendment would protect people who supposedly underutilize their
credit cards from forced closure of their accounts and negatively
impacting their credit scores. It requires credit card companies to
notify cardholders
[[Page H5032]]
at least 30 days in advance of an account closure. It also requires the
card companies to tell cardholders that their account closure could
adversely affect their credit rating. And it requires card companies to
give cardholders guidance on how to appeal the issuer's decision to
close the account. It's just a commonsense protection for cardholders.
That's all it really is.
And as I addressed earlier, the gentleman from Texas has some
concerns. We respect them, and as I mentioned, we're willing to work
with him on that.
But in the end, I encourage all my colleagues to support this
amendment.
{time} 1330
Mr. GUTIERREZ. Mr. Chairman, how much time do we have left on our
side?
The Acting CHAIR. The gentleman has 2 minutes remaining.
Mr. GUTIERREZ. I yield 2 minutes to the chief sponsor of the
legislation.
Mrs. DAVIS of California. Mr. Chairman, I appreciate the time, and I
certainly want to respond to my colleagues.
It's always possible to raise those kinds of concerns over fraud, and
this is not intended to do that on the face of it, but we're willing to
work with you, because the reality is that, if fraud is being
committed, then these kinds of agreements wouldn't hold anyway, and the
banks would certainly have a way of dealing with this.
The real concern here is letting consumers know what's going on with
their accounts. If they have been in an experience--and we know there
are many consumers who have been--where card accounts that are not
being used very often are closed and where they don't know about it,
then their credit scores are affected. That's one of those surprises
that comes along that people aren't expecting.
This is an attempt to be transparent about it and to give people,
really, the opportunity to be able to respond and to work out whatever
problem exists and to move on. So we appreciate the opportunity to put
this in what I think is some very important legislation.
Mr. Chairman, today Mr. Gutierrez, as my designee, offered a common
sense amendment to H.R. 627--The Credit Card Bill of Rights Act.
This amendment warns consumers of possible reductions to their credit
scores.
Currently, credit card companies are not required to notify a
consumer when they decide to close an account.
Often, consumers do not know that their accounts are being closed
until after the fact.
Because of the way credit scores are calculated, account closures can
lower a consumer's credit score, sometimes significantly.
A reduction in a consumer's credit score can hamper his or her
ability to buy a car or home, start a business, or pay for college.
Especially in today's tight credit market, a solid credit score is
more important than ever.
A large number of consumers have no idea that the mere closure of a
credit card can adversely impact their credit scores.
Imagine saving for a home only to discover your credit score is too
low for a mortgage because of an account closure.
Consumers do not get a chance to prepare and plan their finances
accordingly. This is an issue that affects all consumers and not just
the elderly retiree in San Diego who first brought this to my
attention.
It affects teachers, firefighters, doctors, and our men and women in
uniform.
I ask unanimous consent to enter into the Record a recent article in
the Wall Street Journal detailing this problem for consumers across the
country.
The amendment Mr. Gutierrez offered on my behalf would require credit
card companies to give consumers a 30-days advance notice that their
accounts are being closed.
Within this notice, the card issuer must also include:
The reason why the account is being closed;
Options the consumer has to keep the account open;
Programs available for the consumer to repay their account balance
over time;
And the fact that an account closure may impact the cardholder's
credit score.
This amendment is really about informing consumers so they are not
caught by surprise.
We believe that consumers have a right to know when their credit
scores may be lowered so they can plan their finances accordingly.
This amendment has been endorsed by a broad coalition of consumer
groups including the Center for Responsible Lending, Consumer
Federation of America, and U.S. PIRG.
I thank Congressman Carney for all the hard work he has put into this
amendment. It has been a pleasure working-With you and your office in
this effort.
I urge the adoption of this amendment.
[From the Wall Street Journal, Mar. 11, 2009]
Credit Card Issuers: Buy Something or Else!
(By Kelli B. Grant)
One of the biggest causes of the financial crisis was that
Americans were borrowing (and spending) more money than they
could afford to pay back.
So how are credit-card issuers reacting to consumers'
attempts to live a more financially responsible lifestyle?
They're threatening to cut their credit cards off if they
don't spend enough.
Loretta Maxwell of Troy, Mich., thought her credit score of
790 buffered her against most of the fallout of the credit
crunch. When Chase closed her $6,000-limit card in December
without warning after two years of inactivity, she called to
fight it. She was unsuccessful. ``If you're not using it,
they entice you to do so, and then the moment you don't spend
enough, they cut your limit,'' she says. (Chase says it is
standard practice is to review inactive accounts. ``Inactive
cards with large open credit lines present a real risk of
fraudulent use and large potential liabilities for Chase,''
says spokeswoman Stephanie Jacobson.)
Maxwell's experience is far from an isolated incident. Most
major issuers, including Chase, Bank of America, American
Express and Citibank have been slashing credit lines and
closing the accounts of those who don't spend on their card
regularly. While these issuers are required to notify you in
writing of an account closing, there's no requirement that
they do so in advance. Even when they do give early notice,
the only way a cardholder can stop their account from getting
shut down is to start spending again.
In December, Discover reported that it closed three million
accounts during 2008 due to inactivity, and plans to cull up
to two million more. A Discover spokeswoman says the issuer
is constantly reevaluating cardholder's credit and assessing
whether they have the most appropriate credit line and
product. Capital One is suspending accounts that have been
inactive for at least a year, warning account holders they
only have 60 days to redeem their rewards. ``Some of these
accounts had literally never been used,'' says spokeswoman
Pamela Girardo. A spokeswoman for Bank of America, meanwhile,
says the bad economy prompted it to close accounts with zero
balances that have been inactive for more than a year.
American Express spokeswoman Lisa Gonzalez says it
periodically reviews inactive accounts for cancellation.
Citibank did not respond to requests for comment.
From a business perspective, cutting off certain customers
is a smart financial move, says Sanjay Sakhrani, an analyst
with investment bank Keefe, Bruyette & Woods. Closing rarely-
used accounts lowers a card issuer's risk profile by keeping
their potential liabilities (i.e., the amount of credit
available they extend to cardholders) from outweighing
their assets. Inactive accounts also cost the issuer money
to maintain, without providing the benefit of income from
interest or merchant fees, he says.
For consumers, however, closing accounts can be
devastating--especially to their credit score. Your credit
utilization ratio the amount of your debt in relation to the
amount of your available credit--comprises 30% of your score,
says Craig Watts, a spokesman for Fair Isaac Corporation, the
company that calculates and issues the FICO credit score that
most lenders use. So when an account is closed, you have less
credit available to you--and the ratio immediately jumps
higher. A person with a solid credit score of 720 or so,
whose utilization ratio jumps from 35% to 75% after one of
their accounts is closed is likely see their score drop by
``several dozen points,'' to somewhere in the 600s, he says.
That's a far cry from the 760 (or higher) consumers need to
get the best rates from lenders.
One thing that somewhat softens the blow is that FICO
factors in closed accounts when calculating the longevity of
your credit history, which accounts for 15% of your score.
While lenders may make a note on your report indicating
whether the account was closed by them or you, the
information isn't used in the scoring formula, says Watts.
Ironically, an excellent credit score can actually serve as
more of a bulls-eye than a shield, says Dennis Moroney, a
research director and senior analyst for consulting firm
Tower Group. He says banks figure they can limit cardholder
backlash by targeting consumers with few debts and plenty of
other accounts. That way, a closed account won't have as much
of a detrimental effect on their creditworthiness.
Even years of loyalty and regular spending won't spare some
cardholders. David Good of Houston, used to be devoted to
American Express, with which he had two credit cards: an
unlimited charge account and a $7,500 revolving account. Yet
a solid credit score, eight years of on-time payments and
fairly frequent purchases on the cards--including more than
$100,000 last year alone--weren't enough to save his
accounts. In December, Good received a written notice that
the issuer had closed both due to ``low activity in the past
six months.'' ``I was shocked,'' he says. ``They lost my
trust, totally.'' (American Express declined to comment on
Good's or any other individual's accounts.)
New Yorker Veronica Eady Famira was vacationing in Germany
when she discovered that her $1,500-limit Delta SkyMiles card
from American Express had been shut down. ``I must have spent
$300 in cellphone charges
[[Page H5033]]
calling banks,'' she says. ``I was pretty stranded.'' Adding
insult to injury, Famira had just earned a free companion
ticket on the card valued at up to $400 for a domestic
flight--now she can't redeem the ticket.
Mr. GUTIERREZ. Mr. Chairman, we yield back the balance of our time.
The Acting CHAIR. The question is on the amendment offered by the
gentleman from Illinois (Mr. Gutierrez).
The amendment was agreed to.
Amendment No. 14 Offered by Mr. Perriello
The Acting CHAIR. It is now in order to consider amendment No. 14
printed in House Report 111-92.
Mr. PERRIELLO. Mr. Chairman, I have an amendment at the desk.
The Acting CHAIR. The Clerk will designate the amendment.
The text of the amendment is as follows:
Amendment No. 14 offered by Mr. Perriello:
In subsection (c) of section 127B of the Truth in Lending
Act (as added by section 2(c) of the bill) insert after
paragraph (2) the following new paragraph:
(3) Minimum term for promotional rates.--In the case of a
promotional rate, no written notice under paragraph (1) of an
increase in any annual percentage rate of interest on any
credit card account under an open end consumer credit plan
shall be effective before the end of a 6-month period
beginning from the date the promotional rate takes effect.
The Acting CHAIR. Pursuant to House Resolution 379, the gentleman
from Virginia (Mr. Perriello) and a Member opposed each will control 5
minutes.
The Chair recognizes the gentleman from Virginia.
Mr. PERRIELLO. Mr. Chairman, I yield myself such time as I may
consume.
I rise today in support of my amendment requiring credit card
companies to have a 6-month minimum period for promotional rates.
Credit card companies should not have the right to take advantage of
consumers with their confusing policies. Today, the voices of
accountability and common sense have a chance to fight back against
many of the problems that got us into this economic mess in the first
place. If you can't sell a product without tricks and traps, this is
the kind of place where consumer protection must come in to ensure a
well-functioning free market.
This is a simple amendment that represents the common sense that is
greatly needed. Credit card companies should not be allowed to trick
consumers around with short-term promotional rates that confuse them. A
6-month minimum is a reasonable period of time to expect these so-
called ``teaser rates'' to last.
It also includes a 45-day notice before any rate change is
implemented. Middle class Americans are facing difficult economic
times, and many factors have caused the current economic crisis, but
soaring debt is near the top of that list.
One group particularly targeted by these rates is that of young
people, our students, who get caught in a cycle of debt early in life.
Instead of using those first earning years as a time to save up and to
be able to afford a down payment on a home, we see people caught in a
cycle of credit card debt, then taking a zero-interest loan or a zero
down payment on a home, and that cycle of debt continues.
I believe this is a day where we can start to fight back for Main
Street over Wall Street and put common sense over greed to protect the
American family.
Mr. Chairman, I reserve the balance of my time.
Mr. HENSARLING. Mr. Chairman, I rise to claim time in opposition.
The Acting CHAIR. The gentleman from Texas is recognized for 5
minutes.
Mr. HENSARLING. I yield myself such time as I may consume.
Mr. Chairman, I listened carefully to the gentleman, and I appreciate
the intent of his particular amendment, but I fear, again, that this
will be one more in a series of amendments that may have unintended
consequences.
I heard the gentleman, as well as other speakers on the other side of
the aisle, say they want to prevent tricks by the credit card
companies. I think that is one of the few items, besides renaming a
post office, that could receive a unanimous vote in this institution.
Out of, I believe, 1,200 pages of Federal Reserve regulations where
they spent 3 years studying the issues, we will have disclosure under
the Federal Reserve regulations that will prevent such tricks unless
one defines the actual period of a teaser rate to be a trick. I believe
a consumer can understand the difference between 1 month, 6 months, 6
years, and 12 years. Let the consumer choose.
Let me tell you what I believe the practical result of this amendment
will be. Particularly those who may have a more checkered credit past,
consumers, instead of having the ability to have a teaser rate--and I'm
just using numbers for an example--at 8 percent for 3 months that then
goes up to 15 percent for 9 months--they'll just end up having to pay
15 percent for the whole 12 months. They'll lose consumer choice.
They'll lose that opportunity.
Now, some maintain that there are some concepts--and I've heard it
said from friends on the other side of the aisle--certain aspects of
their credit card agreements that consumers just can't understand.
They're just too difficult to understand. Again, I congratulate the
gentlelady from New York, yet again, for having a disclosure title, I
believe, very roughly equivalent to that of the Federal Reserve's. This
is a problem that can be solved with disclosure.
Empower the consumers. Don't take away their options. Empower the
consumers with effective disclosure, and let them choose in a
competitive marketplace. Let there be competition. Again, today, I can
understand how consumers are confused. These forms are so long. They're
written in legalese. It's easy to hide it. The answer is effective
disclosure. The answer is not an arbitrary date on how long a teaser
rate ought to be.
What you are doing is protecting the consumer out of having any
opportunity of having a teaser rate. A teaser rate, when averaged with
the other rate, again gives you an average of what the interest rate
would be for a year. If you pass this, there is going to be a universe
of consumers who are going to end up paying more, paying more on
average for their credit than they otherwise would. So I urge rejection
of the amendment.
I reserve the balance of my time.
Mr. PERRIELLO. Mr. Chairman, I am happy to yield 2 minutes to the
gentleman from Massachusetts (Mr. Frank).
Mr. FRANK of Massachusetts. Well, I heard my friend from Texas with
mixed emotions. I liked the part of it where he said to trust the
individual to make his or her economic decisions and to not interfere,
and I hope when the bill I am sponsoring to repeal the ban on Internet
gambling comes up that that sentiment doesn't die, because some people
don't like the choices people would make. I would like to empower
consumers. Congress passed a law that said, if you want to gamble with
your own money on the Internet and you're 53 years old, you can't do
it. So I welcome this kind of consumer choice, but that's, I think, a
more clear-cut choice than this one.
The gentleman from Texas confidently says that, if you have this,
there will be no teaser rates for a lot of people. I do not think there
is any basis on which he can say that.
I am reminded of what Lord Melbourne said about Macaulay in the 19th
century: ``I wish I could be as sure of anything as he is of
everything.''
There is no basis for saying there will be no more teaser rates. As a
matter of fact, a rate that only lasts 2 months or 3 months is likely
to be a confusing thing to people, and he says that a consumer can
tell. There still will be disclosure, but it will still come with a
blizzard, and it will still come in ways that may not be clear to
people.
The fact is that a 6-month minimum is a way to make sure that the
product being offered is a sensible and thoughtful product that will
not mislead some people. The fact is that not all consumers are of
equal education, of equal ability to discriminate, of equal financial
literacy. Yes, I think we should work to the point where people are as
well educated as they should be, but that's not the case now.
You have to ask yourself, Mr. Chairman: Why would someone offer a 2-
month teaser rate other than to try and bait and switch people into a
higher rate?
I congratulate the gentleman from Virginia. This is a very thoughtful
amendment. He has been working with the Obama administration. It comes
with their strong support, and he is to be congratulated for an
important consumer protection motion.
[[Page H5034]]
Mr. HENSARLING. Mr. Chairman, one, what I believed I said in my
comment is that, for some universe of people, they would lose their
teaser rates under this legislation. I listened to the chairman spend a
fair amount of his time debating Internet gambling, which I do not
believe is on the floor at this time; but if the chairman is so
supportive of having consumer choice, I don't understand why we just
spent a day and a half in markup in his committee taking away
consumers' choice in the mortgage market. So we will continue to have
this debate throughout.
Again, it's a simple argument. I believe that we can have effective
disclosure and can allow consumers to make choices. If they're not
allowed, if this type of arbitrary date is imposed, some universe of
borrowers will probably lose their teaser rates and will effectively
end up paying more, which will restrict their options. Again, I urge
rejection of the amendment.
I reserve the balance of my time.
Mr. PERRIELLO. I would like to inquire if the gentleman has
additional speakers.
Mr. HENSARLING. No.
Mr. PERRIELLO. I reserve the balance of my time.
Mr. HENSARLING. Mr. Chairman, may I inquire as to who has the right
to close.
The Acting CHAIR. The gentleman from Texas has the right to close.
Mr. HENSARLING. In this case, I continue to reserve.
Mr. PERRIELLO. Mr. Chairman, I ask for my colleagues to support this
amendment.
I yield back the balance of my time.
Mr. HENSARLING. Mr. Chairman, I urge rejection of the amendment, and
I yield back the balance of my time.
The Acting CHAIR. The question is on the amendment offered by the
gentleman from Virginia (Mr. Perriello).
The amendment was agreed to.
Amendment No. 15 Offered by Mr. Schauer
The Acting CHAIR. It is now in order to consider amendment No. 15
printed in House Report 111-92.
Mr. SCHAUER. Mr. Chairman, I have an amendment at the desk.
The Acting CHAIR. The Clerk will designate the amendment.
The text of the amendment is as follows:
Amendment No. 15 offered by Mr. Schauer:
After section 8, insert the following new section (and
redesignate the subsequent sections accordingly):
SEC. 9. POSTING INFORMATION ON THE INTERNET.
Section 122 of the Truth in Lending Act (U.S.C. 1632) is
amended by adding at the end the following new subsection:
``(d) Internet Posting of Credit Card Agreements.--
``(1) Posting agreements.--A creditor shall establish and
maintain an Internet site on which the creditor will post the
written agreement between the creditor and the consumer for
each open-end consumer credit plan not secured by a dwelling
that has a credit card feature.
``(2) Providing copy of contracts to the board.--A creditor
shall provide to the Board in electronic format, the consumer
credit card agreements that the creditor publishes on the
creditor's Internet site.
``(3) Record repository.--The Board shall establish and
maintain on its publically available Internet site a central
repository of the consumer credit card agreements received
from the creditors pursuant to this subsection and such
agreements shall be easily accessible and retrievable.
``(4) Exception.--Paragraphs (1) and (2) shall not apply to
individually negotiated changes to contractual terms, such as
individually-modified workouts or renegotiations of amounts
owed by a consumer under an open end consumer credit plan.
``(5) Regulations.--The Board, in consultation with the
other agencies described in section 108 and the Federal Trade
Commission, may prescribe regulations to implement this
subsection, including--
``(A) specifying the format for posting the agreements on
the creditor's Internet site; and
``(B) establishing exceptions to paragraphs (1) and (2) in
cases where the administrative burden outweighs the benefit
of increased transparency, such as where a credit card plan
has a de minimis number of consumer account holders''.
The Acting CHAIR. Pursuant to House Resolution 379, the gentleman
from Michigan (Mr. Schauer) and a Member opposed each will control 5
minutes.
The Chair recognizes the gentleman from Michigan.
Mr. SCHAUER. I yield myself 2 minutes.
Mr. Chairman, first, let me congratulate my distinguished colleague
from New York for her leadership on bringing forward this important and
timely bill. I'm proud to be a cosponsor of the credit cardholders'
bill of rights.
I've heard from many of my constituents in Michigan, as I'm certain
all of you have heard from your constituents, who have found themselves
being misled by the credit card companies and being subjected to
usurious rates. Americans are hurting, Michiganders especially, and
they need our help. This bill is a critical step in providing that
relief. Mr. Chairman, my amendment is a simple, two-part amendment that
will help consumers make good choices when they get a credit card.
First, it requires credit card companies to post their agreement
disclosures on their Web sites. Second, it requires a company to
transmit that information to the Federal Reserve Board so that the
board can compile those agreements and post them on the board's Web
site. Together, these provisions provide important disclosure and
transparency to the public, and they are an important resource for
consumers so that they can easily be informed of tricks and traps that
may exist within their credit card contracts or so that they can shop
for the best possible deal for credit cards.
The goal is to provide consumers with direct public information and
transparency regarding the interest rates that companies charge for
their credit cards. This will allow one-stop shopping for good, fair
rates.
Mr. Chairman, our people are hurting. Unemployment in my State is
approaching 13 percent, and it's much higher than that in parts of my
district. My amendment is a simple, straightforward step, and I ask for
your support.
I reserve the balance of my time.
Mr. HENSARLING. Mr. Chairman, I claim time in opposition to the
amendment.
The Acting CHAIR. The gentleman from Texas is recognized for 5
minutes.
Mr. HENSARLING. I yield myself such time as I may consume.
Mr. Chairman, I'm not completely certain that I actually oppose the
amendment. I do have a couple of concerns.
One, I want to congratulate the gentleman for the thrust of his
amendment, and indeed, we want to ensure that our consumers are
empowered and that our consumers have proper disclosure.
There are a number of reasons why consumers do not understand the
disclosure forms that they have today, one of which is there are
misleading and deceptive practices by credit card companies. We all
agree on that.
Another reason, though, is that, day after day and with the noblest
of intentions, we mandate more disclosures. I'm just somewhat fearful--
and not that this is not necessarily good information--that the
combined impact will turn what otherwise might be a 2- to 3-page
disclosure that a consumer might actually take the time to read into a
30- to 45-page behemoth that no one will take the time to read.
Again, I congratulate the gentleman for his intent and for his
thrust. I'm not going to oppose the amendment, but I do want to
articulate the concern again that we really want to emphasize that the
most important aspects of a consumer's relationship with his credit
card company are disclosed so that we can get focused there. In the
average mortgage disclosure, there is so much disclosure, that people
see a dizzying array of documents and pay attention to none of them.
{time} 1345
I have always been an advocate for the succinct, effective disclosure
written in plain English, not necessarily voluminous disclosure written
in legalese.
I would also say that particularly for my friends on the other side
of the aisle that have been extolling the virtues of the Federal
Reserve throughout this debate, that through their rule-making, I
believe that they have already addressed this issue. They did spend
more time studying it than we did. I personally don't know. I didn't
see the evidence of how much demand there is for consumers for this
information. I don't know the answer to that.
One other aspect I would bring up besides the fact that we need to
ensure that we're having effective disclosure. I am not indifferent as
to the increased
[[Page H5035]]
regulatory burden on our small community banks. Two Congresses ago, I
had the opportunity to be the lead sponsor and write regulatory relief
legislation for our small community banks. We have about half of what
we had, I believe, 20 years ago. And so I am always a little concerned,
too, in making sure that the benefits of an amendment or legislation
are worth the cost. I don't want to continue to see more community
banks get out of the credit card business because it's an extra cost
here, it's an extra cost there. They don't have the personnel, and I
just always want to be sensitive to the fact that I do not want to
reduce competition down.
I don't see the distinguished chairman of the full committee on the
floor today at this moment, but I know that he often jokes about that
one day we may change our name to the ``bank committee'' because there
will only be one bank left in America.
So, again, I just want to show sensitivity, and I don't know if there
is any kind of program for our smaller banks. I know on a number of
pieces of legislation there are exclusions for small businesses. I
don't see that in the language here. And again, I am not going to
oppose this particular amendment, but I did want to articulate concerns
that I hope will be taken to heart by the majority, things that they
could consider as this goes into conference.
At this moment, I will reserve the balance of my time.
Mr. SCHAUER. I appreciate the comments from the gentleman from Texas
in support of the amendment. My amendment doesn't change the content of
the disclosure, only its dissemination through a Web site that the
Federal Reserve Board would collect and post those disclosures.
Mr. Chairman, I am happy to yield 1 minute to the gentleman from
Illinois (Mr. Gutierrez).
Mr. GUTIERREZ. First of all, I want to thank the gentleman from
Michigan for introducing this amendment. I think, first of all,
probably the most junior member of my staff--they are all really
bright--but the most recent graduate from college can probably go on
the computer and somehow transcribe a document because the consumers--I
don't want anybody to be led to believe that somehow this bill of
rights isn't going to give the consumers the agreement. They are going
to have every right to the agreement, and the banks are going to have
to print the agreements and give it to people, except the agreements
are going to be easier to read and understand. So I think a junior
member can put that on a computer and Web site.
Having said that, again, Mr. Hensarling--I hope that I have done a
good enough job today, and I know he's always done a good enough job on
his side, and we will take a look at that. If there is some onerous
cost, we will take a look at that. But I have a funny feeling that
there is a template out there that's going to be given to these smaller
institutions. And I thank the gentleman for not opposing the amendment.
Mr. HENSARLING. Mr. Chairman, who has the right to close?
The Acting CHAIR. The gentleman from Texas has the right to close.
Mr. HENSARLING. Then I will continue to reserve.
Mr. SCHAUER. Mr. Chairman, I ask that my colleagues support this
amendment.
I yield back my time.
Mr. HENSARLING. Mr. Chairman, I yield back the balance of my time.
The Acting CHAIR. The question is on the amendment offered by the
gentleman from Michigan (Mr. Schauer).
The amendment was agreed to.
Amendment No. 16 Offered by Mr. Teague
The Acting CHAIR. It is now in order to consider amendment No. 16
printed in House Report 111-92.
Mr. TEAGUE. Mr. Chairman, I have an amendment at the desk.
The Acting CHAIR. The Clerk will designate the amendment.
The text of the amendment is as follows:
Amendment No. 16 offered by Mr. Teague:
After section 8, insert the following new section (and
redesignate subsequent sections accordingly):
SEC. 9. REGULATIONS RELATING TO ACTIVE DUTY MILITARY
CONSUMERS AND RECENTLY DISABLED VETERANS.
Section 127B of the Truth in Lending Act is amended by
inserting after subsection (p) (as added by section 6) the
following new subsection:
``(q) Regulations Relating to Active Duty Military
Consumers and Recently Disabled Veterans.--In the case of any
credit card account, under an open end consumer credit plan,
held by any veteran receiving compensation for a service-
connected disability (as such terms are defined in section
101 of title 38, United States Code) that occurred less than
2 years before or any active duty military consumer (as
defined in section 603(q)(2) of this Act) , the Board shall
prescribe regulations that prohibits the creditor with
respect to such account from making adverse reports to any
consumer reporting agency with respect while the consumer
maintains status as such a veteran or as an active duty
military consumer.''.
The Acting CHAIR. Pursuant to House Resolution 379, the gentleman
from New Mexico (Mr. Teague) and a Member opposed each will control 5
minutes.
The Chair recognizes the gentleman from New Mexico.
Mr. TEAGUE. Mr. Chairman, I yield myself 2 minutes.
Mr. Chairman, I rise today to offer an amendment along with my
friends, Congressmen Nye, Kissell and Boccieri, that has three
principal attributes. One is it's common sense. It does what is right
and it helps out our Nation's veterans. Specifically, the amendment
stops credit card companies from bringing down the credit scores of
deployed soldiers and disabled veterans during the first 2 years of
their disability.
Mr. Chairman, one of the time-honored commitments we make to our
veterans is after they do the dangerous work of protecting our national
security, we, as a country, ensure their economic security. When a
soldier is fighting in the mountains of Afghanistan or the deserts of
Iraq, he or she does not have access to regular mail service nor the
ability to tend to the everyday financial pressures of home.
Likewise, when an injured veteran is adjusting to life with his or
her disability, there is often a period of economic vulnerability where
the costs pile up and sometimes you just don't get to every last letter
in the mail.
When veterans return home, they should do so with the confidence that
their credit history allows them to open a business, buy a house or a
truck. If they were late on some payments while serving their country
or recovering from a severe injury, that shouldn't prevent them from
pursuing the American Dream. No commercial credit rating agency can be
equipped to account for the intangibles of combat service and
recovering from service-connected injuries.
Economic opportunity for veterans should not be a question of
mistakes that they may have made during deployment or recovery. It
should be a question of their service.
I urge my colleagues to pass this amendment.
I reserve the balance of my time.
Mr. HENSARLING. Mr. Chairman, I rise to claim time in opposition.
The Acting CHAIR. The gentleman from Texas is recognized for 5
minutes.
Mr. HENSARLING. Mr. Chairman, I may be reluctantly opposed to the
gentleman's amendment.
First, let me congratulate the gentleman from New Mexico. I have said
other times that people had a noble purpose in their amendment. Of all
amendments I have seen, this certainly has the most noble purpose, the
most noble intent. No one who dons our Nation's uniform and fights for
freedom, protects America's security ought to somehow be harmed because
they missed a payment while they were taking on their Nation's duty. I
certainly agree with the intent of the gentleman's legislation.
I have a couple of concerns, though, because I believe that this
would be the first time that we are asking credit card bureaus to hide
information.
I am just curious. Is there not another way to protect our brave men
and women in uniform than setting the precedent of keeping accurate
information away from a credit file which allows people to access
credit in the first place? I am not an expert on it, but others who
serve on the committee have informed me that this situation has been
addressed under the Civil Relief Act. I know that military, Active Duty
military, can append to their credit file that they are indeed in
harm's way.
I would be happy to work with the gentleman for a program in DOD that
would help ensure, again, that whatever type of resources are needed to
ensure that people do not default on their
[[Page H5036]]
credit obligations while they are in harm's way, that's something I
would want to support. I would want to go to the Appropriations
Committee and ask them to appropriate funds to assure that this is
done.
Clearly, we want to be sensitive to our Active Duty personnel. It's
the most important thing we can do in this institution is protect the
Nation from all enemies, foreign and domestic.
So I want to achieve the gentleman's goal, but I wonder if it might
not have the unintended consequence of, perhaps, making credit even
less available to our military personnel if, for some reason, the
creditor community started believing that they were no longer receiving
accurate information.
So I don't have a solution at my hand, and I admit that. But I do
continue to be concerned that there may be unintended consequences
here.
I reserve the balance of my time.
Mr. TEAGUE. Mr. Chairman, I yield 1\1/2\ minutes to my friend from
Ohio (Mr. Boccieri).
(Mr. BOCCIERI asked and was given permission to revise and extend his
remarks.)
Mr. BOCCIERI. They are fighting for us; now we have to fight for
them. Every day, thousands of brave Americans are asked to leave the
comfort and safety of their homes and families to fight for our freedom
abroad. Oftentimes, those soldiers leave behind families who are
surviving on credit cards to put food on the table or to clothe their
kids as they send them off to school.
Some of those brave soldiers are deployed to the Middle East and then
they are deployed to a forward-operating base. As a C-130 pilot, I
delivered mail to those austere and sometimes remote locations. No, our
soldiers in the battle every day don't have time to affix a stamp and
send off a bill or a statement, their credit card bills, back to
America. But while those soldiers are dodging bullets and IEDs and
RPGs, they shouldn't be concerned about whether they sent their Visa
bill on time. Frankly, they are under enough pressure. I know the
stresses of a battlefield, and our soldiers shouldn't have to fight the
credit card companies when they return because they were defending our
country when their bill was due.
So I ask you, we've heard a lot about how this bill and amendments
could create unintended consequences. Are we going to allow our
soldiers and our brave men and women serving in our Nation's uniform to
be victims of unintended consequences because they are overseas
fighting?
The industry should be proud to stand by the soldiers and veterans
who defend their ability to operate in a safe and secure environment
led by a freely elected government. The industry should be willing to
take the extra step, go the extra mile to show leniency to the military
members who put their lives on the line.
Mr. HENSARLING. Mr. Chairman, how much time do I have remaining?
The Acting CHAIR. The gentleman has 3 minutes remaining.
Mr. HENSARLING. I will continue to reserve.
Mr. TEAGUE. Mr. Chairman, I yield 1\1/2\ minutes to my friend from
Virginia (Mr. Nye).
Mr. NYE. Mr. Chairman, I would like to thank my colleague from New
Mexico for his hard work on this amendment and for yielding.
Earlier this month, I had the opportunity to visit two forward-
operating bases in the eastern part of Afghanistan, and it's true our
troops today can keep in touch with home more easily than ever before.
But the reality of patrolling the border along Pakistan means that
sometimes payment dates will be missed.
Quite frankly, our troops deployed overseas have more important
things to do than worry about a credit score. Their only concern should
be to complete their missions and come home safely.
The same is true for injured veterans. As service-disabled veterans
work to readjust to civilian life, they often face serious challenges
finding a job, going through therapy, and working to recover from their
injuries. We should do everything in our power to help them recover and
rebuild. That's what this amendment will do.
I urge my colleagues to join me in supporting this amendment and
supporting our troops overseas and our injured veterans back home.
{time} 1400
Mr. HENSARLING. Mr. Chairman, I was listening carefully to the
previous speakers. And again, I could not agree with them more in
sharing their desire to ensure that this is not a problem. No one on
Active Duty should be worrying about paying for their credit card
bills. But I do continue to ask the question, is this the single best
remedy?
Now, I'm not sure that any credit card company in America would be so
stupid as to go and consciously ping somebody who is fighting for
freedom in Afghanistan or Iraq. Wait until the local newspaper or local
television station finds out about that. I would say some PR department
would be working overtime.
But again, the thing that disturbs me here--and I want to solve the
problem. Again, I admit, I am not an expert on what resources may be
available at the Pentagon. I don't know if there couldn't be somehow
automatic payment through the paycheck. If we need to set up money to
loan our soldiers to ensure their bills are paid when they are
overseas, I would be happy to support that.
But in some respects, you are asking credit bureaus to, in some
respects, deceive creditors because they have information and you are
telling them you are not allowed to give accurate information. Now, I
don't want them to act adversely, but the precedent of essentially
saying that you can now put misleading information into the market
disturbs me greatly. I just would hope that there would be an
alternative solution than this particular amendment, again, with the
noblest of intentions.
I reserve the balance of my time.
Mr. TEAGUE. My concern is that penalizing veterans for missing
payments while they are in combat or recovering from an injury is not
an accurate way of determining their creditworthiness. However, I do
look forward to working in conference to address some of these valid
concerns.
The amendment requires the Federal Reserve to write the rules that
accomplish the goals of this amendment, and we will work closely with
the Fed.
Once again, Mr. Chairman, I encourage all of my colleagues to vote
for this amendment.
Mr. Chairman, I yield back the balance of my time.
Mr. HENSARLING. Again, I want to congratulate my friend from New
Mexico and his leadership on this issue.
This is absolutely, positively, unequivocally something that the
Federal Reserve has to look into. I don't care if it affects only one
soldier, sailor or airman in the entire Nation, this problem must be
solved.
I continue to have reservations on this particular solution and its
potential unintended consequences. I will most reluctantly urge a
``no'' vote at this time and hopefully have a commitment, particularly
those who serve on our Armed Services Committee and our Appropriations
Committee, to maybe find out if there is a less onerous way to treat
what is a very, very serious problem.
I yield back the balance of my time.
The Acting CHAIR. The question is on the amendment offered by the
gentleman from New Mexico (Mr. Teague).
The amendment was agreed to.
Amendment No. 17 Offered by Mr. Schock
The Acting CHAIR (Mr. Serrano). It is now in order to consider
amendment No. 17 printed in House Report 111-92.
Mr. SCHOCK. Mr. Chairman, I have an amendment at the desk.
The Acting CHAIR. The Clerk will designate the amendment.
The text of the amendment is as follows:
Amendment No. 17 Offered by Mr. Schock:
In the subsection heading for section 3(d), strike
``Before'' and insert ``After''.
In the subsection heading of subsection (h) of section 127B
of the Truth in Lending Act (as added by section 3(d)),
strike ``Before'' and insert ``After''.
In paragraph (1) of section 127B(h) of the Truth in Lending
Act (as added by section 3(d))--
(1) strike ``may not furnish any information to'' and
insert ``shall remove any information furnished to''; and
(2) strike ``until the credit card has been used or
activated by the consumer''and insert ``if the consumer has
not used or activated the account and the consumer contacts
the creditor within 45 days of the establishment of the
account to close the account''.
[[Page H5037]]
The Acting CHAIR. Pursuant to House Resolution 379, the gentleman
from Illinois (Mr. Schock) and a Member opposed each will control 5
minutes.
The Chair now recognizes the gentleman from Illinois.
Mr. SCHOCK. Mr. Chairman, I yield myself such time as I may consume.
Mr. Chairman, the amendment I offer today is really targeted at
reducing identity theft and ensuring that consumers have the
appropriate information they need to make themselves aware of
inappropriate activity on their accounts that may be opened in their
name.
As the current legislation stands, it leaves inactivated credit cards
off of credit reporting altogether. The legislation would allow a
potential identity thief to apply for and obtain numerous credit cards
in someone else's name, accruing massive lines of credit, all with the
intention of opening each credit card at once and simultaneously
spending massive amounts of that victim's money and then disappearing,
as often is the case, which ruins the victim's credit history and
oftentimes costs the victim thousands of dollars.
My amendment ensures consumers are aware of credit activity made in
their name by removing the requirement that open lines of credit are
not reported to the credit bureaus until the issued credit card is
activated.
Now, identity theft is a real problem. As an individual who has had
my identity stolen, I can tell you that it is also a very costly
problem. Eight million Americans were victims of identity theft in
2005, and over 2 million of those 8 million victims were victims
because new accounts were opened in their names that they were not made
aware of.
The Federal Trade Commission also states that a quarter of those
victims' problems were exacerbated because they were not made aware of
the problems for over 6 months. The underlying legislation will only
exacerbate that without this amendment.
The Federal Trade Commission goes on in the report that they
encourage consumers to stay vigilant in protecting their identity
through two ways; one is monitoring accounts that you didn't open and
debts on your accounts that you can't explain. Well, Mr. Chairman, my
amendment does exactly that by ensuring consumers continue to have the
information about these accounts that would otherwise have been applied
in their name but up until this point would not be noted on their
credit account. Under the 2003 Fair Credit Reporting Act passed by
Congress, consumers are allowed this information free of charge. And
with the amendment I offer here today, they will be given that
information in advance of any adverse credit effects that a potential
identity thief could be trying.
Mr. Chairman, I urge a ``yes'' vote, and I reserve the balance of my
time.
Mr. GUTIERREZ. Mr. Chairman, I rise to claim the time in opposition.
The Acting CHAIR. The gentleman from Illinois is recognized for 5
minutes.
Mr. GUTIERREZ. Mr. Chairman, I yield myself 2 minutes.
The bill prohibits a creditor from providing information about a new
credit card to consumer reporting until the consumer uses or activates
the card. I think the intention is excellent. I don't know that you are
going to reach it through this amendment.
I am going to look forward to speaking to the gentleman. And as the
chairman of the Subcommittee on Financial Institutions, I look forward
to working with him to make sure that we actually reach your goal. I
think credit card companies should be able to allow that information to
be removed. Moreover, the reporting agencies should remove that
information, and it should be done quickly and swiftly, and we should
look at measures to do that.
I am not going to oppose or ask people to oppose this particular
amendment here this afternoon. I just want to share with the gentleman
that I am going to vote ``yes'' on it--and hopefully we won't have a
recorded vote and it will become part of the bill. We can then work on
it. And if we can't, I would suggest to the gentleman that we sit down
and figure out a way to get there, just in case I'm wrong, you're
right; you're wrong, I'm right. We should continue this conversation.
I reserve the balance of my time.
Mr. SCHOCK. I urge passage, Mr. Chairman, and I yield back the
balance of my time.
Mr. GUTIERREZ. I yield 2 minutes to the gentlelady from New York,
Carolyn Maloney.
Mrs. MALONEY. I thank the gentleman for yielding.
Mr. Chairman, I am generally in support of what my colleague from
Illinois is attempting to do, but I do have concerns that too few
consumers would take advantage of this provision or even know that it
was available to them. I am going to be supporting your amendment, but
I would like to work with you in further refining it.
I know the main concern that has been raised about this provision has
focused on preventing fraud. And I fully support efforts to prevent
fraud, and I am willing to work with you going forward to ensure that
consumers know of their right to reject the card and have this
information removed from the credit report.
I would also like to take this time to explain why this provision was
added to the bill and why I believe it is necessary in one form or
another.
Right now, consumers generally do not know the full terms and
conditions of their credit card until they have been issued the card.
And once a card has been issued, the card is reported on the consumer's
credit report, regardless of whether the consumer uses the card or not.
The bill would allow an issuer to report a consumer's application for a
credit card, but would not allow an issuer to report the approval of
the credit card to the credit bureaus until the card has been activated
or used.
Consumers should not have open lines of credit listed on their credit
report if they have no intention of ever using the card. And while I
appreciate the gentleman's amendment and will maintain this going
forward, I just want to ensure consumers receive adequate disclosures
relating to this. And so I will be supporting your amendment, and we
can help work on further disclosures.
Mr. GUTIERREZ. Mr. Chairman, I yield back the balance of my time.
The Acting CHAIR. The question is on the amendment offered by the
gentleman from Illinois (Mr. Schock).
The amendment was agreed to.
Announcement by the Acting Chair
The Acting CHAIR. Pursuant to clause 6 of rule XVIII, proceedings
will now resume on those amendments printed in House Report 111-92 on
which further proceedings were postponed, in the following order:
Amendment No. 3 by Ms. Slaughter of New York.
Amendment No. 8 by Mrs. Maloney of New York.
The Chair will reduce to 5 minutes the time for any electronic vote
after the first vote in this series.
Amendment No. 3 Offered by Ms. Slaughter
The Acting CHAIR. The unfinished business is the demand for a
recorded vote on the amendment offered by the gentlewoman from New York
(Ms. Slaughter) on which further proceedings were postponed and on
which the ayes prevailed by voice vote.
The Clerk will redesignate the amendment.
The Clerk redesignated the amendment.
Recorded Vote
The Acting CHAIR. A recorded vote has been demanded.
A recorded vote was ordered.
The vote was taken by electronic device, and there were--ayes 276,
noes 154, not voting 9, as follows:
[Roll No. 225]
AYES--276
Abercrombie
Ackerman
Adler (NJ)
Andrews
Arcuri
Baca
Baird
Baldwin
Barrow
Barton (TX)
Becerra
Berkley
Berman
Bishop (GA)
Bishop (NY)
Blumenauer
Boccieri
Bono Mack
Boren
Boswell
Boucher
Brady (PA)
Braley (IA)
Brown (SC)
Brown, Corrine
Brown-Waite, Ginny
Buchanan
Butterfield
Buyer
Camp
Cao
Capito
Capps
Capuano
Cardoza
Carnahan
Carney
Carson (IN)
Castor (FL)
Chandler
Christensen
Clarke
Clay
Cleaver
Clyburn
Cohen
Cole
Connolly (VA)
Conyers
Cooper
Costa
Costello
Courtney
Crenshaw
Crowley
Cuellar
Cummings
Dahlkemper
Davis (AL)
Davis (CA)
Davis (IL)
Davis (TN)
Deal (GA)
DeFazio
DeGette
Delahunt
DeLauro
Dent
[[Page H5038]]
Dicks
Dingell
Donnelly (IN)
Doyle
Driehaus
Duncan
Edwards (MD)
Ehlers
Ellison
Ellsworth
Engel
Eshoo
Etheridge
Faleomavaega
Farr
Fattah
Filner
Fleming
Forbes
Fortenberry
Frank (MA)
Fudge
Gerlach
Gingrey (GA)
Gohmert
Gonzalez
Gordon (TN)
Grayson
Green, Al
Green, Gene
Grijalva
Guthrie
Gutierrez
Hall (NY)
Halvorson
Hare
Harman
Heinrich
Higgins
Hill
Hinchey
Hinojosa
Hirono
Hodes
Holden
Holt
Honda
Hoyer
Inslee
Israel
Jackson (IL)
Jackson-Lee (TX)
Johnson, E. B.
Jones
Kagen
Kanjorski
Kaptur
Kennedy
Kildee
Kilpatrick (MI)
Kilroy
Kind
Kirk
Kirkpatrick (AZ)
Kissell
Klein (FL)
Kosmas
Kratovil
Kucinich
Langevin
Larsen (WA)
Larson (CT)
LaTourette
Lee (CA)
Lee (NY)
Levin
Lewis (GA)
Lipinski
LoBiondo
Loebsack
Lofgren, Zoe
Lowey
Lujan
Lungren, Daniel E.
Lynch
Maffei
Maloney
Markey (CO)
Markey (MA)
Marshall
Massa
Matsui
McCarthy (NY)
McCollum
McCotter
McDermott
McGovern
McNerney
Meek (FL)
Meeks (NY)
Melancon
Michaud
Miller (MI)
Miller (NC)
Miller, George
Minnick
Mollohan
Moore (KS)
Moore (WI)
Moran (VA)
Murphy (CT)
Murphy (NY)
Murphy, Patrick
Murtha
Myrick
Nadler (NY)
Napolitano
Neal (MA)
Norton
Nye
Oberstar
Ortiz
Pallone
Pascrell
Pastor (AZ)
Paulsen
Payne
Perriello
Peters
Peterson
Petri
Pierluisi
Pingree (ME)
Platts
Pomeroy
Price (NC)
Quigley
Radanovich
Rahall
Rangel
Reyes
Richardson
Rodriguez
Rogers (KY)
Rogers (MI)
Ros-Lehtinen
Roskam
Ross
Rothman (NJ)
Roybal-Allard
Ruppersberger
Ryan (OH)
Sablan
Sanchez, Linda T.
Sanchez, Loretta
Sarbanes
Schakowsky
Schauer
Schrader
Schwartz
Scott (GA)
Scott (VA)
Serrano
Sestak
Shea-Porter
Sherman
Shimkus
Shuler
Sires
Skelton
Slaughter
Space
Speier
Spratt
Stearns
Stupak
Sutton
Tauscher
Taylor
Teague
Thompson (CA)
Thompson (MS)
Tierney
Titus
Tonko
Towns
Tsongas
Turner
Van Hollen
Velazquez
Visclosky
Walz
Wamp
Wasserman Schultz
Waters
Watson
Watt
Waxman
Weiner
Welch
Wexler
Wilson (OH)
Wittman
Wolf
Woolsey
Wu
Yarmuth
Young (FL)
NOES--154
Aderholt
Akin
Alexander
Altmire
Austria
Bachmann
Bachus
Barrett (SC)
Bartlett
Bean
Biggert
Bilbray
Bilirakis
Blackburn
Blunt
Boehner
Bonner
Boozman
Boustany
Boyd
Brady (TX)
Bright
Broun (GA)
Burton (IN)
Calvert
Campbell
Cantor
Carter
Cassidy
Castle
Chaffetz
Childers
Coble
Coffman (CO)
Conaway
Culberson
Davis (KY)
Diaz-Balart, L.
Diaz-Balart, M.
Doggett
Dreier
Edwards (TX)
Emerson
Fallin
Flake
Foster
Foxx
Franks (AZ)
Frelinghuysen
Gallegly
Garrett (NJ)
Giffords
Goodlatte
Graves
Griffith
Hall (TX)
Harper
Hastings (WA)
Heller
Hensarling
Herger
Herseth Sandlin
Himes
Hoekstra
Hunter
Inglis
Issa
Jenkins
Johnson (IL)
Johnson, Sam
Jordan (OH)
King (IA)
King (NY)
Kingston
Kline (MN)
Lamborn
Lance
Latham
Latta
Lewis (CA)
Linder
Lucas
Luetkemeyer
Lummis
Mack
Manzullo
Marchant
Matheson
McCarthy (CA)
McCaul
McClintock
McHenry
McHugh
McIntyre
McKeon
McMahon
McMorris Rodgers
Mica
Miller (FL)
Miller, Gary
Mitchell
Moran (KS)
Murphy, Tim
Neugebauer
Nunes
Obey
Olson
Olver
Paul
Pence
Perlmutter
Pitts
Poe (TX)
Polis (CO)
Posey
Price (GA)
Putnam
Rehberg
Reichert
Roe (TN)
Rogers (AL)
Rohrabacher
Rooney
Royce
Ryan (WI)
Salazar
Scalise
Schiff
Schmidt
Schock
Sensenbrenner
Sessions
Shadegg
Shuster
Simpson
Smith (NE)
Smith (NJ)
Smith (TX)
Smith (WA)
Snyder
Souder
Sullivan
Tanner
Terry
Thompson (PA)
Thornberry
Tiahrt
Tiberi
Upton
Walden
Westmoreland
Whitfield
Wilson (SC)
Young (AK)
NOT VOTING--9
Berry
Bishop (UT)
Bordallo
Burgess
Granger
Hastings (FL)
Johnson (GA)
Rush
Stark
{time} 1439
Messrs. GALLEGLY, TANNER, FLAKE, BOYD, MITCHELL, FOSTER and SCHIFF
changed their vote from ``aye'' to ``no.''
Mrs. MILLER of Michigan and Messrs. GUTHRIE and WITTMAN changed their
vote from ``no'' to ``aye.''
So the amendment was agreed to.
The result of the vote was announced as above recorded.
Stated for:
Mr. RUSH. Mr. Chair, on rollcall No. 225 I was unavoidably detained
in a strategic meeting of significant interests to my constituents. Had
I been present, I would have voted ``aye.''
Amendment No. 8 Offered by Mrs. Maloney
The Acting CHAIR. The unfinished business is the demand for a
recorded vote on the amendment offered by the gentlewoman from New York
(Mrs. Maloney) on which further proceedings were postponed and on which
the ayes prevailed by voice vote.
The Clerk will redesignate the amendment.
The Clerk redesignated the amendment.
Recorded Vote
The Acting CHAIR. A recorded vote has been demanded.
A recorded vote was ordered.
The Acting CHAIR. This will be a 5-minute vote.
The vote was taken by electronic device, and there were--ayes 284,
noes 149, not voting 6, as follows:
[Roll No. 226]
AYES--284
Abercrombie
Ackerman
Aderholt
Adler (NJ)
Altmire
Andrews
Baca
Baird
Baldwin
Barrow
Becerra
Berkley
Berman
Bilbray
Bilirakis
Bishop (GA)
Bishop (NY)
Blumenauer
Boccieri
Boren
Boswell
Boucher
Brady (PA)
Brady (TX)
Braley (IA)
Bright
Brown (SC)
Brown, Corrine
Buchanan
Butterfield
Buyer
Campbell
Cao
Capps
Capuano
Cardoza
Carnahan
Carney
Carson (IN)
Cassidy
Castor (FL)
Chandler
Christensen
Clarke
Clay
Cleaver
Clyburn
Cohen
Cole
Connolly (VA)
Conyers
Cooper
Costello
Courtney
Crenshaw
Crowley
Cuellar
Culberson
Cummings
Davis (AL)
Davis (CA)
Davis (IL)
Davis (TN)
DeFazio
DeGette
Delahunt
DeLauro
Dent
Diaz-Balart, L.
Diaz-Balart, M.
Dicks
Dingell
Doggett
Donnelly (IN)
Doyle
Driehaus
Edwards (MD)
Edwards (TX)
Ellison
Ellsworth
Engel
Eshoo
Etheridge
Faleomavaega
Farr
Fattah
Filner
Fleming
Forbes
Fortenberry
Foster
Frank (MA)
Fudge
Gerlach
Giffords
Gohmert
Gonzalez
Gordon (TN)
Grayson
Green, Al
Green, Gene
Griffith
Grijalva
Gutierrez
Hall (NY)
Halvorson
Hare
Harman
Heinrich
Herseth Sandlin
Higgins
Hill
Himes
Hinchey
Hinojosa
Hirono
Hodes
Holden
Holt
Honda
Hoyer
Inslee
Israel
Jackson (IL)
Jackson-Lee (TX)
Johnson (GA)
Johnson, E. B.
Jones
Kagen
Kanjorski
Kaptur
Kennedy
Kildee
Kilpatrick (MI)
Kilroy
Kind
King (NY)
Kingston
Kirkpatrick (AZ)
Kissell
Klein (FL)
Kosmas
Kratovil
Kucinich
Langevin
Larsen (WA)
Larson (CT)
Latham
Lee (CA)
Levin
Lewis (GA)
Lipinski
LoBiondo
Loebsack
Lofgren, Zoe
Lowey
Lujan
Lynch
Maffei
Maloney
Markey (MA)
Marshall
Massa
Matsui
McCaul
McCollum
McDermott
McGovern
McHugh
McIntyre
McNerney
Meek (FL)
Meeks (NY)
Melancon
Michaud
Miller (NC)
Miller, George
Mitchell
Mollohan
Moore (KS)
Moore (WI)
Moran (VA)
Murphy (CT)
Murphy (NY)
Murphy, Patrick
Murtha
Nadler (NY)
Napolitano
Neal (MA)
Norton
Nye
Oberstar
Obey
Olver
Ortiz
Pallone
Pascrell
Pastor (AZ)
Payne
Perlmutter
Perriello
Peters
Peterson
Petri
Pierluisi
Pingree (ME)
Platts
Polis (CO)
Pomeroy
Price (NC)
Putnam
Quigley
Rahall
Rangel
Reichert
Reyes
Richardson
Rodriguez
Rogers (KY)
Rogers (MI)
Rohrabacher
Rooney
Ros-Lehtinen
Ross
Rothman (NJ)
Roybal-Allard
Ruppersberger
Rush
Ryan (OH)
Sablan
Sanchez, Linda T.
Sanchez, Loretta
Sarbanes
Schakowsky
Schauer
Schiff
Schrader
Schwartz
Scott (GA)
Scott (VA)
Serrano
Sestak
Shea-Porter
Sherman
Sires
Slaughter
Smith (NJ)
Smith (WA)
Snyder
Speier
Spratt
Stearns
Stupak
Sutton
Tauscher
Taylor
Teague
Terry
Thompson (CA)
Thompson (MS)
Thornberry
Tiahrt
Tierney
Titus
Tonko
Towns
Tsongas
Turner
Van Hollen
Velazquez
Visclosky
Walz
Wasserman Schultz
Waters
Watson
Watt
Waxman
Weiner
Welch
Wexler
Wilson (OH)
Woolsey
Wu
Yarmuth
NOES--149
Akin
Alexander
Arcuri
Austria
Bachmann
Bachus
Barrett (SC)
Bartlett
Barton (TX)
Bean
Biggert
Bishop (UT)
Blackburn
Blunt
Boehner
Bonner
Bono Mack
Boozman
Boustany
Boyd
Broun (GA)
Brown-Waite, Ginny
Burton (IN)
Calvert
Camp
Cantor
Capito
Carter
Castle
Chaffetz
Childers
Coble
Coffman (CO)
Conaway
Costa
Dahlkemper
Davis (KY)
Deal (GA)
Dreier
Duncan
Ehlers
Emerson
Fallin
Flake
Foxx
Franks (AZ)
Frelinghuysen
Gallegly
Garrett (NJ)
Gingrey (GA)
[[Page H5039]]
Goodlatte
Graves
Guthrie
Hall (TX)
Harper
Hastings (WA)
Heller
Hensarling
Herger
Hoekstra
Hunter
Inglis
Issa
Jenkins
Johnson (IL)
Johnson, Sam
Jordan (OH)
King (IA)
Kirk
Kline (MN)
Lamborn
Lance
LaTourette
Latta
Lee (NY)
Lewis (CA)
Linder
Lucas
Luetkemeyer
Lummis
Lungren, Daniel E.
Mack
Manzullo
Marchant
Markey (CO)
Matheson
McCarthy (CA)
McCarthy (NY)
McClintock
McCotter
McHenry
McKeon
McMahon
McMorris Rodgers
Mica
Miller (FL)
Miller (MI)
Miller, Gary
Minnick
Moran (KS)
Murphy, Tim
Myrick
Neugebauer
Nunes
Olson
Paul
Paulsen
Pence
Pitts
Poe (TX)
Posey
Price (GA)
Radanovich
Rehberg
Roe (TN)
Rogers (AL)
Roskam
Royce
Ryan (WI)
Salazar
Scalise
Schmidt
Schock
Sensenbrenner
Sessions
Shadegg
Shimkus
Shuler
Shuster
Simpson
Skelton
Smith (NE)
Smith (TX)
Souder
Space
Sullivan
Tanner
Thompson (PA)
Tiberi
Upton
Walden
Wamp
Westmoreland
Whitfield
Wilson (SC)
Wittman
Wolf
Young (AK)
Young (FL)
NOT VOTING--6
Berry
Bordallo
Burgess
Granger
Hastings (FL)
Stark
{time} 1448
So the amendment was agreed to.
The result of the vote was announced as above recorded.
PERSONAL EXPLANATION
Ms. BORDALLO. Mr. Chair, today I have been granted an official leave
of absence by the House of Representatives and am in my district
attending to official business. As such, I am unable to cast my votes
in the Committee of the Whole House on the State of the Union on
amendments to H.R. 627, the Credit Cardholders' Bill of Rights Act of
2009. If I were present for these votes, I would vote as follows and
ask that the Record reflect these positions: ``no'' on the amendment
offered by Ms. Slaughter of New York (rollcall vote 225) and ``aye'' on
the amendment offered by Mrs. Maloney of New York (rollcall vote 226).
The Acting CHAIR. The question is on the committee amendment in the
nature of a substitute, as amended.
The committee amendment in the nature of a substitute, as amended,
was agreed to.
The Acting CHAIR. Under the rule, the Committee rises.
Accordingly, the Committee rose; and the Speaker pro tempore (Mr.
Weiner) having assumed the chair, Mr. Serrano, Acting Chair of the
Committee of the Whole House on the state of the Union, reported that
that Committee, having had under consideration the bill (H.R. 627) to
amend the Truth in Lending Act to establish fair and transparent
practices relating to the extension of credit under an open end
consumer credit plan, and for other purposes, pursuant to House
Resolution 379, he reported the bill back to the House with an
amendment adopted by the Committee of the Whole.
The SPEAKER pro tempore. Under the rule, the previous question is
ordered.
Is a separate vote demanded on any amendment reported from the
Committee of the Whole? If not, the question is on the amendment.
The amendment was agreed to.
The SPEAKER pro tempore. The question is on the engrossment and third
reading of the bill.
The bill was ordered to be engrossed and read a third time, and was
read the third time.
Motion to Recommit
Mr. ROSKAM. Mr. Speaker, I have a motion to recommit at the desk.
The SPEAKER pro tempore. Is the gentleman opposed to the bill?
Mr. ROSKAM. I am, in its current form.
The SPEAKER pro tempore. The Clerk will report the motion.
The Clerk read as follows:
Mr. Roskam moves to recommit the bill H.R. 627 to the
Committee on Financial Services with instructions to report
the same back to the House forthwith with the following
instructions:
At the end of the bill, insert the following new section:
SEC. 11. TRIGGER FOR ENACTMENT.
No provision of the Act shall take effect until a study to
be completed by the Board of Governors of the Federal Reserve
System makes a determination that the provisions of the Act
will not result in a reduction in the availability of credit
covered by this Act to small businesses.
The SPEAKER pro tempore. The gentleman from Illinois is recognized
for 5 minutes.
Mr. ROSKAM. Mr. Speaker, we are here today because we are having a
national conversation about credit, and it is a conversation that has
had an impact on each and every one of our congressional districts. It
doesn't matter where we are from, it doesn't matter what our background
is, credit is inextricably linked to our success as a country.
So here we are, and we have got sponsors who have worked hard, and I
want to take my hat off to the sponsors and to the chairman of the
committee for taking on a very, very serious work. There are some good
things in here, there are some good things in the underlying bill, but
I think there is a weakness, and I want to point out the weakness and
offer a suggestion.
This is not a ``gotcha'' amendment. This was an idea presented to the
Rules Committee, and, unfortunately, it was sort of swatted aside. I
think it was a little bit misinterpreted, and that's disappointing. But
the great thing about this process is you get another shot at the
title. So here we are and we have another opportunity to consider this
idea. Here is what it says.
Notwithstanding everything that is in this bill, it doesn't matter
what you have been told about it, what has been represented to you,
what kind of talking points, what kind of hearings you have heard, what
kind of testimony, let's face it, if this falls short and it has an
adverse impact on small business, then we have failed. If this has an
adverse impact on the biggest job creators in our economy, then we have
failed.
So my attitude is look, we all, all of us, talk about how important
small business is, how important the entrepreneur is, how important the
self-employed are. But ultimately, if we are passing legislation that
has an adverse impact on that group's ability to get credit, we have
failed.
So what this amendment says, it says, look. What the motion says is
take a good hard look at the bill, but hit the pause button, and here
is why. Let the Fed look at this, do a study that says it is not going
to have an adverse impact on small business.
``Small business'' is a term of art, one that we can all come around.
It is not meant to sneak up on anybody. It is not meant to overly
characterize anything. But what it says is do the credit card changes,
if you will, but make sure we are not having an impact on the small
person.
Now, why is this important? Why should we be thinking in terms of a
pause button right now? And I want to give you three examples where we
cumulatively voted on things that have been presented in one way and
they have turned out very differently.
Remember during the bailout debate last fall, remember the drumbeat,
the pounding sort of, that pulsing feeling on the House floor and that
sense of urgency of you got to pass it, you got to pass it, you got to
pass it? Well, what is in it? I don't know, but just pass it and it is
all going to be great.
Well, it didn't work out so well. Credit markets haven't been
restored and we are still limping along months later.
Remember during the stimulus debate, when we heard from the White
House that if we pass this, unemployment was going to peak at 8
percent, the birds were going to be chirping, it was all going to be
great and that was going to be the high mark in terms of unemployment?
That didn't happen to turn out that way, and we are already at 8.5
percent or beyond.
And most recently in the budget figures we heard represented in the
Ways and Means Committee, that the Budget Committee heard, this is what
we were told in terms of projections: That real GDP was only going to
shrink by 1.2 percent this year. But already this quarter, this last
quarter, it is down 6.1 percent.
Now, why do I bring those numbers up? They are important because they
are indicators of mischaracterizations of things.
So when people say we are going to fix this credit card situation, my
reluctance, and I think the reason there is a little bit of reluctance
out there is the suggestion that there is going to be no cost to it and
it is all going to be great and it is all going to be roses, and what I
am suggesting to you today is that if we fail to protect small
business, then we have failed.
Now, you will hear that the NFIB has endorsed it, and endorsed it
they have. The NFIB has endorsed it, and I think
[[Page H5040]]
in fairness to the NFIB, they have looked at it and they have thought
it is okay.
But we can do better. We have an opportunity to raise this to a
higher standard. We have a chance today with adopting this simple
motion to say it is all well and good, but let's make sure the Fed
checks this out and comes back affirmatively.
Now, you might hear there is a study, Congressman, in the bill
already. And I would suggest to you that the way the study in the bill
is already crafted, it is a retroactive study, right? So it says within
3 months, 6 months of the acceptance date, we need to move forward.
You know what you need to do, and you know we need to do it.
Mr. GUTIERREZ. I rise in opposition to the motion.
The SPEAKER pro tempore. The gentleman from Illinois is recognized
for 5 minutes.
Mr. GUTIERREZ. Members of the House, a consistent argument that we
hear from the other side is about the alleged lack of transparency and
bipartisanship in this House; yet, it was only 5 minutes ago that we
received this motion to recommit. How seriously can we take this? It is
a motion to delay.
But we cannot stand another day and delay stopping the suffering of
the American consumers at the hands of practices that the Federal
Reserve Board, the same Federal Reserve Board which the minority wishes
to have a study, has already spoken. They said it is unfair, it is
deceptive, it is wrong, and we should change it. And we should not
delay one day more the suffering of the American consumers at the hands
of the deceptive practices of the credit card industry.
We are considering today a bill which already passed last year. The
gentlelady from New York, Carolyn Maloney , the architect of the bill,
a heroine for consumers across this country, deserves our recognition
and our praise and our gratitude for fighting, for fighting this good
and courageous fight.
Look, the Federal Reserve Board, the one you want to do a study, has
already spoken. It says the practices are unfair and deceptive, and
they have created rules and we will put them into effect on July 1,
2010, to stop those things.
I say let's not wait. Let's do it today. If it is unfair and it is
deceptive, this Congress has the responsibility to the American
consumer to act quickly and promptly with no further delay.
They say that this bill is for the small business community, a
community of businesses that we are very concerned about. But, look,
maybe you didn't get it. ``Key vote alert. On behalf of the National
Federation of Independent Businesses, the Nation's leading small
business advocates, we urge your support immediately for the Credit
Cardholders' Bill of Rights.'' They have spoken.
The National Small Business Association endorses the bill, also.
It seems to me that the predicate of the minority is that they are in
defense of small businesses. The small business community has already
spoken on this issue. We need to delay this no further.
{time} 1500
The only one, the only group in America that can be happy if we delay
this bill any longer are those that are engaged in deceptive predatory
lending to consumers who are already unemployed, who are already
suffering, who are already at the mercy of an economic system that just
isn't there for them. Let's stand up for consumers at least one time
while we're here. We can do it today, and the first step is saying
``no'' to the motion to recommit.
I yield to the gentlelady from New York, Carolyn Maloney.
Mrs. MALONEY. Today, America's consumers can see what a Democratic
President and a Democratic majority means to their lives. We can stop
these abusive practices by voting down the motion to recommit and
voting for the bill.
Small businesses, the Small Business Association was part of our
coalition. They support the bill. The National Federation of
Independent Businesses, they call it a key vote alert. They will score
people on this vote, a vote in support of the legislation.
So we have a chance to vote with the regulators of this country that
support the bill and have called these practices unfair, deceptive and
anticompetitive. We get to vote with 54 editorial boards across the
country that have endorsed the bill, with every consumer group, every
civil rights group, and many grassroots organizations that have called
this their number 1 legislative priority.
We do not need to delay. We need to vote against this motion to
recommit, and we need to move forward in enacting these provisions to
protect America's working men and women, particularly when our economy
is downturning, many people are losing their jobs. We need to protect
our consumers, not delay provisions that can help them better manage
their credit and stop abusive practices.
Vote for the Democratic bill.
Mr. GUTIERREZ. I would just like to say, once again, listen,
seriously, on both sides, let's not delay this any further. Vote ``no''
on the motion to recommit.
The SPEAKER pro tempore. Without objection, the previous question is
ordered on the motion to recommit.
There was no objection.
The SPEAKER pro tempore. The question is on the motion to recommit.
The question was taken; and the Speaker pro tempore announced that
the noes appeared to have it.
Recorded Vote
Mr. ROSKAM. Mr. Speaker, I demand a recorded vote.
A recorded vote was ordered.
The SPEAKER pro tempore. Pursuant to clause 9 of rule XX, the Chair
will reduce to 5 minutes the minimum time for any electronic vote on
the question of passage.
The vote was taken by electronic device, and there were--ayes 164,
noes 263, not voting 6, as follows:
[Roll No. 227]
AYES--164
Aderholt
Akin
Alexander
Austria
Bachmann
Bachus
Barrett (SC)
Bartlett
Barton (TX)
Biggert
Bilbray
Bilirakis
Bishop (UT)
Blackburn
Blunt
Boehner
Bonner
Bono Mack
Boozman
Boustany
Brady (TX)
Broun (GA)
Brown (SC)
Brown-Waite, Ginny
Buchanan
Burton (IN)
Buyer
Calvert
Camp
Campbell
Cantor
Cao
Capito
Carter
Cassidy
Castle
Chaffetz
Coble
Coffman (CO)
Cole
Conaway
Crenshaw
Culberson
Davis (KY)
Deal (GA)
Dent
Diaz-Balart, L.
Diaz-Balart, M.
Dreier
Duncan
Emerson
Fallin
Flake
Fleming
Foxx
Franks (AZ)
Gallegly
Garrett (NJ)
Giffords
Gingrey (GA)
Gohmert
Goodlatte
Graves
Guthrie
Hall (TX)
Harper
Heller
Hensarling
Herger
Hoekstra
Hunter
Inglis
Issa
Jenkins
Johnson (IL)
Johnson, Sam
Jordan (OH)
King (IA)
King (NY)
Kingston
Kirk
Kirkpatrick (AZ)
Kline (MN)
Lamborn
Lance
Latham
LaTourette
Latta
Lee (NY)
Lewis (CA)
Lucas
Luetkemeyer
Lummis
Lungren, Daniel E.
Mack
Manzullo
Marchant
McCarthy (CA)
McCaul
McClintock
McCotter
McHenry
McIntyre
McKeon
McMorris Rodgers
McNerney
Mica
Miller (FL)
Miller (MI)
Miller, Gary
Moran (KS)
Myrick
Neugebauer
Nunes
Nye
Olson
Paul
Paulsen
Pence
Pitts
Poe (TX)
Posey
Price (GA)
Putnam
Radanovich
Rehberg
Reichert
Roe (TN)
Rogers (AL)
Rogers (KY)
Rogers (MI)
Rooney
Ros-Lehtinen
Roskam
Royce
Ryan (WI)
Scalise
Schmidt
Schock
Sensenbrenner
Sessions
Shadegg
Shimkus
Shuster
Simpson
Smith (NE)
Smith (TX)
Souder
Stearns
Sullivan
Terry
Thompson (PA)
Thornberry
Tiahrt
Tiberi
Turner
Walden
Wamp
Westmoreland
Whitfield
Wilson (SC)
Wittman
Wolf
Young (AK)
NOES--263
Abercrombie
Ackerman
Adler (NJ)
Altmire
Andrews
Arcuri
Baca
Baird
Baldwin
Barrow
Bean
Becerra
Berkley
Berman
Bishop (GA)
Bishop (NY)
Blumenauer
Boccieri
Boren
Boswell
Boucher
Boyd
Brady (PA)
Braley (IA)
Bright
Brown, Corrine
Butterfield
Capps
Capuano
Cardoza
Carnahan
Carney
Carson (IN)
Castor (FL)
Chandler
Childers
Clarke
Clay
Cleaver
Clyburn
Cohen
Connolly (VA)
Conyers
Cooper
Costa
Costello
Courtney
Crowley
Cuellar
Cummings
Dahlkemper
Davis (AL)
Davis (CA)
Davis (IL)
Davis (TN)
DeFazio
DeGette
Delahunt
DeLauro
Dicks
Dingell
Doggett
Donnelly (IN)
Doyle
Driehaus
Edwards (MD)
Edwards (TX)
Ehlers
Ellison
Ellsworth
Engel
Eshoo
Etheridge
Farr
Fattah
Filner
Forbes
Fortenberry
Foster
Frank (MA)
Frelinghuysen
Fudge
Gerlach
Gonzalez
[[Page H5041]]
Gordon (TN)
Grayson
Green, Al
Green, Gene
Griffith
Grijalva
Gutierrez
Hall (NY)
Halvorson
Hare
Harman
Heinrich
Herseth Sandlin
Higgins
Hill
Himes
Hinchey
Hinojosa
Hirono
Hodes
Holden
Holt
Honda
Hoyer
Inslee
Israel
Jackson (IL)
Jackson-Lee (TX)
Johnson (GA)
Johnson, E. B.
Jones
Kagen
Kanjorski
Kaptur
Kennedy
Kildee
Kilpatrick (MI)
Kilroy
Kind
Kissell
Klein (FL)
Kosmas
Kratovil
Kucinich
Langevin
Larsen (WA)
Larson (CT)
Lee (CA)
Levin
Lewis (GA)
Linder
Lipinski
LoBiondo
Loebsack
Lofgren, Zoe
Lowey
Lujan
Lynch
Maffei
Maloney
Markey (CO)
Markey (MA)
Marshall
Massa
Matheson
Matsui
McCarthy (NY)
McCollum
McDermott
McGovern
McHugh
McMahon
Meek (FL)
Meeks (NY)
Melancon
Michaud
Miller (NC)
Miller, George
Minnick
Mitchell
Mollohan
Moore (KS)
Moore (WI)
Moran (VA)
Murphy (CT)
Murphy (NY)
Murphy, Patrick
Murphy, Tim
Murtha
Nadler (NY)
Napolitano
Neal (MA)
Oberstar
Obey
Olver
Ortiz
Pallone
Pascrell
Pastor (AZ)
Payne
Perlmutter
Perriello
Peters
Peterson
Petri
Pingree (ME)
Platts
Polis (CO)
Pomeroy
Price (NC)
Quigley
Rahall
Rangel
Reyes
Richardson
Rodriguez
Rohrabacher
Ross
Rothman (NJ)
Roybal-Allard
Ruppersberger
Rush
Ryan (OH)
Salazar
Sanchez, Linda T.
Sanchez, Loretta
Sarbanes
Schakowsky
Schauer
Schiff
Schrader
Schwartz
Scott (GA)
Scott (VA)
Serrano
Sestak
Shea-Porter
Sherman
Shuler
Sires
Skelton
Slaughter
Smith (NJ)
Smith (WA)
Snyder
Space
Speier
Spratt
Stupak
Sutton
Tanner
Tauscher
Taylor
Teague
Thompson (CA)
Thompson (MS)
Tierney
Titus
Tonko
Towns
Tsongas
Upton
Van Hollen
Velazquez
Visclosky
Walz
Wasserman Schultz
Waters
Watson
Watt
Waxman
Weiner
Welch
Wexler
Wilson (OH)
Woolsey
Wu
Yarmuth
Young (FL)
NOT VOTING--6
Berry
Burgess
Granger
Hastings (FL)
Hastings (WA)
Stark
{time} 1521
Messrs. GERLACH, MEEKS of New York, MINNICK, and Ms. McCOLLUM changed
their vote from ``aye'' to ``no.''
Messrs. FLAKE and CANTOR changed their vote from ``no'' to ``aye.''
So the motion to recommit was rejected.
The result of the vote was announced as above recorded.
The SPEAKER pro tempore. The question is on the passage of the bill.
The question was taken; and the Speaker pro tempore announced that
the ayes appeared to have it.
Recorded Vote
Mr. GUTIERREZ. Mr. Speaker, I demand a recorded vote.
A recorded vote was ordered.
The SPEAKER pro tempore. This will be a 5-minute vote.
The vote was taken by electronic device, and there were--ayes 357,
noes 70, not voting 7, as follows:
[Roll No. 228]
AYES--357
Abercrombie
Ackerman
Aderholt
Adler (NJ)
Akin
Alexander
Altmire
Andrews
Arcuri
Austria
Baca
Baird
Baldwin
Barrow
Bartlett
Barton (TX)
Bean
Becerra
Berkley
Berman
Biggert
Bilbray
Bilirakis
Bishop (GA)
Bishop (NY)
Blumenauer
Blunt
Boccieri
Bono Mack
Boozman
Boren
Boswell
Boucher
Boustany
Boyd
Brady (PA)
Braley (IA)
Bright
Brown (SC)
Brown, Corrine
Brown-Waite, Ginny
Buchanan
Burton (IN)
Butterfield
Buyer
Calvert
Camp
Campbell
Cao
Capito
Capps
Capuano
Cardoza
Carnahan
Carney
Carson (IN)
Carter
Cassidy
Castle
Castor (FL)
Chandler
Childers
Clarke
Clay
Cleaver
Clyburn
Coffman (CO)
Cohen
Cole
Connolly (VA)
Conyers
Cooper
Costa
Costello
Courtney
Crenshaw
Crowley
Cuellar
Culberson
Cummings
Dahlkemper
Davis (AL)
Davis (CA)
Davis (IL)
Davis (TN)
DeFazio
DeGette
Delahunt
DeLauro
Dent
Diaz-Balart, L.
Diaz-Balart, M.
Dicks
Dingell
Doggett
Donnelly (IN)
Doyle
Driehaus
Duncan
Edwards (MD)
Edwards (TX)
Ehlers
Ellison
Ellsworth
Emerson
Engel
Eshoo
Etheridge
Fallin
Farr
Fattah
Filner
Fleming
Forbes
Fortenberry
Foster
Frank (MA)
Frelinghuysen
Fudge
Gallegly
Gerlach
Giffords
Gonzalez
Gordon (TN)
Graves
Grayson
Green, Al
Green, Gene
Griffith
Grijalva
Guthrie
Gutierrez
Hall (NY)
Hall (TX)
Halvorson
Hare
Harman
Harper
Heinrich
Higgins
Hill
Himes
Hinchey
Hinojosa
Hirono
Hodes
Hoekstra
Holden
Holt
Honda
Hoyer
Hunter
Inslee
Israel
Issa
Jackson (IL)
Jackson-Lee (TX)
Johnson (GA)
Johnson (IL)
Johnson, E. B.
Jones
Kagen
Kanjorski
Kaptur
Kennedy
Kildee
Kilpatrick (MI)
Kilroy
Kind
King (NY)
Kingston
Kirk
Kirkpatrick (AZ)
Kissell
Klein (FL)
Kosmas
Kratovil
Kucinich
Lance
Langevin
Larsen (WA)
Larson (CT)
Latham
LaTourette
Lee (CA)
Lee (NY)
Levin
Lewis (CA)
Lewis (GA)
Lipinski
LoBiondo
Loebsack
Lofgren, Zoe
Lowey
Luetkemeyer
Lujan
Lungren, Daniel E.
Lynch
Maffei
Maloney
Markey (CO)
Markey (MA)
Marshall
Massa
Matheson
Matsui
McCarthy (NY)
McCaul
McCollum
McCotter
McDermott
McGovern
McHugh
McIntyre
McKeon
McMahon
McNerney
Meek (FL)
Meeks (NY)
Melancon
Mica
Michaud
Miller (MI)
Miller (NC)
Miller, George
Minnick
Mitchell
Mollohan
Moore (KS)
Moore (WI)
Moran (KS)
Moran (VA)
Murphy (CT)
Murphy (NY)
Murphy, Patrick
Murphy, Tim
Murtha
Nadler (NY)
Napolitano
Neal (MA)
Nye
Oberstar
Obey
Olver
Ortiz
Pallone
Pascrell
Pastor (AZ)
Paulsen
Payne
Pelosi
Perlmutter
Perriello
Peters
Peterson
Petri
Pingree (ME)
Platts
Polis (CO)
Pomeroy
Posey
Price (NC)
Putnam
Quigley
Radanovich
Rahall
Rangel
Rehberg
Reichert
Reyes
Richardson
Rodriguez
Roe (TN)
Rogers (AL)
Rogers (KY)
Rogers (MI)
Rohrabacher
Rooney
Ros-Lehtinen
Ross
Rothman (NJ)
Roybal-Allard
Ruppersberger
Rush
Ryan (OH)
Salazar
Sanchez, Linda T.
Sanchez, Loretta
Sarbanes
Schakowsky
Schauer
Schiff
Schock
Schrader
Schwartz
Scott (GA)
Scott (VA)
Serrano
Sestak
Shea-Porter
Sherman
Shimkus
Shuler
Shuster
Simpson
Sires
Skelton
Slaughter
Smith (NJ)
Smith (WA)
Snyder
Souder
Space
Speier
Spratt
Stearns
Stupak
Sullivan
Sutton
Tanner
Tauscher
Taylor
Teague
Terry
Thompson (CA)
Thompson (MS)
Tiberi
Tierney
Titus
Tonko
Towns
Tsongas
Turner
Upton
Van Hollen
Velazquez
Visclosky
Walden
Walz
Wamp
Wasserman Schultz
Waters
Watson
Watt
Waxman
Weiner
Welch
Wexler
Whitfield
Wilson (OH)
Wittman
Wolf
Woolsey
Wu
Yarmuth
Young (AK)
Young (FL)
NOES--70
Bachmann
Bachus
Barrett (SC)
Bishop (UT)
Blackburn
Boehner
Bonner
Brady (TX)
Broun (GA)
Cantor
Chaffetz
Coble
Conaway
Davis (KY)
Deal (GA)
Dreier
Flake
Foxx
Franks (AZ)
Garrett (NJ)
Gingrey (GA)
Gohmert
Goodlatte
Heller
Hensarling
Herger
Herseth Sandlin
Inglis
Jenkins
Johnson, Sam
Jordan (OH)
King (IA)
Kline (MN)
Lamborn
Latta
Linder
Lucas
Lummis
Mack
Manzullo
Marchant
McCarthy (CA)
McClintock
McHenry
McMorris Rodgers
Miller (FL)
Miller, Gary
Myrick
Neugebauer
Nunes
Olson
Paul
Pitts
Poe (TX)
Price (GA)
Roskam
Royce
Ryan (WI)
Scalise
Schmidt
Sensenbrenner
Sessions
Shadegg
Smith (NE)
Smith (TX)
Thompson (PA)
Thornberry
Tiahrt
Westmoreland
Wilson (SC)
NOT VOTING--7
Berry
Burgess
Granger
Hastings (FL)
Hastings (WA)
Pence
Stark
Announcement by the Speaker Pro Tempore
The SPEAKER pro tempore (during the vote). Members are reminded there
are less than 2 minutes remaining on this vote.
{time} 1534
Mrs. McMORRIS RODGERS and Mr. GOODLATTE changed their vote from
``aye'' to ``no.''
So the bill was passed.
The result of the vote was announced as above recorded.
A motion to reconsider was laid on the table.
____________________