An amendment numbered 10 printed in House Report 111-92 to allow creditors to use retroactive rate increases, universal default, and "double cycle billing" practices as long as they offer at least one card option that does not have those billing features to all of their existing customers.
What it does: Inserts new text at the section 127B(b) of the Truth in Lending Act (as added by section 2(b) of the bill)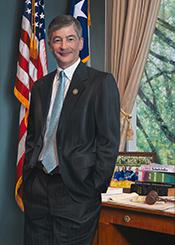 Rep. Jeb Hensarling (R-TX)
Description
Amendment sought to allow creditors to use retroactive rate increases, universal default, and "double cycle billing" practices as long as they offer at least one card option that does not have those billing features to all of their existing customers.
What it changes
1 change to H.R. 627
We couldn't match these changes to the text of H.R. 627, so they're shown as written.
We couldn't read part of this amendment. That part is shown as written below.
Inserts new text at the section 127B(b) of the Truth in Lending Act (as added by section 2(b) of the bill)
InsertsOriginal wording
In subsection (b) of section 127B of the Truth in Lending Act (as added by section 2(b) of the bill), insert the following
Shown as written
new paragraph after paragraph (1) (and redesignate the subsequent paragraphs accordingly): “(2) Nonapplicability to certain creditors who make available alternative card options.--The limitations on retroactive rate increases and universal default shall not apply to any creditor that offers a credit card account to consumers under an open end consumer credit plan to the extent such creditor--“(A) makes at least 1 credit card option available to 100 percent of the creditor's existing consumers that does not feature retroactive rate increases or universal default billing practice; and “(B) provides clear and conspicuous notice of the availability of a credit card option referred to in subparagraph (A) to the consumer customers of such creditor at least once annually.”. In subsection (e) of section 127B of the Truth in Lending Act (as added by section 3(a) of the bill), insert after paragraph (3) the following new paragraph: “(4) Nonapplicability to certain creditors who make available alternative card options.--The limitation on double cycle billing shall not apply to any creditor that offers a credit card account to consumers under an open end consumer credit plan to the extent such creditor--“(A) makes at least 1 credit card option available to 100 percent of the creditor's existing consumers that does not feature double cycle billing; and “(B) provides clear and conspicuous notice of the availability of a credit card option referred to in subparagraph (A) to the consumer customers of such creditor at least once annually.”.
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
In subsection (b) of section 127B of the Truth in Lending Act (as added by section 2(b) of the bill), insert the following new paragraph after paragraph (1) (and redesignate the subsequent paragraphs accordingly):
“(2) Nonapplicability to certain creditors who make available alternative card options.--The limitations on retroactive rate increases and universal default shall not apply to any creditor that offers a credit card account to consumers under an open end consumer credit plan to the extent such creditor--
“(A) makes at least 1 credit card option available to 100 percent of the creditor's existing consumers that does not feature retroactive rate increases or universal default billing practice; and
“(B) provides clear and conspicuous notice of the availability of a credit card option referred to in subparagraph (A) to the consumer customers of such creditor at least once annually.”.
In subsection (e) of section 127B of the Truth in Lending Act (as added by section 3(a) of the bill), insert after paragraph (3) the following new paragraph:
“(4) Nonapplicability to certain creditors who make available alternative card options.--The limitation on double cycle billing shall not apply to any creditor that offers a credit card account to consumers under an open end consumer credit plan to the extent such creditor--
“(A) makes at least 1 credit card option available to 100 percent of the creditor's existing consumers that does not feature double cycle billing; and
“(B) provides clear and conspicuous notice of the availability of a credit card option referred to in subparagraph (A) to the consumer customers of such creditor at least once annually.”.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
House amendment offered
April 30, 2009
View full timeline
House amendment offered
April 30, 2009
House amendment offered/reported by : Amendment (A010) offered by Mr. Hensarling.(consideration: CR H5027-5029; text: CR H5028)
April 30, 2009 • 1:03 PM
House amendment not agreed to: On agreeing to the Hensarling amendment (A010) Failed by voice vote.
April 30, 2009 • 1:15 PM
Amendment failed in Committee of the Whole
April 30, 2009 • 1:15 PM
Amendment (A010) offered by Mr. Hensarling. (consideration: CR H5027-5029; text: CR H5028)
April 30, 2009 • 1:03 PM
On agreeing to the Hensarling amendment (A010) Failed by voice vote.
April 30, 2009 • 1:15 PM