S.Amdt. 1124Senate111th Congress (2009-2011)2nd degree
S.Amdt. 1124
Sponsored by 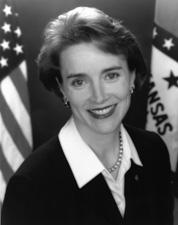 Sen. Blanche L. Lincoln (D-AR)
Submitted May 14, 2009
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Floor
Latest Action
Senate amendment submitted
May 14, 2009
Text
Submitted
TEXT OF AMENDMENTS

SA 1111. Mr. VITTER submitted an amendment intended to be proposed to
amendment SA 1058 proposed by Mr. Dodd (for himself and Mr. Shelby) to
the bill H.R. 627, to amend the Truth in Lending Act to establish fair
and transparent practices relating to the extension of credit under an
open end consumer credit plan, and for other purposes; which was
ordered to lie on the table; as follows:

At the end of title V, add the following:

SEC. 503. RESPA AND TILA DISCLOSURE IMPROVEMENT.

(a) Compatible Disclosures.--Not later than 6 months after
the date of enactment of this Act, the Secretary of Housing
and Urban Development (in this section referred to as the
``Secretary'') and the Board shall jointly issue for public
comment proposed regulations providing for compatible
disclosures to be made to borrowers to at the time of a
mortgage application and at the time of closing of a
mortgage.
(b) Requirements.--Such disclosures shall--
(1) provide clear and concise information to borrowers on
the terms and costs of residential mortgage transactions and
mortgage transactions covered by the Truth in Lending Act (12
U.S.C. 1601 et seq.) and the Real Estate Settlement
Procedures Act of 1974 (12 U.S.C. 2601 et seq.);
(2) satisfy the requirements of section 128 of the Truth in
Lending Act (12 U.S.C. 1638) and sections 4 and 5 of the Real
Estate Settlement Procedures Act of 1974 (12 U.S.C. 2603 and
2604);
(3) include early disclosures under the Truth in Lending
Act, the good faith estimate disclosures under the Real
Estate Settlement Procedures Act of 1974, and final
disclosures under the Truth in Lending Act and the uniform
settlement statement disclosures under the Real Estate
Settlement Procedures Act of 1974, and provide for
standardization to the greatest extent possible among such
disclosures, from mortgage origination through the mortgage
settlement; and
(4) include, with respect to a residential home mortgage
loan, a written statement of--
(A) the principal amount of the loan;
(B) the term of the loan;
(C) whether the loan has a fixed rate of interest or an
adjustable rate of interest;
(D) the annual percentage rate of interest under the loan
as of the time of the disclosure;
(E) if the rate of interest under the loan can adjust after
the disclosure, for each such possible adjustment--
(i) when such adjustment will or may occur; and
(ii) the maximum annual percentage rate of interest to
which it can be adjusted;
(F) the total monthly payment under the loan (including
loan principal and interest, property taxes, and insurance)
at the time of the disclosure;
(G) the maximum total estimated monthly maximum payment
pursuant to each possible adjustment described in
subparagraph (E);
(H) the total settlement charges in connection with the
loan and the amount of any down payment or cash required at
settlement; and
(I) whether the loan has a prepayment penalty or balloon
payment and the terms, timing, and amount of any such penalty
or payment.
(c) Suspension of 2008 RESPA Rule.--
(1) Requirement.--The Secretary shall, during the period
beginning on the date of enactment of this Act and ending on
the date on which proposed regulations are issued pursuant to
subsection (a), suspend implementation of any provision of
the final rule referred to in paragraph (2) that would
establish and implement a new standardized good faith
estimate and a new standardized uniform settlement statement.
Any such provision shall be replaced by the regulations
issued pursuant to subsections (a) and (b) on the date on
which such regulations are issued.
(2) 2008 rule.--The final rule referred to in this
paragraph is the rule of the Department of Housing and Urban
Development published on November 17, 2008, on pages 68204-
68288 of Volume 73 of the Federal Register (Docket No. FR-
5180-F-03; relating to ``Real Estate Settlement Procedures
Act (RESPA): Rule to Simplify and Improve the Process of
Obtaining Mortgages and Reduce Consumer Settlement Costs'').
(d) Implementation.--The regulations required under
subsection (a) shall take effect, and shall provide an
implementation date for the new disclosures required under
such regulations, not later than 12 months after the date of
enactment of this Act.
(e) Failure to Issue Compatible Disclosures.--
(1) Report to congress.--If the Secretary and the Board
cannot agree on compatible disclosures pursuant to
subsections (a) and (b), the Secretary and the Board shall
submit a report to the Congress, after the 6-month period
referred to in subsection (a), explaining the reasons for
such disagreement.
(2) Separate proposed regulations.--
(A) Issuance of proposed regulations.--After the 15-day
period beginning on the date of submission of a report under
paragraph (1), the Secretary and the Board may separately
issue for public comment regulations, as required by this
section, providing for disclosures under the Real Estate
Settlement Procedures Act of 1974 (12 U.S.C. 2601 et seq.)
and the Truth in Lending Act (12 U.S.C. 1601 et seq.),
respectively.
(B) Effective date of final regulatiosn.--Any final
disclosures as a result of such regulations issued by the
Secretary and the Board shall take effect on the same date,
and in no case shall such regulations take effect later than
12 months after the date of enactment of this Act.
(C) Failure to act.--If either the Secretary or the Board
fails to act as required by this paragraph during such 12-
month period, the other agency may act independently to
implement final regulations.
(f) Standardized Disclosure Forms.--
(1) In general.--Any regulation proposed or issued pursuant
to the requirements of this section shall include model
disclosure forms.
(2) Option for mandatory use.--In issuing proposed
regulations under subsection (a), the Secretary and the Board
shall include regulations for the mandatory use of
standardized disclosure forms if the Secretary and the Board
jointly determine that such forms would substantially benefit
consumers.
______

SA 1112. Mr. VITTER submitted an amendment intended to be proposed to
amendment SA 1058 proposed by Mr. Dodd (for himself and Mr. Shelby) to
the bill H.R. 627, to amend the Truth in Lending Act to establish fair
and transparent practices relating to the extension of credit under an
open end consumer credit plan, and for other purposes; which was
ordered to lie on the table; as follows:

On page 47, strike lines 10 and 11 and insert the
following:
``(6) the use of risk-based pricing;
``(7) credit card product innovation;
``(8) higher annual percentage rates of interest, on
average, for users than the average of such rates of interest
in effect before the effective date of this Act and the
amendments made by this Act;
``(9) the imposition of annual fees or other fees--
``(A) that did not exist before such effective date;
``(B) at a higher average rate of applicability than
existed before such effective date; or

[[Page S5532]]

``(C) with higher average costs to the consumer than were
in effect before such effective date;
``(10) any increase in the rate of denial of--
``(A) new credit accounts for consumers; or
``(B) new extensions of credit or additional lines of
credit for credit accounts established before such effective
date; and
``(11) any other adverse or negative condition or effect on
consumers.''.
______

SA 1113. Mr. THUNE (for himself and Mr. Johnson) submitted an
amendment intended to be proposed to amendment SA 1058 proposed by Mr.
Dodd (for himself and Mr. Shelby) to the bill H.R. 627, to amend the
Truth in Lending Act to establish fair and transparent practices
relating to the extension of credit under an open end consumer credit
plan, and for other purposes; which was ordered to lie on the table; as
follows:

On page 19, line 10, strike ``Section 127'' and insert the
following:
``(a) Report on Impact; Effective Date.--
``(1) Report by the board.--Not later than December 1,
2009, the Board shall provide an economic report to Congress
detailing the impact of section 127(n) of the Truth in
Lending Act, as added by this section, on consumer access to
credit.
``(2) Effective date.--Notwithstanding section 3 or any
other provision of this Act, unless the Board certifies in
writing to Congress that the economic report required by this
subsection shows no potential for a material reduction in
consumer access to credit, or if the Board fails to timely
issue the economic report required by this subsection,
section 127(n) of the Truth in Lending Act, as added by this
section, shall become effective 2 years after the date of
enactment of this Act. The effective date provided in section
3 shall apply to such section 127(n) if the Board certifies
that the report shows no potential reduction in consumer
access to credit.
``(b) Amendment to TILA.--Section 127''.
______

SA 1114. Mr. MARTINEZ submitted an amendment intended to be proposed
to amendment SA 1058 proposed by Mr. Dodd (for himself and Mr. Shelby)
to the bill H.R. 627, to amend the Truth in Lending Act to establish
fair and transparent practices relating to the extension of credit
under an open end consumer credit plan, and for other purposes; which
was ordered to lie on the table; as follows:

At the end of title V, add the following:

SEC. 503. ADDITIONAL MONITORING AND ACCOUNTABILITY FOR THE
TROUBLED ASSET RELIEF PROGRAM.

(a) In General.--Section 113 of the Emergency Economic
Stabilization Act of 2008 (12 U.S.C. 5223) is amended by
adding at the end the following new subsection:
``(e) Additional Monitoring and Accountability.--
``(1) In general.--The Secretary shall--
``(A) provide to the Special Inspector General appointed
under section 121, the Comptroller General of the United
States, and the Congressional Oversight Panel established
under section 125 ongoing, continuous, and close to real-time
updates of the status of the use of funds distributed under
this title, including with respect to procurement contracts,
through a standardized electronic database that combines all
of the necessary information from existing public and private
sources;
``(B) compare the data in such database with any other data
that the Secretary chooses to review for any activities that
are inconsistent with the purposes of this Act;
``(C) collect from all Federal agencies any regulatory
filings, data generated by the use of internal models,
financial models, and analytics associated with the financial
assistance received under this title on no less than a daily
basis to help enable the Secretary to determine the
effectiveness of the Troubled Asset Relief Program in
stimulating prudent lending and strengthening bank capital;
``(D) if the Secretary determines that the goals of this
title are not being met, work with the Federal agencies
supplying the information to have them provide the recipients
with recommendations for better meeting the goals of this
title; and
``(E) if the Secretary determines that the goals of this
title are not met following such recommendations, adjust the
future uses of assistance available under this title.
``(2) Database as repository.--To the extent practicable,
all information that is required to be reported under this
title by institutions receiving financial assistance or
procurement contracts under this title shall be included by
the Secretary in the database established pursuant to
paragraph (1)(A).
``(3) Procedures and regulations.--The Secretary shall, in
consultation with the appropriate Federal banking agencies,
define and manage the procedures and regulations needed for
carrying out this subsection.''.
(b) Effective Date.--The amendment made by this section
shall take effect 60 days after the date of enactment of this
Act.
______

SA 1115. Mr. MENENDEZ submitted an amendment intended to be proposed
to amendment SA 1058 proposed by Mr. Dodd (for himself and Mr. Shelby)
to the bill H.R. 627, to amend the Truth in Lending Act to establish
fair and transparent practices relating to the extension of credit
under an open end consumer credit plan, and for other purposes; which
was ordered to lie on the table; as follows:

Beginning on page 34, line 12, strike all through page 35,
line 24, and insert the following:

SEC. 301. EXTENSIONS OF CREDIT TO CONSUMERS.

Section 127(c) of the Truth in Lending Act (15 U.S.C.
1637(c)) is amended by adding at the end the following:
``(8) Verification of ability to pay.--
``(A) Prohibition on issuance.--No credit card may be
issued to, or open end consumer credit plan established by or
on behalf of, a consumer, unless the consumer has submitted a
written application to the card issuer that meets the
requirements of subparagraph (B).
``(B) Application requirements.--An application to open a
credit card account by a consumer shall require--
``(i) the signature of a cosigner having a means to repay
debts incurred by the consumer in connection with the
account, indicating joint liability for debts incurred by the
consumer in connection with the account; or
``(ii) submission by the consumer of financial information,
including through an application, indicating an independent
means of repaying any obligation arising from the proposed
extension of credit in connection with the account.
``(C) Safe harbor.--The Board shall promulgate regulations
providing standards that, if met, would satisfy the
requirements of subparagraph (B)(ii).''.
______

SA 1116. Mr. MENENDEZ submitted an amendment intended to be proposed
to amendment SA 1058 proposed by Mr. Dodd (for himself and Mr. Shelby)
to the bill H.R. 627, to amend the Truth in Lending Act to establish
fair and transparent practices relating to the extension of credit
under an open end consumer credit plan, and for other purposes; which
was ordered to lie on the table; as follows:

At the end of title I, add the following:

SEC. 109. FIRM OFFER OF CREDIT.

Section 603(l) of the Fair Credit Reporting Act (15 U.S.C.
1681a(l)) is amended to read as follows:
``(l) Firm Offer of Credit.--
``(1) Definition.--The term `firm offer of credit' means
any offer of credit to a consumer that specifies all material
terms, and will be honored if the consumer is determined to
meet the specific criteria used to select the consumer for
the offer, based on information in a consumer report on the
consumer.
``(2) Required disclosures in offers of credit.--In the
case of a firm offer of credit, the offer shall set forth the
specific annual percentage rate, fees, and amount of credit
or credit limit applicable to the offer.
``(3) Acceptable conditions.--A firm offer of credit to a
consumer may be further conditioned on--
``(A) verification that the consumer continues to meet the
specific criteria used to select the consumer for the offer,
by using information in a consumer report on the consumer,
information in the application of the consumer for the
credit, or other information bearing on the credit worthiness
of the consumer;
``(B) the consumer furnishing any collateral that is a
requirement for the extension of the credit that was--
``(i) established before selection of the consumer for the
offer of credit; and
``(ii) disclosed to the consumer in the offer of credit; or
``(C) any combination of the criteria in subparagraphs (A)
and (B).''.
______

SA 1117. Mr. LEVIN (for himself and Mrs. McCaskill) submitted an
amendment intended to be proposed to amendment SA 1058 proposed by Mr.
Dodd (for himself and Mr. Shelby) to the bill H.R. 627, to amend the
Truth in Lending Act to establish fair and transparent practices
relating to the extension of credit under an open end consumer credit
plan, and for other purposes; which was ordered to lie on the table; as
follows:

On page 15, strike lines 5 through 12, and insert the
following:
``(a) In General.--
``(1) The amount of any penalty fee or charge that a card
issuer may impose with respect to a credit card account under
an open end consumer credit plan in connection with any
omission with respect to, or violation of, the cardholder
agreement, including any late payment fee, over the limit
fee, or any other penalty fee or charge, shall be reasonable
and proportional to such omission or violation.
``(2) A fee amount shall not be treated as reasonable and
proportional under paragraph (1) if such card issuer
increases such fee amount by charging interest with respect
to such fee amount.''.
______

SA 1118. Mr. LEVIN submitted an amendment intended to be proposed to
amendment SA 1058 proposed by Mr. Dodd (for himself and Mr. Shelby) to

[[Page S5533]]

the bill H.R. 627, to amend the Truth in Lending Act to establish fair
and transparent practices relating to the extension of credit under an
open end consumer credit plan, and for other purposes; which was
ordered to lie on the table; as follows:

On page 15, strike lines 5 through 12, and insert the
following:
``(a) In General.--
``(1) The amount of any penalty fee or charge that a card
issuer may impose with respect to a credit card account under
an open end consumer credit plan in connection with any
omission with respect to, or violation of, the cardholder
agreement, including any late payment fee, over-the-limit
fee, or any other penalty fee or charge, shall be reasonable
and proportional to such omission or violation.
``(2) An over-the-limit fee amount may be treated as
reasonable and proportional under paragraph (1) only if the
over-the-limit fee is imposed only once during a billing
cycle when, on the last day of such billing cycle, the credit
limit on the account is exceeded, and only if the over-the-
limit fee, with respect to such excess credit, may be imposed
only once in each of the 2 subsequent billing cycles unless
the consumer has obtained an additional extension of credit
in excess of such credit limit during any such subsequent
cycle or the consumer reduces the outstanding balance below
the credit limit as of the end of such billing cycle.''.
______

SA 1119. Mr. LEVIN (for himself, Mrs. McCaskill, and Ms. Collins)
submitted an amendment intended to be proposed to amendment SA 1058
proposed by Mr. Dodd (for himself and Mr. Shelby) to the bill H.R. 627,
to amend the Truth in Lending Act to establish fair and transparent
practices relating to the extension of credit under an open end
consumer credit plan, and for other purposes; which was ordered to lie
on the table; as follows:

On page 46, line 18, through page 47, line 11, strike the
text and insert the following--
``(a) Required Review.--
``(1) In general.--Not later than 2 years after the
effective date of this Act and every 2 years thereafter,
except as provided in subsection (c)(2), the Board shall
conduct a review of the consumer credit card market,
including--
``(A) the terms of credit card agreements and the practices
of credit card issuers;
``(B) the effectiveness of disclosures of terms, fees, and
other expenses of credit card plans;
``(C) the adequacy of protections against unfair or
deceptive acts or practices relating to credit card plans;
``(D) the cost and availability of credit, particularly
with respect to non-prime borrowers;
``(E) the safety and soundness of credit card issuers;
``(F) the use of risk-based pricing; and
``(G) credit card product innovation; and
``(2) Credit card data.--In conducting the review under
paragraph (1), the Board shall consider information collected
under section 136 of the Truth in Lending Act (15 U.S.C.
1646); and to ensure an adequate review of the matters in
subparagraphs (1)(A), (C), (D), (F), and (G), and to carry
out section 149 of the Truth in Lending Act on the
reasonableness and proportionality of credit card fees and
charges, as amended by this Act, the Board shall require that
the information collected under section 136(b) of the Truth
in Lending Act (15 U.S.C. 1646(b)) shall include the
following--
``(A) a list of each type of transaction or event during
the relevant semiannual period for which one or more card
issuer has imposed a separate interest rate upon a
cardholder, including purchases, cash advances, and balance
transfers;
``(B) for each type of transaction or event identified
under subparagraph (A)--
``(i) each distinct interest rate charged by the card
issuer to a cardholder during the semiannual period; and
``(ii) the number of cardholders to whom each such interest
rate was applied during the last calendar month of the
semiannual period, and the total amount of interest charged
to such cardholders at each such rate during such month;
``(C) a list of each type of fee that one or more card
issuer has imposed upon a cardholder during the relevant
semiannual period, including any fee imposed for obtaining a
cash advance, making a late payment, exceeding the credit
limit on an account, making a balance transfer, or exchanging
United States dollars for foreign currency;
``(D) for each type of fee identified under clause (C), the
number of cardholders upon whom the fee was imposed during
each calendar month of the relevant semiannual period, and
the total amount of fees imposed upon cardholders during such
month;
``(E) the total number of cardholders that incurred any
interest charge or any fee during the relevant semiannual
period; and
``(F) any other information related to interest rates,
fees, or other charges that the Board deems of interest to
conduct the review under this section or carry out section
149 of the Truth in Lending Act, as amended by this Act.
``(3) Income analysis.--To ensure an adequate review of the
matters in subparagraphs (1)(A), (C), (D), (E), (F) and (G),
the Board shall, on an annual basis, transmit to Congress and
make public a report containing an assessment by the Board of
the approximate, relative percentage of income derived by
credit card operations of depository institutions from--
``(A) the imposition of interest rates on cardholders,
including separate estimates for--
``(i) interest with an annual percentage rate of less than
25 percent, and
``(ii) interest with an annual percentage rate equal to or
greater than 25 percent;
``(B) the imposition of fees on cardholders;
``(C) the imposition of fees on merchants; and
``(D) any other material source of income, while specifying
the nature of that income.''.
______

SA 1120. Mrs. BOXER submitted an amendment intended to be proposed to
amendment SA 1058 proposed by Mr. Dodd (for himself and Mr. Shelby) to
the bill H.R. 627, to amend the Truth in Lending Act to establish fair
and transparent practices relating to the extension of credit under an
open end consumer credit plan, and for other purposes; which was
ordered to lie on the table; as follows:

At the end of title V, add the following:

SEC. 503. REPORTS ON ISSUER PRACTICES DURING THE INTERIM
PERIOD BETWEEN THE DATE OF ENACTMENT AND THE
EFFECTIVE DATE.

(a) Reports to Agencies Required.--
(1) In general.--Not later than 45 days after the date of
enactment of this Act, and every 45 days thereafter, each
card issuer shall submit to the appropriate enforcement
agency a report containing data on any increase in consumer
interest rates by the card issuer made on or after May 1,
2009 that would be prohibited if such increase took place
after the effective date of this Act.
(2) Contents of reports.--The reports required under
paragraph (1)--
(A) shall include--
(i) the number of cardholders affected by each such
increase;
(ii) the categories of cardholders affected by each such
increase;
(iii) the size of each such increase;
(iv) the reason for each such increase; and
(v) a summary of the volume and nature of any complaints
received from cardholders concerning interest rate increases
that would be prohibited if such increases took place after
the effective date of this Act; and
(B) need not include information on individually negotiated
changes to contractual terms, such as individually modified
workouts or renegotiations of amounts owed by a consumer
under an open end consumer credit plan.
(b) Summary of Data on Complaints.--Each appropriate
enforcement agency shall--
(1) summarize information on the volume and nature of any
complaints received by such agency from a consumer concerning
interest rate increases that would be prohibited if such
increases took place after the effective date of this Act;
and
(2) provide such summary to the Board for purposes of
subsection (d).
(c) Reports and Data Available to Public.--Each appropriate
enforcement agency shall make the reports and data required
under subsections (a) and (b) available to the public.
(d) Reports to Congress.--
(1) Reports required.--The Board shall submit to Congress
periodic reports on practices of creditors that contain a
compilation of the reports and data required under
subsections (a) and (b).
(2) Agency cooperation.--Each appropriate enforcement
agency shall provide compilations of any reports it receives
under this section to the Board for purposes of this
subsection.
(3) Timing of reports.--The Board shall submit the reports
required under paragraph (1) not later than 90 days after the
date of enactment of this Act, and every 90 days thereafter.
(e) Effective Date.--Notwithstanding section 3 of this Act,
this section shall be effective during the period beginning
on the date of enactment of this Act and ending on the
effective date of this Act under section 3.
(f) Definitions.--In this section--
(1) the term ``appropriate enforcement agency'' means, with
respect to a card issuer, the agency responsible for
administrative enforcement relating to such card issuer under
section 108 of the Truth in Lending Act (15 U.S.C. 1607); and
(2) the terms ``cardholder'', ``card issuer'',
``consumer'', and ``open end credit plan'' have the same
meanings as section 103 of the Truth in Lending Act (15
U.S.C. 1602).
______

SA 1121. Mr. DURBIN (for himself and Mr. Bond) submitted an amendment
intended to be proposed to amendment SA 1058 proposed by Mr. Dodd (for
himself and Mr. Shelby) to the bill H.R. 627, to amend the Truth in
Lending Act to establish fair and transparent practices relating to the
extension of credit under an open end consumer credit plan, and for
other purposes; which was ordered to lie on the table; as follows:

At the end of title I, add the following:

[[Page S5534]]

SEC. 109. CONSUMER DISCOUNTS; TRANSPARENCY IN MERCHANT FEE
INFORMATION.

(a) In General.--Section 167 of the Truth in Lending Act
(15 U.S.C. 1666f) is amended to read as follows:

``SEC. 167. INDUCEMENTS TO CARD HOLDERS BY SELLERS OF
DISCOUNTS FOR PAYMENTS BY CASH, CHECK, OR DEBIT
CARDS; FINANCE CHARGE FOR SALES TRANSACTIONS
INVOLVING DISCOUNTS.

``(a) Cash, Check, and Debit Discounts.--With respect to a
credit card which may be used for extensions of credit in
sales transactions in which the seller is a person other than
the card issuer, the card issuer and any other covered person
may not, by contract, rule, or otherwise, prohibit any such
seller from offering a discount to a cardholder to induce the
cardholder to pay by cash, check, debit card, or similar
payment device, rather than by use of a credit card.
``(b) Finance Charge.--With respect to any sales
transaction, any discount from the regular price offered by
the seller for the purpose of inducing payment by a means not
involving the use of an open end credit plan or credit card
shall not constitute a finance charge, as determined under
section 106, if the seller--
``(1) offers the discount to all prospective buyers; and
``(2) discloses the availability of the discount to
consumers clearly and conspicuously.
``(c) Discount Display Restrictions.--With respect to a
credit card which may be used for extensions of credit in
sales transactions in which the seller is a person other than
the card issuer, the card issuer or any other covered person
may not, by contract, rule, or otherwise, restrict the
discretion of the seller as to how to display or advertise
the discounts offered by the seller.
``(d) Definitions.--For purposes of this section--
``(1) the term `covered person' means--
``(A) an electronic payment system network;
``(B) a licensed member of an electronic payment system
network; and
``(C) any other person that sets or implements the rules
for the use of an electronic payment system network.''.
(b) Definitions.--Section 103 of the Truth in Lending Act
(15 U.S.C. 1602) is amended--
(1) in subsection (x), by striking ``or similar means'' and
inserting ``debit card or similar payment device''; and
(2) by adding at the end the following:
``(cc) Debit Card.--The term `debit card' means any
general-purpose card or other device issued or approved for
use by a financial institution (as that term is defined in
section 903 of the Electronic Fund Transfer Act (15 U.S.C.
1693a)) for use in debiting an account for the purpose of the
cardholder obtaining goods or services, whether authorization
is signature-based, PIN-based, or otherwise.
``(dd) Electronic Payment System Network.--The term
`electronic payment system network' means a network that
provides, through licensed members, processors, or agents--
``(1) for the issuance of credit cards, debit cards, or
other payment cards or similar devices bearing any logo of
the network;
``(2) the proprietary services and infrastructure that
route information and data to facilitate transaction
authorization, clearance, and settlement that merchants must
access in order to accept credit cards, debit cards, or other
payment cards or similar devices bearing any logo of the
network as payment for goods and services; and
``(3) for the screening and acceptance of merchants into
the network in order to allow such merchants to accept credit
cards, debit cards, or other payment cards or similar devices
bearing any logo of the network as payment for goods and
services.
``(ee) Licensed Member.--The term `licensed member', in
connection with any electronic payment system network,
includes--
``(1) any creditor or credit card issuer that is authorized
to issue credit cards or charge cards bearing any logo of the
network;
``(2) any financial institution (as that term is defined in
section 903 of the Electronic Fund Transfer Act (15 U.S.C.
1693a)) that is authorized to issue debit cards to consumers
who maintain accounts at such financial institution; and
``(3) any person, including any financial institution, that
is authorized--
``(A) to screen and accept merchants into any program under
which any credit card, debit card, or other payment card or
similar device bearing any logo of such network may be
accepted by the merchant for payment for goods or services;
``(B) to process transactions on behalf of any such
merchant for payment; and
``(C) to complete financial settlement of any such
transaction on behalf of such merchant.''.
______

SA 1122. Mr. CRAPO submitted an amendment intended to be proposed to
amendment SA 1058 proposed by Mr. Dodd (for himself and Mr. Shelby) to
the bill H.R. 627, to amend the Truth in Lending Act to establish fair
and transparent practices relating to the extension of credit under an
open end consumer credit plan, and for other purposes; which was
ordered to lie on the table; as follows:

At the end of title V, add the following:

SEC. 503. FEDERAL TRADE COMMISSION RULEMAKING ON MORTGAGE
LENDING.

(a) In General.--Section 626 of division D of the Omnibus
Appropriations Act, 2009 (Public Law 111-8) is amended--
(1) in subsection (a)--
(A) by striking ``Within'' and inserting ``(1) Within'';
and
(B) by adding at the end the following:
``(2) Paragraph (1) shall not be construed to authorize the
Federal Trade Commission to promulgate a rule with respect to
an entity that is not subject to enforcement of the Federal
Trade Commission Act (15 U.S.C. 41 et seq.) by the
Commission.
``(3) The Federal Trade Commission shall enforce the rules
promulgated pursuant to paragraph (1) in the same manner, by
the same means, and with the same jurisdiction, powers, and
duties as though all applicable terms and provisions of the
Federal Trade Commission Act (15 U.S.C. 41 et seq.) were
incorporated into and made part of this section.
``(4) An entity owned and controlled by a depository
institution and regulated by the Federal Deposit Insurance
Corporation, the Comptroller of the Currency, the Board of
Governors of the Federal Reserve System, the Office of Thrift
Supervision, or the National Credit Union Administration
shall not be subject to any rule prescribed under paragraph
(1) if the entity is subject to a rule on the same subject
matter prescribed by the Board of Governors of the Federal
Reserve System pursuant to section 105 or 129(l) of the Truth
in Lending Act (15 U.S.C. 1604 and 1639(l)).'';
(2) by striking so much of subsection (b) as precedes
paragraph (2) and inserting the following:
``(b)(1) Except as provided in paragraph (6), in any case
in which the attorney general of a State has reason to
believe that an interest of the residents of that State has
been or is threatened or adversely affected by the engagement
of any person subject to a rule prescribed under subsection
(a) in a practice that violates such rule, the State, as
parens patriae, may bring a civil action on behalf of the
residents of the State in an appropriate district court of
the United States or other court of competent jurisdiction--
``(A) to enjoin that practice;
``(B) to enforce compliance with the rule;
``(C) to obtain damages, restitution, or other compensation
on behalf of residents of the State; or
``(D) to obtain penalties and relief provided by the
Federal Trade Commission Act or the rule and such other
relief as the court considers appropriate.''; and
(3) by adding at the end of subsection (b) the following:
``(8) Paragraph (1) shall not be construed to authorize the
attorney general of a State to bring an action under this
subsection against an entity subject to enforcement by the
Federal Deposit Insurance Corporation, the Comptroller of the
Currency, the Board of Governors of the Federal Reserve
System, the Office of Thrift Supervision, or the National
Credit Union Administration under section 108(a) of the Truth
in Lending Act (15 U.S.C. 1607(a)), including an entity
described in subsection (a)(4) of this section.''.
(b) Effective Date.--The amendments made by subsection (a)
shall take effect on March 12, 2009.
______

SA 1123. Mr. BURR submitted an amendment intended to be proposed to
amendment SA 1058 proposed by Mr. Dodd (for himself and Mr. Shelby) to
the bill H.R. 627, to amend the Truth in Lending Act to establish fair
and transparent practices relating to the extension of credit under an
open end consumer credit plan, and for other purposes; which was
ordered to lie on the table; as follows:

At the end of title V, add the following:

SEC. 503. DEFERRAL OF PAYMENTS AND INTEREST ON OBLIGATIONS
INCURRED BY SERVICEMEMBERS BEFORE SERVICE IN A
COMBAT ZONE.

(a) In General.--Title II of the Servicemembers Civil
Relief Act (50 U.S.C. App. 521 et seq.) is amended by adding
at the end the following new section:

``SEC. 208. DEFERRAL OF PAYMENTS AND INTEREST ON OBLIGATIONS
INCURRED BY SERVICEMEMBERS BEFORE SERVICE IN A
COMBAT ZONE.

``(a) In General.--Payment on any obligation or liability
that is incurred by a servicemember, or the servicemember and
the servicemember's spouse jointly, before the servicemember
is ordered or assigned to military service in a combat zone
shall, upon request of the servicemember in accordance with
subsection (b), be deferred and shall not accrue interest
during the period the servicemember performs such military
service in such combat zone, plus--
``(1) in the case of a servicemember who is retired for
disability incurred during such military service, until one
year from the date of such retirement; or
``(2) in the case of any other servicemember, 90 days.
``(b) Written Notice to Creditor.--In order for an
obligation or liability of a servicemember to be deferred in
accordance with subsection (a), the servicemember shall
provide the creditor written notice and a copy of the
military orders ordering or assigning the servicemember to
military service in a combat zone not later than 30 days
after the

[[Page S5535]]

date of the servicemember's order or assignment to such
military service. In the event the servicemember's military
service in a combat zone is extended, the servicemember shall
provide the creditor written notice and a copy of the
military orders extending such service not later than 30 days
after the date of the order extending such military service.
``(c) Limitation Effective as of Date of Orders.--Upon
receipt of written notice and a copy of orders ordering or
assigning a servicemember to military service in a combat
zone under subsection (b), the creditor shall treat the
obligation or liability in accordance with subsection (a),
effective as of the date on which the servicemember is called
or assigned to such military service.
``(d) Creditor Protection.--A court may grant a creditor
relief from the limitations of subsection (a) if, in the
opinion of the court, the ability of the servicemember to pay
the obligation or liability is not materially affected by
reason of the servicemember's military service in a combat
zone.
``(e) Definitions.--In this section:
``(1) The term `interest' includes service charges, renewal
charges, fees, or any other charges (other than bona fide
insurance) with respect to an obligation or liability.
``(2) The term `combat zone' means a combat zone for
purposes of section 112 of the Internal Revenue Code of
1986.''.
(b) Clerical Amendment.--The table of contents in section
1(b) of such Act is amended by inserting after the item
relating to section 207 the following new item:

``Sec. 208. Deferral of payments and interest on obligations incurred
by servicemembers before service in a combat zone.''.
______

SA 1124. Mrs. LINCOLN (for herself and Mr. Pryor) submitted an
amendment intended to be proposed to amendment SA 1058 proposed by Mr.
Dodd (for himself and Mr. Shelby) to the bill H.R. 627, to amend the
Truth in Lending Act to establish fair and transparent practices
relating to the extension of credit under an open end consumer credit
plan, and for other purposes; which was ordered to lie on the table; as
follows:

At the end of title V, add the following:

SEC. 503. EXTENSION OF LIMITATIONS.

(a) In General.--Section 44(f)(1) of the Federal Deposit
Insurance Act (12 U.S.C. 1831u(f)(1)) is amended--
(1) in subparagraph (B), by striking the period at the end
and inserting ``; and'';
(2) by redesignating subparagraphs (A) and (B) as clauses
(i) and (ii), respectively;
(3) by striking ``equal to not more than the greater of--''
and inserting the following: ``equal to--
``(A) not more than the greater of--''; and
(4) by adding at the end the following:
``(B) the State's maximum lawful annual percentage rate or
17 percent, to facilitate the uniform implementation of
federally mandated or federally established programs and
financings related thereto, including--
``(i) uniform accessibility of student loans, including the
issuance of qualified student loan bonds as set forth in
section 144(b) of the Internal Revenue Code of 1986;
``(ii) the uniform accessibility of mortgage loans,
including the issuance of qualified mortgage bonds and
qualified veterans' mortgage bonds as set forth in section
143 of such Code;
``(iii) the uniform accessibility of safe and affordable
housing programs administered or subject to review by the
Department of Housing and Urban Development, including--

``(I) the issuance of exempt facility bonds for qualified
residential rental property as set forth in section 142(d) of
such Code;
``(II) the issuance of low income housing tax credits as
set forth in section 42 of such Code, to facilitate the
uniform accessibility of provisions of the American Recovery
and Reinvestment Act of 2009; and
``(III) the issuance of bonds and obligations issued under
that Act, to facilitate economic development, higher
education, and improvements to infrastructure, and the
issuance of bonds and obligations issued under any provision
of law to further the same; and

``(iv) to facilitate interstate commerce generally,
including consumer loans, in the case of any person or
governmental entity (other than a depository institution
subject to subparagraph (A) and paragraph (2)).''.
(b) Effective Period.--The amendments made by subsection
(a) shall apply with respect to contracts consummated during
the period beginning on the date of enactment of this Act and
ending on December 31, 2010.
______

SA 1125. Mr. DORGAN submitted an amendment intended to be proposed to
amendment SA 1058 proposed by Mr. Dodd (for himself and Mr. Shelby) to
the bill H.R. 627, to amend the Truth in Lending Act to establish fair
and transparent practices relating to the extension of credit under an
open end consumer credit plan, and for other purposes; which was
ordered to lie on the table; as follows:

At the appropriate place, and the following:

SEC. ------. FEDERAL TRADE COMMISSION RULEMAKING ON MORTGAGE
LENDING.

(a) In General.--Section 626 of Division D of the Omnibus
Appropriations Act, 2009 (Public Law 111-8) is amended--
(1) by inserting ``(1) in subsection (a) before ``Within'';
(2) by inserting after paragraph (1) of subsection (a) (as
designated by paragraph (1)), the following:
``(2) Paragraph (1) shall not be construed to authorize the
Federal Trade Commission to promulgate a rule with respect to
an entity that is not subject to enforcement of the Federal
Trade Commission Act (15 U.S.C.41 et seq.) by the Commission.
``(3) The Federal Trade Commission shall enforce the
provisions of this section in the same manner, by the same
means, and with the same jurisdiction, powers, and duties as
though all applicable terms and provisions of the Federal
Trade Commission Act (15 U.S.C. 41 et seq.) were incorporated
into and made part of this section.'';
(3) by striking so much of subsection (b) as precedes
paragraph (2) and inserting the following:
``(b)(1) Except as provided in paragraph (6), in any case
in which the attorney general of a State has reason to
believe that an interest of the residents of that State has
been or is threatened or adversely affected by the engagement
of any person subject to a rule prescribed under subsection
(a) in a practice that violates such rule, the State, as
parens patriae, may bring a civil action on behalf of the
residents of the State in an appropriate district court of
the United States or other court of competent jurisdiction--
``(A) to enjoin that practice;
``(B) to enforce compliance with the rule;
``(C) to obtain damages, restitution, or other compensation
on behalf of residents of the State; or
``(D) to obtain penalties and relief provided by the
Federal Trade Commission Act or the rule and such other
relief as the court considers appropriate.''; and
(4) by adding at the end of subsection (b) the following:
``(8) Paragraph (1) shall not be construed to authorize the
attorney general of a State to bring an action under this
subsection against an entity subject to supervision or
regulation by the Federal Deposit Insurance Corporation, the
Comptroller of the Currency, the Federal Reserve Board, the
Office of Thrift Supervision, the National Credit Union
Administration Board, or any other Federal banking agency.''.
(b) Effective Date.--The amendments made by subsection (a)
shall take effect on March 12, 2009.
______

SA 1126. Mrs. LINCOLN (for herself and Mr. Pryor) submitted an
amendment intended to be proposed to amendment SA 1107 submitted by Ms.
Collins (for herself, Mr. Lieberman, and Mr. Burris) to the amendment
SA 1058 proposed by Mr. Dodd (for himself and Mr. Shelby) to the bill
H.R. 627, to amend the Truth in Lending Act to establish fair and
transparent practices relating to the extension of credit under an open
end consumer credit plan, and for other purposes; as follows:

At the end of the amendment, add the following:

SEC. 504. EXTENSION OF LIMITATIONS.

(a) In General.--Section 44(f)(1) of the Federal Deposit
Insurance Act (12 U.S.C. 1831u(f)(1)) is amended--
(1) in subparagraph (B), by striking the period at the end
and inserting ``; and'';
(2) by redesignating subparagraphs (A) and (B) as clauses
(i) and (ii), respectively;
(3) by striking ``equal to not more than the greater of--''
and inserting the following: ``equal to--
``(A) not more than the greater of--''; and
(4) by adding at the end the following:
``(B) the State's maximum lawful annual percentage rate or
17 percent, to facilitate the uniform implementation of
federally mandated or federally established programs and
financings related thereto, including--
``(i) uniform accessibility of student loans, including the
issuance of qualified student loan bonds as set forth in
section 144(b) of the Internal Revenue Code of 1986;
``(ii) the uniform accessibility of mortgage loans,
including the issuance of qualified mortgage bonds and
qualified veterans' mortgage bonds as set forth in section
143 of such Code;
``(iii) the uniform accessibility of safe and affordable
housing programs administered or subject to review by the
Department of Housing and Urban Development, including--

``(I) the issuance of exempt facility bonds for qualified
residential rental property as set forth in section 142(d) of
such Code;
``(II) the issuance of low income housing tax credits as
set forth in section 42 of such Code, to facilitate the
uniform accessibility of provisions of the American Recovery
and Reinvestment Act of 2009; and
``(III) the issuance of bonds and obligations issued under
that Act, to facilitate economic development, higher
education, and improvements to infrastructure, and the
issuance of bonds and obligations issued under any provision
of law to further the same; and

``(iv) to facilitate interstate commerce generally,
including consumer loans, in the case of any person or
governmental entity (other than a depository institution
subject to subparagraph (A) and paragraph (2)).''.
(b) Effective Period.--The amendments made by subsection
(a) shall apply with respect to contracts consummated during
the period beginning on the date of enactment of this Act and
ending on December 31, 2010.

[[Page S5536]]

______

SA 1127. Ms. SNOWE (for herself and Ms. Landrieu) submitted an
amendment intended to be proposed by her to the bill H.R. 627, to amend
the Truth in Lending Act to establish fair and transparent practices
relating to the extension of credit under an open end consumer credit
plan, and for other purposes; which was ordered to lie on the table; as
follows:

At the appropriate place, insert the following:

SEC. ___. SMALL BUSINESS INFORMATION SECURITY TASK FORCE.

(a) Definitions.--In this section--
(1) the terms ``Administration'' and ``Administrator'' mean
the Small Business Administration and the Administrator
thereof, respectively;
(2) the term ``small business concern'' has the same
meaning as in section 3 of the Small Business Act (15 U.S.C.
632); and
(3) the term ``task force'' means the task force
established under subsection (b).
(b) Establishment.--The Administrator shall, in conjunction
with the Department of Homeland Security, establish a task
force, to be known as the Small Business Information Security
Task Force, to address the information technology security
needs of small business concerns and to help small business
concerns prevent the loss of credit card data.
(c) Duties.--The task force shall--
(1) identify--
(A) the information technology security needs of small
business concerns; and
(B) the programs and services provided by the Federal
Government, State Governments, and nongovernment
organizations that serve those needs;
(2) assess the extent to which the programs and services
identified under paragraph (1)(B) serve the needs identified
under paragraph (1)(A);
(3) make recommendations to the Administrator on how to
more effectively serve the needs identified under paragraph
(1)(A) through--
(A) programs and services identified under paragraph
(1)(B); and
(B) new programs and services promoted by the task force;
(4) make recommendations on how the Administrator may
promote--
(A) new programs and services that the task force
recommends under paragraph (3)(B); and
(B) programs and services identified under paragraph
(1)(B);
(5) make recommendations on how the Administrator may
inform and educate with respect to--
(A) the needs identified under paragraph (1)(A);
(B) new programs and services that the task force
recommends under paragraph (3)(B); and
(C) programs and services identified under paragraph
(1)(B);
(6) make recommendations on how the Administrator may more
effectively work with public and private interests to address
the information technology security needs of small business
concerns; and
(7) make recommendations on the creation of a permanent
advisory board that would make recommendations to the
Administrator on how to address the information technology
security needs of small business concerns.
(d) Internet Website Recommendations.--The task force shall
make recommendations to the Administrator relating to the
establishment of an Internet website to be used by the
Administration to receive and dispense information and
resources with respect to the needs identified under
subsection (c)(1)(A) and the programs and services identified
under subsection (c)(1)(B). As part of the recommendations,
the task force shall identify the Internet sites of
appropriate programs, services, and organizations, both
public and private, to which the Internet website should
link.
(e) Education Programs.--The task force shall make
recommendations to the Administrator relating to developing
additional education materials and programs with respect to
the needs identified under subsection (c)(1)(A).
(f) Existing Materials.--The task force shall organize and
distribute existing materials that inform and educate with
respect to the needs identified under subsection (c)(1)(A)
and the programs and services identified under subsection
(c)(1)(B).
(g) Coordination With Public and Private Sector.--In
carrying out its responsibilities under this section, the
task force shall coordinate with, and may accept materials
and assistance as it determines appropriate from, public and
private entities, including--
(1) any subordinate officer of the Administrator;
(2) any organization authorized by the Small Business Act
to provide assistance and advice to small business concerns;
(3) other Federal agencies, their officers, or employees;
and
(4) any other organization, entity, or person not described
in paragraph (1), (2), or (3).
(h) Appointment of Members.--
(1) Chairperson and vice-chairperson.--The task force shall
have--
(A) a Chairperson, appointed by the Administrator; and
(B) a Vice-Chairperson, appointed by the Administrator, in
consultation with appropriate nongovernmental organizations,
entities, or persons.
(2) Members.--
(A) Chairperson and vice-chairperson.--The Chairperson and
the Vice-Chairperson shall serve as members of the task
force.
(B) Additional members.--
(i) In general.--The task force shall have additional
members, each of whom shall be appointed by the Chairperson,
with the approval of the Administrator.
(ii) Number of members.--The number of additional members
shall be determined by the Chairperson, in consultation with
the Administrator, except that--

(I) the additional members shall include, for each of the
groups specified in paragraph (3), at least 1 member
appointed from within that group; and
(II) the number of additional members shall not exceed 13.

(3) Groups represented.--The groups specified in this
paragraph are--
(A) subject matter experts;
(B) users of information technologies within small business
concerns;
(C) vendors of information technologies to small business
concerns;
(D) academics with expertise in the use of information
technologies to support business;
(E) small business trade associations;
(F) Federal, State, or local agencies, including the
Department of Homeland Security, engaged in securing
cyberspace; and
(G) information technology training providers with
expertise in the use of information technologies to support
business.
(4) Political affiliation.--The appointments under this
subsection shall be made without regard to political
affiliation.
(i) Meetings.--
(1) Frequency.--The task force shall meet at least 2 times
per year, and more frequently if necessary to perform its
duties.
(2) Quorum.--A majority of the members of the task force
shall constitute a quorum.
(3) Location.--The Administrator shall designate, and make
available to the task force, a location at a facility under
the control of the Administrator for use by the task force
for its meetings.
(4) Minutes.--
(A) In general.--Not later than 30 days after the date of
each meeting, the task force shall publish the minutes of the
meeting in the Federal Register and shall submit to
Administrator any findings or recommendations approved at the
meeting.
(B) Submission to congress.--Not later than 60 days after
the date that the Administrator receives minutes under
subparagraph (A), the Administrator shall submit to the
Committee on Small Business and Entrepreneurship of the
Senate and the Committee on Small Business of the House of
Representatives such minutes, together with any comments the
Administrator considers appropriate.
(5) Findings.--
(A) In general.--Not later than the date on which the task
force terminates under subsection (m), the task force shall
submit to the Administrator a final report on any findings
and recommendations of the task force approved at a meeting
of the task force.
(B) Submission to congress.--Not later than 90 days after
the date on which the Administrator receives the report under
subparagraph (A), the Administrator shall submit to the
Committee on Small Business and Entrepreneurship of the
Senate and the Committee on Small Business of the House of
Representatives the full text of the report submitted under
subparagraph (A), together with any comments the
Administrator considers appropriate.
(j) Personnel Matters.--
(1) Compensation of members.--Each member of the task force
shall serve without pay for their service on the task force.
(2) Travel expenses.--Each member of the task force shall
receive travel expenses, including per diem in lieu of
subsistence, in accordance with applicable provisions under
subchapter I of chapter 57 of title 5, United States Code.
(3) Detail of sba employees.--The Administrator may detail,
without reimbursement, any of the personnel of the
Administration to the task force to assist it in carrying out
the duties of the task force. Such a detail shall be without
interruption or loss of civil status or privilege.
(4) SBA support of the task force.--Upon the request of the
task force, the Administrator shall provide to the task force
the administrative support services that the Administrator
and the Chairperson jointly determine to be necessary for the
task force to carry out its duties.
(k) Not Subject to Federal Advisory Committee Act.--The
Federal Advisory Committee Act (5 U.S.C. App.) shall not
apply to the task force.
(l) Startup Deadlines.--The initial appointment of the
members of the task force shall be completed not later than
90 days after the date of enactment of this Act, and the
first meeting of the task force shall be not later than 180
days after the date of enactment of this Act.
(m) Termination.--
(1) In general.--Except as provided in paragraph (2), the
task force shall terminate at the end of fiscal year 2013.
(2) Exception.--If, as of the termination date under
paragraph (1), the task force has not complied with
subsection (i)(4) with respect to 1 or more meetings, then
the task force shall continue after the termination date for
the sole purpose of achieving compliance with subsection
(i)(4) with respect to those meetings.

[[Page S5537]]

(n) Authorization of Appropriations.--There is authorized
to be appropriated to carry out this section $300,000 for
each of fiscal years 2010 through 2013.
______

SA 1128. Mr. McCONNELL (for himself and Mr. Reid) proposed an
amendment to the bill S. 386, to improve enforcement of mortgage fraud,
securities and commodities fraud, financial institution fraud, and
other frauds related to Federal assistance and relief programs, for the
recovery of funds lost to these frauds, and for other purposes; as
follows:

On 31, line 13, after ``the Commission'' insert ``,
including an affirmative vote of at least one member
appointed under subparagraph (C) or (D) of subsection
(b)(1)''.
______

SA 1129. Mrs. MURRAY submitted an amendment intended to be proposed
to amendment SA 1106 submitted by Mrs. Murray and intended to be
proposed to the amendment SA 1058 proposed by Mr. Dodd (for himself and
Mr. Shelby) to the bill H.R. 627, to amend the Truth in Lending Act to
establish fair and transparent practices relating to the extension of
credit under an open end consumer credit plan, and for other purposes;
which was ordered to lie on the table; as follows:

In lieu of the matter proposed to be inserted, insert the
following:

SEC. 503. FINANCIAL AND ECONOMIC LITERACY.

(a) In General.--Not later than 180 days after the date of
enactment of this Act, the Financial Literacy and Education
Commission shall--
(1) evaluate and compile a comprehensive summary of all
existing Federal financial and economic literacy education
programs, as of the time of the report; and
(2) prepare and submit a report to Congress that includes--
(A) the findings of the evaluations and the effectiveness
of Federal financial and economic literacy education
programs, including programs included in the Commission's
2006 National Strategy for Financial Literacy report;
(B) recommendations for improvements to Federal financial
and economic literacy education programs;
(C) specific Federal policies that should be implemented,
updated, or changed to improve financial and economic
literacy education;
(D) a description of any gaps that exist in research on
financial and economic literacy education, and
recommendations on research that would fill those gaps;
(E) specific recommendations on sources of revenue to
support financial and economic literacy education activities,
with a specific analysis of the potential use of credit card
transaction fees; and
(F) recommendations for ways to increase the awareness of
elementary and secondary schools, postsecondary educational
institutions, and the general public of the Commission's
website,
www.
MyMoney.gov, or any successor to such website.
(b) Effective Date.--Notwithstanding section 3, this
section shall become effective on the date of enactment of
this Act.

____________________