To amend the Internal Revenue Code of 1986 to expand the application of the homebuyer credit, and for other purposes.
What it does: Adds SEC. 504. CREDIT FOR CERTAIN HOME PURCHASES at the end of title V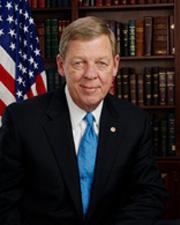 Sen. Johnny Isakson (R-GA)
What it changes
1 change to H.R. 2346
Adds SEC. 504. CREDIT FOR CERTAIN HOME PURCHASES at the end of title V
Adds a sectionInserted: SEC. 504. CREDIT FOR CERTAIN HOME PURCHASES.
Inserted: (a) Elimination of First-Time Homebuyer Requirement.--
Inserted: (1) In general.--Subsection (a) of section 36 of the Internal Revenue Code of 1986 is amended by striking "who is a first-time homebuyer of a principal residence" and inserting "who purchases a principal residence".
Inserted: (2) Conforming amendments.--
Inserted: (A) Subsection (c) of section 36 of such Code is amended by striking paragraph (1) and by redesignating paragraphs (2), (3), (4), and (5) as paragraphs (1), (2), (3), and (4), respectively.
Inserted: (B) Section 36 of such Code is amended by striking "FIRST-TIME HOMEBUYER CREDIT" in the heading and inserting "HOME PURCHASE CREDIT".
Inserted: (C) The table of sections for subpart C of part IV of subchapter A of chapter 1 of such Code is amended by striking the item relating to section 36 and inserting the following new item:
Inserted: "Sec. 36. Home purchase credit.".
Inserted: (D) Subparagraph (W) of section 26(b)(2) of such Code is amended by striking "homebuyer credit" and inserting "home purchase credit".
Inserted: (b) Elimination of Recapture Except for Homes Sold Within 3 Years.--Subsection (f) of section 36 of the Internal Revenue Code of 1986 is amended to read as follows:
Inserted: "(f) Recapture of Credit in the Case of Certain Dispositions.--
Inserted: "(1) In general.--In the event that a taxpayer--
Show 19 more inserted paragraphsShow less
Inserted: "(A) disposes of the principal residence with respect to which a credit was allowed under subsection (a), or
Inserted: "(B) fails to occupy such residence as the taxpayer's principal residence, at any time within 36 months after the date on which the taxpayer purchased such residence, then the tax imposed by this chapter for the taxable year during which such disposition occurred or in which the taxpayer failed to occupy the residence as a principal residence shall be increased by the amount of such credit.
Inserted: "(2) Exceptions.--
Inserted: "(A) Death of taxpayer.--Paragraph (1) shall not apply to any taxable year ending after the date of the taxpayer's death.
Inserted: "(B) Involuntary conversion.--Paragraph (1) shall not apply in the case of a residence which is compulsorily or involuntarily converted (within the meaning of section 1033(a)) if the taxpayer acquires a new principal residence within the 2-year period beginning on the date of the disposition or cessation referred to in such paragraph. Paragraph (1) shall apply to such new principal residence during the remainder of the 36-month period described in such paragraph as if such new principal residence were the converted residence.
Inserted: "(C) Transfers between spouses or incident to divorce.--In the case of a transfer of a residence to which section 1041(a) applies--
Inserted: "(i) paragraph (1) shall not apply to such transfer, and
Inserted: "(ii) in the case of taxable years ending after such transfer, paragraph (1) shall apply to the transferee in the same manner as if such transferee were the transferor (and shall not apply to the transferor).
Inserted: "(D) Relocation of members of the armed forces.--Paragraph (1) shall not apply in the case of a member of the Armed Forces of the United States on active duty who moves pursuant to a military order and incident to a permanent change of station.
Inserted: "(3) Joint returns.--In the case of a credit allowed under subsection (a) with respect to a joint return, half of such credit shall be treated as having been allowed to each individual filing such return for purposes of this subsection.
Inserted: "(4) Return requirement.--If the tax imposed by this chapter for the taxable year is increased under this subsection, the taxpayer shall, notwithstanding section 6012, be required to file a return with respect to the taxes imposed under this subtitle.".
Inserted: (c) Expansion of Application Period.--Subsection (h) of section 36 of the Internal Revenue Code of 1986 is amended by striking "December 1, 2009" and inserting "June 1, 2010".
Inserted: (d) Election To Treat Purchase in Prior Year.--Subsection (g) of section 36 of the Internal Revenue Code of 1986 is amended by striking "December 1, 2009" and inserting "June 1, 2010".
Inserted: (e) Elimination of Income Limitation.--Subsection (b) of section 36 of the Internal Revenue Code of 1986 is amended to read as follows:
Inserted: "(b) Dollar Limitation.--
Inserted: "(1) In general.--Except as otherwise provided in this subsection, the credit allowed under subsection (a) shall not exceed $8,000.
Inserted: "(2) Married individuals filing separately.--In the case of a married individual filing a separate return, paragraph (1) shall be applied by substituting '$4,000' for '$8,000'.
Inserted: "(3) Other individuals.--If two or more individuals who are not married purchase a principal residence, the amount of the credit allowed under subsection (a) shall be allocated among such individuals in such manner as the Secretary may prescribe, except that the total amount of the credits allowed to all such individuals shall not exceed $8,000.".
Inserted: (f) Effective Date.--The amendments made by this section shall apply to residences purchased on or after the date of the enactment of this Act.
Original wording
At the end of title V, insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 1164. Mr. ISAKSON (for himself, Mr. Chambliss, Mr. Dodd, and Mr. Lieberman) submitted an amendment intended to be proposed by him to the bill H.R. 2346, making supplemental appropriations for the fiscal year ending September 30, 2009, and for other purposes; as follows:
At the end of title V, insert the following:
SEC. 504. CREDIT FOR CERTAIN HOME PURCHASES.
(a) Elimination of First-Time Homebuyer Requirement.--
(1) In general.--Subsection (a) of section 36 of the Internal Revenue Code of 1986 is amended by striking “who is a first-time homebuyer of a principal residence” and inserting “who purchases a principal residence”.
(2) Conforming amendments.--
(A) Subsection (c) of section 36 of such Code is amended by striking paragraph (1) and by redesignating paragraphs (2), (3), (4), and (5) as paragraphs (1), (2), (3), and (4), respectively.
(B) Section 36 of such Code is amended by striking “FIRST-TIME HOMEBUYER CREDIT” in the heading and inserting “HOME PURCHASE CREDIT”.
(C) The table of sections for subpart C of part IV of subchapter A of chapter 1 of such Code is amended by striking the item relating to section 36 and inserting the following new item:
“Sec. 36. Home purchase credit.”.
(D) Subparagraph (W) of section 26(b)(2) of such Code is amended by striking “homebuyer credit” and inserting “home purchase credit”.
(b) Elimination of Recapture Except for Homes Sold Within 3 Years.--Subsection (f) of section 36 of the Internal Revenue Code of 1986 is amended to read as follows:
“(f) Recapture of Credit in the Case of Certain Dispositions.--
“(1) In general.--In the event that a taxpayer--
“(A) disposes of the principal residence with respect to which a credit was allowed under subsection (a), or
“(B) fails to occupy such residence as the taxpayer's principal residence, at any time within 36 months after the date on which the taxpayer purchased such residence, then the tax imposed by this chapter for the taxable year during which such disposition occurred or in which the taxpayer failed to occupy the residence as a principal residence shall be increased by the amount of such credit.
“(2) Exceptions.--
“(A) Death of taxpayer.--Paragraph (1) shall not apply to any taxable year ending after the date of the taxpayer's death.
“(B) Involuntary conversion.--Paragraph (1) shall not apply in the case of a residence which is compulsorily or involuntarily converted (within the meaning of section 1033(a)) if the taxpayer acquires a new principal residence within the 2-year period beginning on the date of the disposition or cessation referred to in such paragraph. Paragraph (1) shall apply to such new principal residence during the remainder of the 36-month period described in such paragraph as if such new principal residence were the converted residence.
“(C) Transfers between spouses or incident to divorce.--In the case of a transfer of a residence to which section 1041(a) applies--
“(i) paragraph (1) shall not apply to such transfer, and
“(ii) in the case of taxable years ending after such transfer, paragraph (1) shall apply to the transferee in the same manner as if such transferee were the transferor (and shall not apply to the transferor).
“(D) Relocation of members of the armed forces.--Paragraph (1) shall not apply in the case of a member of the Armed Forces of the United States on active duty who moves pursuant to a military order and incident to a permanent change of station.
“(3) Joint returns.--In the case of a credit allowed under subsection (a) with respect to a joint return, half of such credit shall be treated as having been allowed to each individual filing such return for purposes of this subsection.
“(4) Return requirement.--If the tax imposed by this chapter for the taxable year is increased under this subsection, the taxpayer shall, notwithstanding section 6012, be required to file a return with respect to the taxes imposed under this subtitle.”.
(c) Expansion of Application Period.--Subsection (h) of section 36 of the Internal Revenue Code of 1986 is amended by striking “December 1, 2009” and inserting “June 1, 2010”.
(d) Election To Treat Purchase in Prior Year.--Subsection (g) of section 36 of the Internal Revenue Code of 1986 is amended by striking “December 1, 2009” and inserting “June 1, 2010”.
(e) Elimination of Income Limitation.--Subsection (b) of section 36 of the Internal Revenue Code of 1986 is amended to read as follows:
“(b) Dollar Limitation.--
“(1) In general.--Except as otherwise provided in this subsection, the credit allowed under subsection (a) shall not exceed $8,000.
“(2) Married individuals filing separately.--In the case of a married individual filing a separate return, paragraph (1) shall be applied by substituting ‘$4,000' for ‘$8,000'.
“(3) Other individuals.--If two or more individuals who are not married purchase a principal residence, the amount of the credit allowed under subsection (a) shall be allocated among such individuals in such manner as the Secretary may prescribe, except that the total amount of the credits allowed to all such individuals shall not exceed $8,000.”.
(f) Effective Date.--The amendments made by this section shall apply to residences purchased on or after the date of the enactment of this Act.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Considered by Senate. (consideration: CR S5770)
May 21, 2009
View full timeline
Considered by Senate. (consideration: CR S5770)
May 21, 2009
Point of order raised in Senate with respect to amendment SA 1164.
May 21, 2009
Amendment SA 1164 ruled non-germane by the chair.
May 21, 2009
Senate amendment submitted
May 20, 2009
Senate amendment proposed (on the floor): Amendment SA 1164 proposed by Senator Isakson.(consideration: CR S5666-5667; text CR S5666-5667)
May 20, 2009
Amendment SA 1164 proposed by Senator Isakson. (consideration: CR S5666-5667; text CR S5666-5667) To amend the Internal Revenue Code of 1986 to expand the application of the homebuyer credit, and for other purposes.
May 20, 2009
Amendments
1 amendmentOffered to this amendment
Amendments
1 amendmentOffered to this amendment