S.Amdt. 2391
What it does: Adds SECTION 234. HOME RETENTION AND ECONOMIC STABILIZATION on page 318, between lines 11 and 12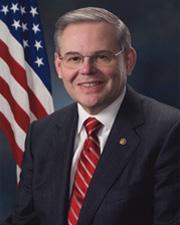 Sen. Robert Menendez (D-NJ)
What it changes
1 change to H.R. 3288
Adds SECTION 234. HOME RETENTION AND ECONOMIC STABILIZATION on page 318, between lines 11 and 12
Adds a sectionPrinted pageInserted: SECTION 234. HOME RETENTION AND ECONOMIC STABILIZATION.
Inserted: (a) Foreclosure Deferment.--Chapter 2 of the Truth in Lending Act (15 U.S.C. 1631 et seq.) is amended by inserting after section 128 the following new section:
Inserted: "Sec. 128A. Foreclosure deferment and reset notification for mortgages
Inserted: "(a) Definitions.--For purposes of this section, the following definitions shall apply:
Inserted: "(1) Deferment payment amount.--The term 'deferment payment amount' means the amount of the monthly payment that is due on an eligible deferred-foreclosure mortgage during the deferment period.
Inserted: "(2) Deferment period.--The term 'deferment period' means the period that--
Inserted: "(A) begins when the eligible consumer sends notice of the exercise of the deferral right under subsection (b)(1) with respect to an eligible deferred-foreclosure mortgage to the creditor or servicer; and
Inserted: "(B) ends on the earliest of the following applicable dates:
Inserted: "(i) The date that is 270 days after the beginning of the period.
Inserted: "(ii) The end of the 30-day period beginning on any due date for any deferment payment (on such mortgage, in accordance with this section) which remains unpaid as of the end of such 30-day period.
Inserted: "(iii) The date on which the creditor or servicer enters into a qualified loan modification with the consumer.
Inserted: "(iv) The date on which the deferment is terminated by judicial order.
Show 71 more inserted paragraphsShow less
Inserted: "(3) Deferment period trigger.--The term 'deferment period trigger' means the date on which the consumer becomes eligible for a deferment under subsection (b)(1) with respect to an eligible deferred-foreclosure mortgage and occurs on the earlier of--
Inserted: "(A) the date of any adjustment or reset of the interest rate on such mortgage;
Inserted: "(B) the date by which the consumer is 60 days delinquent on mortgage payments; or
Inserted: "(C) the date of the first increase in the minimum monthly payment due under such mortgage after the origination of such mortgage.
Inserted: "(4) Eligible deferred-foreclosure mortgage.--The term 'eligible deferred-foreclosure mortgage' means a consumer credit transaction that is secured by the principal dwelling of an eligible consumer that--
Inserted: "(A) was entered into before the date of enactment of this section; and
Inserted: "(B) has reached the deferment period trigger.
Inserted: "(5) Eligible consumer.--The term 'eligible consumer' means a consumer who--
Inserted: "(A) is a mortgagor or borrower on an eligible deferred-foreclosure mortgage;
Inserted: "(B) has resided at the property secured by such mortgage since the mortgage transaction was entered into and intends to reside at such property at least until the end of the deferment period;
Inserted: "(C) has a current monthly income that, when multiplied by 12, is less than 200 percent of the area median annual income for the relevant family size in the State in which the residence is located; and
Inserted: "(D) during the deferment period, responds to reasonable inquiries from a creditor or servicer with respect to an eligible deferred-foreclosure mortgage.
Inserted: "(6) Qualified loan modification.--
Inserted: "(A) In general.--The term 'qualified loan modification' means a permanent, sustainable loan modification.
Inserted: "(B) FDIC regulations.--Not later than 60 days after the date of enactment of the Department of Housing and Urban Development Appropriations Act, 2010, the Chairperson of the Federal Deposit Insurance Corporation shall promulgate rules establishing under what circumstances a loan modification will qualify as permanent and sustainable.
Inserted: "(b) Right to Deferment of Institution of or Action on Foreclosure.--
Inserted: "(1) Right established.--Any eligible deferred-foreclosure consumer shall have the right to defer any initiation of a foreclosure, whether judicial or nonjudicial, or any action in connection with a foreclosure already instituted, including any foreclosure sale, with respect to any eligible deferred-foreclosure mortgage by any creditor, servicer, or holder of such mortgage, or any other person acting on behalf of any such creditor, servicer, or holder, until the end of the deferment period.
Inserted: "(2) Enforcement of right.--An eligible deferred-foreclosure consumer may defend against a foreclosure or bring an action in any court of competent or general jurisdiction to compel compliance with the right of the consumer under paragraph (1) to defer any initiation of a foreclosure or any action in connection with a foreclosure already instituted, including any foreclosure sale, with respect to any eligible deferred-foreclosure mortgage.
Inserted: "(c) Notice to Consumer Before Any Foreclosure Action.--
Inserted: "(1) Notice of right required.--Before initiating any foreclosure with respect to any eligible deferred-foreclosure mortgage, the creditor or servicer shall notify, by personal service, any eligible deferred-foreclosure consumer with respect to such mortgage of such consumer's right under subsection (b) to defer the initiation of foreclosure.
Inserted: "(2) Contents of notice.--The Board shall prescribe, by regulations under sections 105 and 122, the content and format, including the size of the font, of the notices under paragraph (1) in a manner that maximizes the likelihood that the consumer will obtain and understand all the information necessary to exercise the right to defer any action to institute foreclosure, including--
Inserted: "(A) the manner and format for obtaining such deferral, including a sample notice form, an identification form, and a certification form for the consumer to use in complying with subsection (d)(1);
Inserted: "(B) contact information for the creditor or servicer, as the case may be and any third party involved in foreclosure proceedings, including State or local officials; and
Inserted: "(C) contact information for obtaining any counseling concerning the exercise of such deferral from a counselor approved by the appropriate State housing finance agency or the Secretary of Housing and Urban Development.
Inserted: "(3) Timing.--No foreclosure action or proceeding with respect to any eligible deferred-foreclosure mortgage shall be valid unless the creditor or servicer has provided the notice required under this subsection to the consumer at least 30 days before instituting any such action or proceeding and at least once during each subsequent 30-day period until the foreclosure becomes final.
Inserted: "(d) Institution of Deferment.--
Inserted: "(1) Procedure required.--Any eligible deferred-foreclosure consumer who chooses to exercise a deferment right under subsection (b) shall provide--
Inserted: "(A) notice of the exercise of such to the servicer or other person described in the notice to the consumer under subsection (e) by any reasonable means including by mail, service whether directly or to any agent, including at the address of any registered agent;
Inserted: "(B) a clear identification of the eligible deferred-foreclosure consumer and the address of the property securing the mortgage; and
Inserted: "(C) a certification that at least 1 consumer borrower with respect to such mortgage resides at the property secured by such mortgage and intends to reside at such property at least until the end of the deferment period.
Inserted: "(2) Sufficiency of notice.--
Inserted: "(A) In general.--Notice and delivery of an affidavit under paragraph (1) may be made by any reasonable means including by mail, service whether directly or to any agent, including at the address of any registered agent with the secretary of state for the State in which the property is located, or any attorney representing the consumer, or by such means as the terms of the mortgage or regulations prescribed by the Board may provide.
Inserted: "(B) Other parties.--If any court, any sheriff or other official designated under State law, or any other person authorized under State law and the contracts of the parties to maintain any foreclosure proceeding or conduct any foreclosure sale receives, directly or indirectly, a copy of any notice provided under this subsection by an eligible deferred-foreclosure consumer with respect to any eligible deferred-foreclosure mortgage, no foreclosure action may be taken by the court, sheriff, official, or other person with respect to such mortgage during the applicable deferred-foreclosure period.
Inserted: "(3) Acknowledgment.--
Inserted: "(A) In general.--Any creditor, servicer, or holder of an eligible deferred-foreclosure mortgage, or any other person acting on behalf of any such creditor, servicer, or holder, who receives a notice from a consumer under paragraph (2) shall acknowledge to the consumer the receipt of the notice of the exercise of the deferment right under subsection (b) before the end of the 10-business day period beginning on the date of such receipt.
Inserted: "(B) Contents of notice.--The acknowledgment provided to any eligible deferred-foreclosure consumer under subparagraph (A) shall include the date on which the next payment is due on the eligible deferred-foreclosure mortgage, the deferment payment amount, the date on which each subsequent payment is due, and the address or the delivery method for each such payment that is acceptable to the recipient.
Inserted: "(4) Monthly payment notices.--Each periodic statement of account submitted by the creditor or servicer with respect to any eligible deferred-foreclosure mortgage during the period while any deferment right under subsection (b) is in effect shall include--
Inserted: "(A) the due date and the amount of the next payment due on such mortgage;
Inserted: "(B) the address or the delivery method for such payment;
Inserted: "(C) the date on which the deferral of the foreclosure will terminate; and
Inserted: "(D) a notice that failure to make such payment in a timely manner will jeopardize the continuation of the deferral of the foreclosure.
Inserted: "(e) Deferment Payment.--
Inserted: "(1) In general.--During the deferment period with respect to any eligible deferred-foreclosure mortgage for which any deferment right has been exercised under subsection (b), monthly payments shall continue to be made by the consumer with respect to such mortgage.
Inserted: "(2) Amount of payment.--The deferment payment amount for purposes of monthly payments under paragraph (1) with respect to any eligible deferred-foreclosure mortgage shall be, as applicable, the lesser of--
Inserted: "(A) the minimum monthly payment of principal and interest on the date on which the loan was originated;
Inserted: "(B) a monthly payment based on the outstanding loan principal plus a rate of interest calculated at a fixed annual percentage rate, in an amount equal to the most recent conventional mortgage rate plus a 100 basis point premium for risk, amortized over a period of 30 years minus the period of time since the origination of the loan; or
Inserted: "(C) the amount of the first minimum monthly payment due under the mortgage after the origination of such mortgage.
Inserted: "(3) Amortization of difference.--The difference between the amount of any monthly payment due under the terms of any eligible deferred-foreclosure mortgage and the deferment payment amount shall be amortized over the life of the mortgage beginning after the deferred-foreclosure period in accordance with regulations which the Board shall prescribe.
Inserted: "(4) Charges prohibited.--No creditor or servicer may impose any late fee or other fee or charge during the deferment period with respect to any eligible deferred-foreclosure mortgage for which any deferment right has been exercised under subsection (b) or in connection with the exercise of such deferment right.
Inserted: "(f) Notice of Reset and Alternatives.--During the 1-month period that ends 120 days before the date on which the interest rate in effect during the introductory period of an eligible deferred-foreclosure mortgage adjusts or resets to a variable interest rate, or the minimum monthly payment of principal and interest required first increases from the amount of the first such minimum monthly payment due under the mortgage after the origination of such mortgage, the creditor or servicer of such loan shall provide a written notice, separate and distinct from all other correspondence to the consumer, that includes the following:
Inserted: "(1) Any index or formula used--
Inserted: "(A) in determining the annual percentage rate applicable as of the effective date of a reset or adjustment; and
Inserted: "(B) in making any increases in the minimum monthly payments due, and a source of information about the index or formula.
Inserted: "(2) A good faith estimate, based on accepted industry standards and disclosed in a clear and conspicuous manner, of the creditor or servicer of the amount of the monthly payment that will apply after the date of the adjustment or reset, or increase, as applicable, and the assumptions on which this estimate is based.
Inserted: "(3) A list of alternatives consumers may pursue before the date of adjustment or reset, or increase, as applicable, and descriptions of the actions consumers must take to pursue such alternatives, including--
Inserted: "(A) refinancing;
Inserted: "(B) renegotiation of loan terms;
Inserted: "(C) payment forbearance;
Inserted: "(D) pre-foreclosure sales;
Inserted: "(E) any payment assistance available from the State in which the property is located; and
Inserted: "(F) any refinancing, loan modification, or other assistance program available through the Federal Government that may apply to the loan.
Inserted: "(4) The names, addresses, telephone numbers, and Internet addresses of counseling agencies or programs reasonably available to the consumer that have been certified or approved and made publicly available by the Secretary of Housing and Urban Development or a State housing finance authority (as defined in section 1301 of the Financial Institutions Reform, Recovery, and Enforcement Act of 1989).
Inserted: "(5) The address, telephone number, and Internet address for the State housing finance authority (as so defined) for the State in which the consumer resides.
Inserted: "(g) Most Recent Conventional Mortgage Rate.--For purposes of subsection (f)(1)(A)(ii), the term 'most recent conventional mortgage rate' means the contract interest rate on commitments for fixed-rate first mortgages most recently published in the Federal Reserve Statistical Release on selected interest rates (daily or weekly), and commonly referred to as the H.15 release (or any successor publication), in the week preceding a date of determination for purposes of applying this subsection.
Inserted: "(h) Duty of Consumer To Maintain Property.--Any eligible deferred-foreclosure consumer for whom a deferment of foreclosure is in effect under this section with respect to any eligible deferred-foreclosure mortgage may not, with respect to any property securing such mortgage, destroy, damage, or impair such property, allow the property to substantially deteriorate, or commit waste on the property.
Inserted: "(i) Declaration of Rights.--In addition to the right of any party to a mortgage to seek a declaratory judgment under section 2201 of title 28, United States Code, any such party may apply prior to the end of the deferment period to any State court of competent or general jurisdiction for an order establishing the rights, duties, and conditions imposed on or applicable to any party to the mortgage, including the terms and conditions of a deferment.
Inserted: "(j) Coordination With State Law.--
Inserted: "(1) In general.--No provision of this section shall be construed as annulling, altering, or affecting the laws of any State relating to deferment of foreclosures, except to the extent that those laws are inconsistent with the provisions of this section, and then only to the extent of the inconsistency.
Inserted: "(2) Rule of construction.--A State law is not inconsistent with this section if the protection that such law affords any consumer is greater than the protection afforded by this section.".
Inserted: (b) Clerical Amendment.--The table of sections for chapter 2 of the Truth in Lending Act is amended by inserting after the item relating to section 128 the following new item:
Inserted: "128A. Foreclosure deferment and reset notification for certain mortgages.".
Original wording
On page 318, between lines 11 and 12, insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 2391. Mr. MENENDEZ submitted an amendment intended to be proposed by him to the bill H.R. 3288, making appropriations for the Departments of Transportation, and Housing and Urban Development, and related agencies for the fiscal year ending September 30, 2010, and for other purposes; which was ordered to lie on the table; as follows:
On page 318, between lines 11 and 12, insert the following:
SECTION 234. HOME RETENTION AND ECONOMIC STABILIZATION.
(a) Foreclosure Deferment.--Chapter 2 of the Truth in Lending Act (15 U.S.C. 1631 et seq.) is amended by inserting after section 128 the following new section:
“Sec. 128A. Foreclosure deferment and reset notification for
mortgages
“(a) Definitions.--For purposes of this section, the following definitions shall apply:
“(1) Deferment payment amount.--The term ‘deferment payment amount' means the amount of the monthly payment that is due on an eligible deferred-foreclosure mortgage during the deferment period.
“(2) Deferment period.--The term ‘deferment period' means the period that--
“(A) begins when the eligible consumer sends notice of the exercise of the deferral right under subsection (b)(1) with respect to an eligible deferred-foreclosure mortgage to the creditor or servicer; and
“(B) ends on the earliest of the following applicable dates:
“(i) The date that is 270 days after the beginning of the period.
“(ii) The end of the 30-day period beginning on any due date for any deferment payment (on such mortgage, in accordance with this section) which remains unpaid as of the end of such 30-day period.
“(iii) The date on which the creditor or servicer enters into a qualified loan modification with the consumer.
“(iv) The date on which the deferment is terminated by judicial order.
“(3) Deferment period trigger.--The term ‘deferment period trigger' means the date on which the consumer becomes eligible for a deferment under subsection (b)(1) with respect to an eligible deferred-foreclosure mortgage and occurs on the earlier of--
“(A) the date of any adjustment or reset of the interest rate on such mortgage;
“(B) the date by which the consumer is 60 days delinquent on mortgage payments; or
“(C) the date of the first increase in the minimum monthly payment due under such mortgage after the origination of such mortgage.
“(4) Eligible deferred-foreclosure mortgage.--The term ‘eligible deferred-foreclosure mortgage' means a consumer credit transaction that is secured by the principal dwelling of an eligible consumer that--
“(A) was entered into before the date of enactment of this section; and
“(B) has reached the deferment period trigger.
“(5) Eligible consumer.--The term ‘eligible consumer' means a consumer who--
“(A) is a mortgagor or borrower on an eligible deferred-foreclosure mortgage;
“(B) has resided at the property secured by such mortgage since the mortgage transaction was entered into and intends to reside at such property at least until the end of the deferment period;
“(C) has a current monthly income that, when multiplied by 12, is less than 200 percent of the area median annual income for the relevant family size in the State in which the residence is located; and
“(D) during the deferment period, responds to reasonable inquiries from a creditor or servicer with respect to an eligible deferred-foreclosure mortgage.
“(6) Qualified loan modification.--
“(A) In general.--The term ‘qualified loan modification' means a permanent, sustainable loan modification.
“(B) FDIC regulations.--Not later than 60 days after the date of enactment of the Department of Housing and Urban Development Appropriations Act, 2010, the Chairperson of the Federal Deposit Insurance Corporation shall promulgate rules establishing under what circumstances a loan modification will qualify as permanent and sustainable.
“(b) Right to Deferment of Institution of or Action on Foreclosure.--
“(1) Right established.--Any eligible deferred-foreclosure consumer shall have the right to defer any initiation of a foreclosure, whether judicial or nonjudicial, or any action in connection with a foreclosure already instituted, including any foreclosure sale, with respect to any eligible deferred-foreclosure mortgage by any creditor, servicer, or holder of such mortgage, or any other person acting on behalf of any such creditor, servicer, or holder, until the end of the deferment period.
“(2) Enforcement of right.--An eligible deferred-foreclosure consumer may defend against a foreclosure or bring an action in any court of competent or general jurisdiction to compel compliance with the right of the consumer under paragraph (1) to defer any initiation of a foreclosure or any action in connection with a foreclosure already instituted, including any foreclosure sale, with respect to any eligible deferred-foreclosure mortgage.
“(c) Notice to Consumer Before Any Foreclosure Action.--
“(1) Notice of right required.--Before initiating any foreclosure with respect to any eligible deferred-foreclosure mortgage, the creditor or servicer shall notify, by personal service, any eligible deferred-foreclosure consumer with respect to such mortgage of such consumer's right under subsection (b) to defer the initiation of foreclosure.
“(2) Contents of notice.--The Board shall prescribe, by regulations under sections 105 and 122, the content and format, including the size of the font, of the notices under paragraph (1) in a manner that maximizes the likelihood that the consumer will obtain and understand all the information necessary to exercise the right to defer any action to institute foreclosure, including--
“(A) the manner and format for obtaining such deferral, including a sample notice form, an identification form, and a certification form for the consumer to use in complying with subsection (d)(1);
“(B) contact information for the creditor or servicer, as the case may be and any third party involved in foreclosure proceedings, including State or local officials; and
“(C) contact information for obtaining any counseling concerning the exercise of such deferral from a counselor approved by the appropriate State housing finance agency or the Secretary of Housing and Urban Development.
“(3) Timing.--No foreclosure action or proceeding with respect to any eligible deferred-foreclosure mortgage shall be valid unless the creditor or servicer has provided the notice required under this subsection to the consumer at least 30 days before instituting any such action or proceeding and at least once during each subsequent 30-day period until the foreclosure becomes final.
“(d) Institution of Deferment.--
“(1) Procedure required.--Any eligible deferred-foreclosure consumer who chooses to exercise a deferment right under subsection (b) shall provide--
“(A) notice of the exercise of such to the servicer or other person described in the notice to the consumer under subsection (e) by any reasonable means including by mail, service whether directly or to any agent, including at the address of any registered agent;
“(B) a clear identification of the eligible deferred-foreclosure consumer and the address of the property securing the mortgage; and
“(C) a certification that at least 1 consumer borrower with respect to such mortgage resides at the property secured by such mortgage and intends to reside at such property at least until the end of the deferment period.
“(2) Sufficiency of notice.--
“(A) In general.--Notice and delivery of an affidavit under paragraph (1) may be made by any reasonable means including by mail, service whether directly or to any agent, including at the address of any registered agent with the secretary of state for the State in which the property is located, or any attorney representing the consumer, or by such means as the terms of the mortgage or regulations prescribed by the Board may provide.
“(B) Other parties.--If any court, any sheriff or other official designated under State law, or any other person authorized under State law and the contracts of the parties to maintain any foreclosure proceeding or conduct any foreclosure sale receives, directly or indirectly, a copy of any notice provided under this subsection by an eligible deferred-foreclosure consumer with respect to any eligible deferred-foreclosure mortgage, no foreclosure action may be taken by the court, sheriff, official, or other person with respect to such mortgage during the applicable deferred-foreclosure period.
“(3) Acknowledgment.--
“(A) In general.--Any creditor, servicer, or holder of an eligible deferred-foreclosure mortgage, or any other person acting on behalf of any such creditor, servicer, or holder, who receives a notice from a consumer under paragraph (2) shall acknowledge to the consumer the receipt of the notice of the exercise of the deferment right under subsection (b) before the end of the 10-business day period beginning on the date of such receipt.
“(B) Contents of notice.--The acknowledgment provided to any eligible deferred-foreclosure consumer under subparagraph (A) shall include the date on which the next payment is due on the eligible deferred-foreclosure mortgage, the deferment payment amount, the date on which each subsequent payment is due, and the address or the delivery method for each such payment that is acceptable to the recipient.
“(4) Monthly payment notices.--Each periodic statement of account submitted by the creditor or servicer with respect to any eligible deferred-foreclosure mortgage during the period while any deferment right under subsection (b) is in effect shall include--
“(A) the due date and the amount of the next payment due on such mortgage;
“(B) the address or the delivery method for such payment;
“(C) the date on which the deferral of the foreclosure will terminate; and
“(D) a notice that failure to make such payment in a timely manner will jeopardize the continuation of the deferral of the foreclosure.
“(e) Deferment Payment.--
“(1) In general.--During the deferment period with respect to any eligible deferred-foreclosure mortgage for which any deferment right has been exercised under subsection (b), monthly payments shall continue to be made by the consumer with respect to such mortgage.
“(2) Amount of payment.--The deferment payment amount for purposes of monthly payments under paragraph (1) with respect to any eligible deferred-foreclosure mortgage shall be, as applicable, the lesser of--
“(A) the minimum monthly payment of principal and interest on the date on which the loan was originated;
“(B) a monthly payment based on the outstanding loan principal plus a rate of interest calculated at a fixed annual percentage rate, in an amount equal to the most recent conventional mortgage rate plus a 100 basis point premium for risk, amortized over a period of 30 years minus the period of time since the origination of the loan; or
“(C) the amount of the first minimum monthly payment due under the mortgage after the origination of such mortgage.
“(3) Amortization of difference.--The difference between the amount of any monthly payment due under the terms of any eligible deferred-foreclosure mortgage and the deferment payment amount shall be amortized over the life of the mortgage beginning after the deferred-foreclosure period in accordance with regulations which the Board shall prescribe.
“(4) Charges prohibited.--No creditor or servicer may impose any late fee or other fee or charge during the deferment period with respect to any eligible deferred-foreclosure mortgage for which any deferment right has been exercised under subsection (b) or in connection with the exercise of such deferment right.
“(f) Notice of Reset and Alternatives.--During the 1-month period that ends 120 days before the date on which the interest rate in effect during the introductory period of an eligible deferred-foreclosure mortgage adjusts or resets to a variable interest rate, or the minimum monthly payment of principal and interest required first increases from the amount of the first such minimum monthly payment due under the mortgage after the origination of such mortgage, the creditor or servicer of such loan shall provide a written notice, separate and distinct from all other correspondence to the consumer, that includes the following:
“(1) Any index or formula used--
“(A) in determining the annual percentage rate applicable as of the effective date of a reset or adjustment; and
“(B) in making any increases in the minimum monthly payments due, and a source of information about the index or formula.
“(2) A good faith estimate, based on accepted industry standards and disclosed in a clear and conspicuous manner, of the creditor or servicer of the amount of the monthly payment that will apply after the date of the adjustment or reset, or increase, as applicable, and the assumptions on which this estimate is based.
“(3) A list of alternatives consumers may pursue before the date of adjustment or reset, or increase, as applicable, and descriptions of the actions consumers must take to pursue such alternatives, including--
“(A) refinancing;
“(B) renegotiation of loan terms;
“(C) payment forbearance;
“(D) pre-foreclosure sales;
“(E) any payment assistance available from the State in which the property is located; and
“(F) any refinancing, loan modification, or other assistance program available through the Federal Government that may apply to the loan.
“(4) The names, addresses, telephone numbers, and Internet addresses of counseling agencies or programs reasonably available to the consumer that have been certified or approved and made publicly available by the Secretary of Housing and Urban Development or a State housing finance authority (as defined in section 1301 of the Financial Institutions Reform, Recovery, and Enforcement Act of 1989).
“(5) The address, telephone number, and Internet address for the State housing finance authority (as so defined) for the State in which the consumer resides.
“(g) Most Recent Conventional Mortgage Rate.--For purposes of subsection (f)(1)(A)(ii), the term ‘most recent conventional mortgage rate' means the contract interest rate on commitments for fixed-rate first mortgages most recently published in the Federal Reserve Statistical Release on selected interest rates (daily or weekly), and commonly referred to as the H.15 release (or any successor publication), in the week preceding a date of determination for purposes of applying this subsection.
“(h) Duty of Consumer To Maintain Property.--Any eligible deferred-foreclosure consumer for whom a deferment of foreclosure is in effect under this section with respect to any eligible deferred-foreclosure mortgage may not, with respect to any property securing such mortgage, destroy, damage, or impair such property, allow the property to substantially deteriorate, or commit waste on the property.
“(i) Declaration of Rights.--In addition to the right of any party to a mortgage to seek a declaratory judgment under section 2201 of title 28, United States Code, any such party may apply prior to the end of the deferment period to any State court of competent or general jurisdiction for an order establishing the rights, duties, and conditions imposed on or applicable to any party to the mortgage, including the terms and conditions of a deferment.
“(j) Coordination With State Law.--
“(1) In general.--No provision of this section shall be construed as annulling, altering, or affecting the laws of any State relating to deferment of foreclosures, except to the extent that those laws are inconsistent with the provisions of this section, and then only to the extent of the inconsistency.
“(2) Rule of construction.--A State law is not inconsistent with this section if the protection that such law affords any consumer is greater than the protection afforded by this section.”.
(b) Clerical Amendment.--The table of sections for chapter 2 of the Truth in Lending Act is amended by inserting after the item relating to section 128 the following new item:
“128A. Foreclosure deferment and reset notification for certain mortgages.”.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
September 15, 2009