S.Amdt. 3740
What it does: Adds SEC. 1077. NATIONAL CONSUMER CREDIT USURY RATE at the end of subtitle G of title X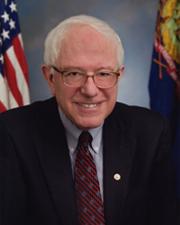 Sen. Bernard Sanders (I-VT)
What it changes
1 change to S. 3217
Adds SEC. 1077. NATIONAL CONSUMER CREDIT USURY RATE at the end of subtitle G of title X
Adds a sectionInserted: SEC. 1077. NATIONAL CONSUMER CREDIT USURY RATE.
Inserted: (a) In General.--Section 107 of the Truth in Lending Act (15 U.S.C. 1606) is amended by adding at the end the following new subsection:
Inserted: "(f) National Consumer Credit Usury Rate.--
Inserted: "(1) Limitation established.--Except as provided in paragraph (2), and notwithstanding subsection (a) or any other provision of law, the annual percentage rate applicable to an extension of credit obtained by use of a credit card may not exceed 15 percent on unpaid balances, inclusive of all finance charges. Any fees that are not considered finance charges under section 106(a) may not be used to evade the limitations of this paragraph, and the total sum of such fees may not exceed the total amount of finance charges assessed.
Inserted: "(2) Exceptions.--
Inserted: "(A) Bureau authority.--The Bureau may establish, after consultation with the appropriate committees of Congress, the Secretary of the Treasury, and any other interested Federal financial institution regulatory agency, an annual percentage rate of interest ceiling exceeding the 15 percent annual rate under paragraph (1) for periods not to exceed 18 months, upon a determination that--
Inserted: "(i) money market interest rates have risen over the preceding 6-month period; or
Inserted: "(ii) prevailing interest rate levels threaten the safety and soundness of individual lenders, as evidenced by adverse trends in liquidity, capital, earnings, and growth.
Inserted: "(B) Treatment of credit unions.--The limitation in paragraph (1) does not apply with respect to any extension of credit by an insured credit union, as that term is defined in section 101 of the Federal Credit Union Act (12 U.S.C. 1752).".
Original wording
At the end of subtitle G of title X, add the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 3740. Mr. SANDERS (for himself, Mr. Leahy, Mr. Harkin, Mr. Whitehouse, and Mr. Begich) submitted an amendment intended to be proposed by him to the bill S. 3217, to promote the financial stability of the United States by improving accountability and transparency in the financial system, to end “too big to fail”, to protect the American taxpayer by ending bailouts, to protect consumers from abusive financial services practices, and for other purposes; which was ordered to lie on the table; as follows:
At the end of subtitle G of title X, add the following:
SEC. 1077. NATIONAL CONSUMER CREDIT USURY RATE.
(a) In General.--Section 107 of the Truth in Lending Act (15 U.S.C. 1606) is amended by adding at the end the following new subsection:
“(f) National Consumer Credit Usury Rate.--
“(1) Limitation established.--Except as provided in paragraph (2), and notwithstanding subsection (a) or any other provision of law, the annual percentage rate applicable to an extension of credit obtained by use of a credit card may not exceed 15 percent on unpaid balances, inclusive of all finance charges. Any fees that are not considered finance charges under section 106(a) may not be used to evade the limitations of this paragraph, and the total sum of such fees may not exceed the total amount of finance charges assessed.
“(2) Exceptions.--
“(A) Bureau authority.--The Bureau may establish, after consultation with the appropriate committees of Congress, the Secretary of the Treasury, and any other interested Federal financial institution regulatory agency, an annual percentage rate of interest ceiling exceeding the 15 percent annual rate under paragraph (1) for periods not to exceed 18 months, upon a determination that--
“(i) money market interest rates have risen over the preceding 6-month period; or
“(ii) prevailing interest rate levels threaten the safety and soundness of individual lenders, as evidenced by adverse trends in liquidity, capital, earnings, and growth.
“(B) Treatment of credit unions.--The limitation in paragraph (1) does not apply with respect to any extension of credit by an insured credit union, as that term is defined in section 101 of the Federal Credit Union Act (12 U.S.C. 1752).”.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
April 29, 2010