S.Amdt. 4491
What it does: Adds TITLE _--RESPONSIBLE ESTATE TAX REFORM at the end of S.Amdt. 4402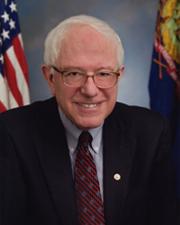 Sen. Bernard Sanders (I-VT)
What it changes
1 change to S.Amdt. 4402 · shown in S.Amdt. 4402's text
Adds TITLE _--RESPONSIBLE ESTATE TAX REFORM at the end of S.Amdt. 4402
Adds a titleIn S.Amdt. 4402 as proposed
The budgetary effects of this Act, for the purpose of complying with the Statutory Pay-As-You-Go Act of 2010, shall be determined by reference to the latest statement titled "Budgetary Effects of PAYGO Legislation" for this Act, submitted for printing in the Congressional Record by the Chairman of the Senate Budget Committee, provided that such statement has been submitted prior to the vote on passage.
Inserted: TITLE _--RESPONSIBLE ESTATE TAX REFORM
Inserted: SEC. __01. SHORT TITLE.
Inserted: This title may be cited as the "Responsible Estate Tax Act".
Inserted: SEC. __02. REINSTATEMENT AND EXTENSION OF ESTATE AND GENERATION-SKIPPING TAXES; REPEAL OF CARRYOVER BASIS.
Inserted: (a) In General.--The following provisions of the Economic Growth and Tax Relief Reconciliation Act of 2001, and the amendments made by such provisions, are hereby repealed effective December 31, 2009:
Inserted: (1) Subtitles A and E of title V.
Inserted: (2) Subsection (d), and so much of subsection (f)(3) as relates to subsection (d), of section 511.
Inserted: (3) Paragraph (2) of subsection (b), and paragraph (2) of subsection (e), of section 521.
Inserted: Any provision of the Internal Revenue Code of 1986 amended by such provisions are amended to read as such provisions would read if such sections had never been enacted.
Inserted: (b) Conforming Amendment.--Subsection (c) of section 2511 of the Internal Revenue Code of 1986 is hereby repealed effective December 31, 2009.
Inserted: (c) Sunset Not to Apply.--
Inserted: (1) Subsection (a) of section 901 of the Economic Growth and Tax Relief Reconciliation Act of 2001 is amended by striking "this Act" and all that follows and inserting "this Act (other than title V) shall not apply to taxable, plan, or limitation years beginning after December 31, 2010.".
Show 125 more inserted paragraphsShow less
Inserted: (2) Subsection (b) of such section 901 is amended by striking ", estates, gifts, and transfers".
Inserted: (d) Transition Rules.--Notwithstanding any provision of the Internal Revenue Code of 1986, in the case of decedent dying or a transfer made after December 31, 2009, and before the date of the enactment of this Act--
Inserted: (1) the due date for any return under section 6018 or 6019 of such Code (including any election required to be made on such a return) and any payment of tax under chapter 11, 12, or 13 of such Code shall be the later of--
Inserted: (A) the date that is 4 months after the date of the enactment of this Act, or
Inserted: (B) the date otherwise required by law (determined without regard to this subsection), and
Inserted: (2) any disclaimer of an interest in property shall be treated as a qualified disclaimer under section 2518 of such Code if such disclaimer meets the requirements of paragraphs (1), (3), and (4) of section 2518(b) of such Code and is received in writing by a person described in section 2518(b)(2) of such Code not later than--
Inserted: (A) the date that is 4 months after the date of the enactment of this Act, or
Inserted: (B) the date otherwise required under section 2518(b)(2) of such Code.
Inserted: SEC. __03. MODIFICATION OF RATES AND MAINTENANCE OF UNIFIED CREDIT AGAINST THE ESTATE TAX.
Inserted: (a) Modification of Rates.--
Inserted: (1) In general.--The table in paragraph (1) of section 2001(c) of the Internal Revenue Code of 1986 is amended by striking the last 6 rows and inserting the following:
Inserted: "Over $750,000 but not over $3,500,000... $248,300 plus 39 percent of the excess of such amount over $750,000 Over $3,500,000 but not over $10,000,000.. $1,320,800 plus 45 percent of the excess of such amount over $3,500,000 Over $10,000,000 but not over $50,000,000. $4,245,800 plus 50 percent of the excess of such amount over $10,000,000 Over $50,000,000.......................... $24,245,800 plus 55 percent of the excess of such amount over $50,000,000".
Inserted: (2) Surtax on wealthy estates.--Paragraph (2) of section 2001(c) of such Code is amended to read as follows:
Inserted: "(2) Surtax on estates over $500,000,000.--Notwithstanding paragraph (1), if the amount with respect to which the tentative tax to be computed is over $500,000,000, the rate of tax otherwise in effect under this subsection with respect to the amount in excess of $500,000,000 shall be increased by 10 percentage points.".
Inserted: (b) Extension of Applicable 2009 Credit Amounts.--The table in subsection (c) of section 2010 of the Internal Revenue Code of 1986 (relating to applicable credit amount) is amended by inserting "and thereafter" after "2009".
Inserted: (c) Effective Date.--The amendments made by this section shall apply to estates of decedents dying, and gifts made, after December 31, 2009.
Inserted: SEC. __04. MODIFICATION OF RULES FOR VALUE OF CERTAIN FARM, ETC., REAL PROPERTY.
Inserted: (a) In General.--Paragraph (2) of section 2032A(a) of the Internal Revenue Code of 1986 is amended by striking "$750,000" and inserting "$3,000,000".
Inserted: (b) Inflation Adjustment.--Paragraph (3) of section 2032A(a) of such Code is amended--
Inserted: (1) by striking "1998" and inserting "2009",
Inserted: (2) by striking "$750,000" and inserting "$3,000,000" in subparagraph (A), and
Inserted: (3) by striking "calendar year 1997" and inserting "calendar year 2008" in subparagraph (B).
Inserted: (c) Effective Date.--The amendments made by this section shall apply to estates of decedents dying, and gifts made, after December 31, 2009.
Inserted: SEC. __05. MODIFICATION OF ESTATE TAX RULES WITH RESPECT TO LAND SUBJECT TO CONSERVATION EASEMENTS.
Inserted: (a) Modification of Exclusion Limitation.--The table in paragraph (3) of section 2031(c) of the Internal Revenue Code of 1986 is amended--
Inserted: (1) by striking "or thereafter" in the last row and inserting "through 2009", and
Inserted: (2) by adding at the end the following row:
Inserted: "2010 and thereafter................................ $2,000,000".
Inserted: (b) Modification of Applicable Percentage.--Paragraph (2) of section 2031(c) of the Internal Revenue Code of 1986 is amended by striking "40 percent" and inserting "60 percent".
Inserted: (c) Effective Date.--The amendments made by this section shall apply to estates of decedents dying, and gifts made, after December 31, 2009.
Inserted: SEC. __06. CONSISTENT BASIS REPORTING BETWEEN ESTATE AND PERSON ACQUIRING PROPERTY FROM DECEDENT.
Inserted: (a) Information Reporting.--
Inserted: (1) In general.--Subpart A of part III of subchapter A of chapter 61 of the Internal Revenue Code of 1986 is amended by inserting after section 6034A the following new section:
Inserted: "SEC. 6035. BASIS INFORMATION TO PERSONS ACQUIRING PROPERTY FROM DECEDENT OR BY GIFT.
Inserted: "(a) Information With Respect to Property Acquired From Decedents.--
Inserted: "(1) In general.--The executor of any estate required to file a return under section 6018(a) shall furnish to the Secretary and to each person acquiring any interest in property included in the decedent's gross estate for federal estate tax purposes a statement identifying--
Inserted: "(A) the fair market value of each interest in such property acquired by such person as reported on such return,
Inserted: "(B) in the case of any property to which the exclusion under section 2031(c) applies or to which section 1014(e) applies, the adjusted basis of such property in the hands of the decedent,
Inserted: "(C) in the case of any property which consists of stock in a DISC or former DISC (as defined in section 992(a)), the basis of the decedent in such stock reduced by the amount (if any) which would have been included in gross income under section 995(c) as a dividend if the decedent had lived and sold the stock at its fair market value on the estate tax valuation date (determined under the rules of section 1014(d)), and
Inserted: "(D) such other information with respect to such interest as the Secretary may prescribe.
Inserted: "(2) Statements by beneficiaries.--Any person required to file a return under section 6018(b) shall furnish to the Secretary and to each other person who holds a legal or beneficial interest in the property to which such return relates a statement identifying the information described in paragraph (1).
Inserted: "(3) Time for furnishing statement.--
Inserted: "(A) In general.--Any statement required to be filed under paragraph (1) or (2) shall be filed not later than the earlier of--
Inserted: "(i) the date which is 30 days after the date on which such return was required to be filed (including extensions, if any), or
Inserted: "(ii) the date which is 30 days after the date such return is filed.
Inserted: "(B) Adjustments.--In any case in which there is an adjustment to the information required to be included on a statement filed under paragraph (1) or (2) after such statement has been filed, a supplemental statement under such paragraph shall be filed not later than the date which is 30 days after such adjustment is made.
Inserted: "(b) Information With Respect to Property Acquired by Gift.--
Inserted: "(1) In general.--Each person making a transfer by gift who is required to file a return under section 6019 with respect to such transfer shall furnish to the Secretary and to each person acquiring any interest in property by reason of such transfer a statement identifying--
Inserted: "(A) the donor's adjusted basis in each interest in property acquired by such person,
Inserted: "(B) the fair market value of each interest in such property at the time of the transfer as reported return,
Inserted: "(C) in the case of a transfer in trust, the amount of the gain or loss recognized by the grantor on such transfer,
Inserted: "(D) the amount, if any, of gift tax paid by the transferor with respect to such interest, and
Inserted: "(E) such other information with respect to such interest as the Secretary may prescribe.
Inserted: "(2) Time for furnishing statement.--
Inserted: "(A) In general.--Any statement required to be filed under paragraph (1) shall be filed not later than the earlier of--
Inserted: "(i) the date which is 30 days after the date on which such return was required to be filed (including extensions, if any), or
Inserted: "(ii) the date which is 30 days after the date such return is filed.
Inserted: "(B) Adjustments.--In any case in which there is an adjustment to the information required to be included on a statement filed under paragraph (1) after such statement has been filed, a supplemental statement under such paragraph shall be filed not later than the date which is 30 days after such adjustment is made.
Inserted: "(c) Regulations.--The Secretary shall prescribe such regulations as necessary to carry out this section, including regulations relating to--
Inserted: "(1) the application of this section to property with regard to which no estate or gift tax return is required to be filed, and
Inserted: "(2) situations in which the surviving joint tenant or other recipient may have better information than the executor regarding the basis or fair market value of the property.".
Inserted: (2) Penalty for failure to file.--
Inserted: (A) Return.--Subparagraph (B) of section 6724(d)(1) of the Internal Revenue Code of 1986 is amended by striking "or" at the end of clause (xxiv), by striking "and" at the end of clause (xxv) and inserting "or", and by adding at the end the following new clause:
Inserted: "(xxvi) section 6035 (relating to returns relating to basis information to persons acquiring property from decedent or by gift), and".
Inserted: (B) Statement.--Subparagraph (A) of section 6724(d)(2)(A) of such Code is amended by inserting "6035," after "6034A,".
Inserted: (3) Clerical amendment.--The table of sections for subpart A of part III of subchapter A of chapter 61 of the Internal Revenue Code of 1986 is amended by inserting after the item relating to section 6034A the following new item:
Inserted: "Sec. 6035. Basis information to persons acquiring property from decedent or by gift.".
Inserted: (b) Consistent Use of Basis.--
Inserted: (1) Property acquired from a decedent.--Section 1014 of the Internal Revenue Code of 1986 is amended by adding at the end the following new subsection:
Inserted: "(f) Basis Must Be Consistent With Information Reports.--Except as provided by the Secretary in regulations, in any case in which the executor of the estate was required to make a return under section 6035, the basis of an interest in property in the hands of the person acquiring such property shall not exceed--
Inserted: "(1) except as provided in paragraph (2), shall not exceed the value of such interest as determined for purposes of chapter 11, and
Inserted: "(2) in the case of property to which subsection (a)(4) or (d) applies, shall be calculated using the information reported to such person under section 6035(a).".
Inserted: (2) Property acquired by gifts and transfers in trust.--Section 1015 of the Internal Revenue Code of 1986 is amended by adding at the end the following new subsection:
Inserted: "(f) Basis Must Be Consistent With Information Reports.--Except as provided by the Secretary in regulations, in any case in which the transferor was required to make a return under section 6035, the basis of the property in the hands of the person acquiring such property shall be calculated using the information reported to such person under section 6035(b).".
Inserted: (c) Penalty for Inconsistent Reporting.--
Inserted: (1) In general.--Subsection (b) of section 6662 of the Internal Revenue Code of 1986 is amended by inserting after paragraph (7) the following new paragraph:
Inserted: "(8) Any inconsistent estate or gift basis reporting.".
Inserted: (2) Inconsistent basis reporting.--Section 6662 of such Code is amended by adding at the end the following new subsection:
Inserted: "(k) Inconsistent Estate or Gift Basis Reporting.--For purposes of this section, the term 'inconsistent estate or gift basis reporting' means the portion of the understatement which is attributable to the failure by the taxpayer to use the information reported to such taxpayer under section 6035 in calculating the basis of any property acquired from a decedent or by gift or transfer in trust.".
Inserted: (d) Effective Date.--The amendments made by this section shall apply to transfers for which returns are filed after the date of the enactment of this Act.
Inserted: SEC. __07. VALUATION RULES FOR CERTAIN TRANSFERS OF NONBUSINESS ASSETS; LIMITATION ON MINORITY DISCOUNTS.
Inserted: (a) In General.--Section 2031 of the Internal Revenue Code of 1986 (relating to definition of gross estate) is amended by redesignating subsection (d) as subsection (f) and by inserting after subsection (c) the following new subsections:
Inserted: "(d) Valuation Rules for Certain Transfers of Nonbusiness Assets.--For purposes of this chapter and chapter 12--
Inserted: "(1) In general.--In the case of the transfer of any interest in an entity other than an interest which is actively traded (within the meaning of section 1092)--
Inserted: "(A) the value of any nonbusiness assets held by the entity with respect to such interest shall be determined as if the transferor had transferred such assets directly to the transferee (and no valuation discount shall be allowed with respect to such nonbusiness assets), and
Inserted: "(B) such nonbusiness assets shall not be taken into account in determining the value of the interest in the entity.
Inserted: "(2) Nonbusiness assets.--For purposes of this subsection--
Inserted: "(A) In general.--The term 'nonbusiness asset' means any asset which is not used in the active conduct of 1 or more trades or businesses.
Inserted: "(B) Exception for certain passive assets.--Except as provided in subparagraph (C), a passive asset shall not be treated for purposes of subparagraph (A) as used in the active conduct of a trade or business unless--
Inserted: "(i) the asset is property described in paragraph (1) or (4) of section 1221(a) or is a hedge with respect to such property, or
Inserted: "(ii) the asset is real property used in the active conduct of 1 or more real property trades or businesses (within the meaning of section 469(c)(7)(C)) in which the transferor materially participates and with respect to which the transferor meets the requirements of section 469(c)(7)(B)(ii).
Inserted: For purposes of clause (ii), material participation shall be determined under the rules of section 469(h), except that section 469(h)(3) shall be applied without regard to the limitation to farming activity.
Inserted: "(C) Exception for working capital.--Any asset (including a passive asset) which is held as a part of the reasonably required working capital needs of a trade or business shall be treated as used in the active conduct of a trade or business.
Inserted: "(3) Passive asset.--For purposes of this subsection, the term 'passive asset' means any--
Inserted: "(A) cash or cash equivalents,
Inserted: "(B) except to the extent provided by the Secretary, stock in a corporation or any other equity, profits, or capital interest in any entity,
Inserted: "(C) evidence of indebtedness, option, forward or futures contract, notional principal contract, or derivative,
Inserted: "(D) asset described in clause (iii), (iv), or (v) of section 351(e)(1)(B),
Inserted: "(E) annuity,
Inserted: "(F) real property used in 1 or more real property trades or businesses (as defined in section 469(c)(7)(C)),
Inserted: "(G) asset (other than a patent, trademark, or copyright) which produces royalty income,
Inserted: "(H) commodity,
Inserted: "(I) collectible (within the meaning of section 401(m)), or
Inserted: "(J) any other asset specified in regulations prescribed by the Secretary.
Inserted: "(4) Look-thru rules.--
Inserted: "(A) In general.--If a nonbusiness asset of an entity consists of a 10-percent interest in any other entity, this subsection shall be applied by disregarding the 10-percent interest and by treating the entity as holding directly its ratable share of the assets of the other entity. This subparagraph shall be applied successively to any 10-percent interest of such other entity in any other entity.
Inserted: "(B) 10-percent interest.--The term '10-percent interest' means--
Inserted: "(i) in the case of an interest in a corporation, ownership of at least 10 percent (by vote or value) of the stock in such corporation,
Inserted: "(ii) in the case of an interest in a partnership, ownership of at least 10 percent of the capital or profits interest in the partnership, and
Inserted: "(iii) in any other case, ownership of at least 10 percent of the beneficial interests in the entity.
Inserted: "(5) Coordination with subsection (b).--Subsection (b) shall apply after the application of this subsection.
Inserted: "(e) Limitation on Minority Discounts.--For purposes of this chapter and chapter 12, in the case of the transfer of any interest in an entity other than an interest which is actively traded (within the meaning of section 1092), no discount shall be allowed by reason of the fact that the transferee does not have control of such entity if the transferee and members of the family (as defined in section 2032A(e)(2)) of the transferee have control of such entity.".
Inserted: (b) Effective Date.--The amendments made by this section shall apply to transfers after the date of the enactment of this Act.
Inserted: SEC. __08. REQUIRED MINIMUM 10-YEAR TERM, ETC., FOR GRANTOR RETAINED ANNUITY TRUSTS.
Inserted: (a) In General.--Subsection (b) of section 2702 of the Internal Revenue Code of 1986 is amended--
Inserted: (1) by redesignating paragraphs (1), (2), and (3) as subparagraphs (A), (B), and (C), respectively, and by moving such subparagraphs (as so redesignated) 2 ems to the right;
Inserted: (2) by striking "For purposes of" and inserting the following:
Inserted: "(1) In general.--For purposes of";
Inserted: (3) by striking "paragraph (1) or (2)" in paragraph (1)(C) (as so redesignated) and inserting "subparagraph (A) or (B)"; and
Inserted: (4) by adding at the end the following new paragraph:
Inserted: "(2) Additional requirements with respect to grantor retained annuities.--For purposes of subsection (a), in the case of an interest described in paragraph (1)(A) (determined without regard to this paragraph) which is retained by the transferor, such interest shall be treated as described in such paragraph only if--
Inserted: "(A) the right to receive the fixed amounts referred to in such paragraph is for a term of not less than 10 years,
Inserted: "(B) such fixed amounts, when determined on an annual basis, do not decrease relative to any prior year during the first 10 years of the term referred to in subparagraph (A), and
Inserted: "(C) the remainder interest has a value greater than zero determined as of the time of the transfer.".
Inserted: (b) Effective Date.--The amendments made by this section shall apply to transfers made after the date of the enactment of this Act.
Original wording
At the end, add the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 4491. Mr. SANDERS (for himself, Mr. Harkin, Mr. Whitehouse, Mr. Brown of Ohio, and Mr. Franken) submitted an amendment intended to be proposed to amendment SA 4402 proposed by Mr. Reid (for Mr. Baucus (for himself, Ms. Landrieu, and Mr. Reid)) to the bill H.R. 5297, to create the Small Business Lending Fund Program to direct the Secretary of the Treasury to make capital investments in eligible institutions in order to increase the availability of credit for small businesses, to amend the Internal Revenue Code of 1986 to provide tax incentives for small business job creation, and for other purposes; which was ordered to lie on the table; as follows:
At the end, add the following:
TITLE _--RESPONSIBLE ESTATE TAX REFORM
SEC. __01. SHORT TITLE.
This title may be cited as the “Responsible Estate Tax Act”.
SEC. __02. REINSTATEMENT AND EXTENSION OF ESTATE AND GENERATION-SKIPPING TAXES; REPEAL OF CARRYOVER BASIS.
(a) In General.--The following provisions of the Economic Growth and Tax Relief Reconciliation Act of 2001, and the amendments made by such provisions, are hereby repealed effective December 31, 2009:
(1) Subtitles A and E of title V.
(2) Subsection (d), and so much of subsection (f)(3) as relates to subsection (d), of section 511.
(3) Paragraph (2) of subsection (b), and paragraph (2) of subsection (e), of section 521.
Any provision of the Internal Revenue Code of 1986 amended by such provisions are amended to read as such provisions would read if such sections had never been enacted.
(b) Conforming Amendment.--Subsection (c) of section 2511 of the Internal Revenue Code of 1986 is hereby repealed effective December 31, 2009.
(c) Sunset Not to Apply.--
(1) Subsection (a) of section 901 of the Economic Growth and Tax Relief Reconciliation Act of 2001 is amended by striking “this Act” and all that follows and inserting “this Act (other than title V) shall not apply to taxable, plan, or limitation years beginning after December 31, 2010.”.
(2) Subsection (b) of such section 901 is amended by striking “, estates, gifts, and transfers”.
(d) Transition Rules.--Notwithstanding any provision of the Internal Revenue Code of 1986, in the case of decedent dying or a transfer made after December 31, 2009, and before the date of the enactment of this Act--
(1) the due date for any return under section 6018 or 6019 of such Code (including any election required to be made on such a return) and any payment of tax under chapter 11, 12, or 13 of such Code shall be the later of--
(A) the date that is 4 months after the date of the enactment of this Act, or
(B) the date otherwise required by law (determined without regard to this subsection), and
(2) any disclaimer of an interest in property shall be treated as a qualified disclaimer under section 2518 of such Code if such disclaimer meets the requirements of paragraphs (1), (3), and (4) of section 2518(b) of such Code and is received in writing by a person described in section 2518(b)(2) of such Code not later than--
(A) the date that is 4 months after the date of the enactment of this Act, or
(B) the date otherwise required under section 2518(b)(2) of such Code.
SEC. __03. MODIFICATION OF RATES AND MAINTENANCE OF UNIFIED CREDIT AGAINST THE ESTATE TAX.
(a) Modification of Rates.--
(1) In general.--The table in paragraph (1) of section 2001(c) of the Internal Revenue Code of 1986 is amended by striking the last 6 rows and inserting the following:
“Over $750,000 but not over $3,500,000... $248,300 plus 39 percent of the excess of such amount over $750,000
Over $3,500,000 but not over $10,000,000.. $1,320,800 plus 45 percent of the excess of such amount over $3,500,000
Over $10,000,000 but not over $50,000,000. $4,245,800 plus 50 percent of the excess of such amount over $10,000,000
Over $50,000,000.......................... $24,245,800 plus 55 percent of the excess of such amount over $50,000,000”.
(2) Surtax on wealthy estates.--Paragraph (2) of section 2001(c) of such Code is amended to read as follows:
“(2) Surtax on estates over $500,000,000.--Notwithstanding paragraph (1), if the amount with respect to which the tentative tax to be computed is over $500,000,000, the rate of tax otherwise in effect under this subsection with respect to the amount in excess of $500,000,000 shall be increased by 10 percentage points.”.
(b) Extension of Applicable 2009 Credit Amounts.--The table in subsection (c) of section 2010 of the Internal Revenue Code of 1986 (relating to applicable credit amount) is amended by inserting “and thereafter” after “2009”.
(c) Effective Date.--The amendments made by this section shall apply to estates of decedents dying, and gifts made, after December 31, 2009.
SEC. __04. MODIFICATION OF RULES FOR VALUE OF CERTAIN FARM, ETC., REAL PROPERTY.
(a) In General.--Paragraph (2) of section 2032A(a) of the Internal Revenue Code of 1986 is amended by striking “$750,000” and inserting “$3,000,000”.
(b) Inflation Adjustment.--Paragraph (3) of section 2032A(a) of such Code is amended--
(1) by striking “1998” and inserting “2009”,
(2) by striking “$750,000” and inserting “$3,000,000” in subparagraph (A), and
(3) by striking “calendar year 1997” and inserting “calendar year 2008” in subparagraph (B).
(c) Effective Date.--The amendments made by this section shall apply to estates of decedents dying, and gifts made, after December 31, 2009.
SEC. __05. MODIFICATION OF ESTATE TAX RULES WITH RESPECT TO LAND SUBJECT TO CONSERVATION EASEMENTS.
(a) Modification of Exclusion Limitation.--The table in paragraph (3) of section 2031(c) of the Internal Revenue Code of 1986 is amended--
(1) by striking “or thereafter” in the last row and inserting “through 2009”, and
(2) by adding at the end the following row:
“2010 and thereafter................................ $2,000,000”.
(b) Modification of Applicable Percentage.--Paragraph (2) of section 2031(c) of the Internal Revenue Code of 1986 is amended by striking “40 percent” and inserting “60 percent”.
(c) Effective Date.--The amendments made by this section shall apply to estates of decedents dying, and gifts made, after December 31, 2009.
SEC. __06. CONSISTENT BASIS REPORTING BETWEEN ESTATE AND PERSON ACQUIRING PROPERTY FROM DECEDENT.
(a) Information Reporting.--
(1) In general.--Subpart A of part III of subchapter A of chapter 61 of the Internal Revenue Code of 1986 is amended by inserting after section 6034A the following new section:
“SEC. 6035. BASIS INFORMATION TO PERSONS ACQUIRING PROPERTY FROM DECEDENT OR BY GIFT.
“(a) Information With Respect to Property Acquired From Decedents.--
“(1) In general.--The executor of any estate required to file a return under section 6018(a) shall furnish to the Secretary and to each person acquiring any interest in property included in the decedent's gross estate for federal estate tax purposes a statement identifying--
“(A) the fair market value of each interest in such property acquired by such person as reported on such return,
“(B) in the case of any property to which the exclusion under section 2031(c) applies or to which section 1014(e) applies, the adjusted basis of such property in the hands of the decedent,
“(C) in the case of any property which consists of stock in a DISC or former DISC (as defined in section 992(a)), the basis of the decedent in such stock reduced by the amount (if any) which would have been included in gross income under section 995(c) as a dividend if the decedent had lived and sold the stock at its fair market value on the estate tax valuation date (determined under the rules of section 1014(d)), and
“(D) such other information with respect to such interest as the Secretary may prescribe.
“(2) Statements by beneficiaries.--Any person required to file a return under section 6018(b) shall furnish to the Secretary and to each other person who holds a legal or beneficial interest in the property to which such return relates a statement identifying the information described in paragraph (1).
“(3) Time for furnishing statement.--
“(A) In general.--Any statement required to be filed under paragraph (1) or (2) shall be filed not later than the earlier of--
“(i) the date which is 30 days after the date on which such return was required to be filed (including extensions, if any), or
“(ii) the date which is 30 days after the date such return is filed.
“(B) Adjustments.--In any case in which there is an adjustment to the information required to be included on a statement filed under paragraph (1) or (2) after such statement has been filed, a supplemental statement under such paragraph shall be filed not later than the date which is 30 days after such adjustment is made.
“(b) Information With Respect to Property Acquired by Gift.--
“(1) In general.--Each person making a transfer by gift who is required to file a return under section 6019 with respect to such transfer shall furnish to the Secretary and to each person acquiring any interest in property by reason of such transfer a statement identifying--
“(A) the donor's adjusted basis in each interest in property acquired by such person,
“(B) the fair market value of each interest in such property at the time of the transfer as reported return,
“(C) in the case of a transfer in trust, the amount of the gain or loss recognized by the grantor on such transfer,
“(D) the amount, if any, of gift tax paid by the transferor with respect to such interest, and
“(E) such other information with respect to such interest as the Secretary may prescribe.
“(2) Time for furnishing statement.--
“(A) In general.--Any statement required to be filed under paragraph (1) shall be filed not later than the earlier of--
“(i) the date which is 30 days after the date on which such return was required to be filed (including extensions, if any), or
“(ii) the date which is 30 days after the date such return is filed.
“(B) Adjustments.--In any case in which there is an adjustment to the information required to be included on a statement filed under paragraph (1) after such statement has been filed, a supplemental statement under such paragraph shall be filed not later than the date which is 30 days after such adjustment is made.
“(c) Regulations.--The Secretary shall prescribe such regulations as necessary to carry out this section, including regulations relating to--
“(1) the application of this section to property with regard to which no estate or gift tax return is required to be filed, and
“(2) situations in which the surviving joint tenant or other recipient may have better information than the executor regarding the basis or fair market value of the property.”.
(2) Penalty for failure to file.--
(A) Return.--Subparagraph (B) of section 6724(d)(1) of the Internal Revenue Code of 1986 is amended by striking “or” at the end of clause (xxiv), by striking “and” at the end of clause (xxv) and inserting “or”, and by adding at the end the following new clause:
“(xxvi) section 6035 (relating to returns relating to basis information to persons acquiring property from decedent or by gift), and”.
(B) Statement.--Subparagraph (A) of section 6724(d)(2)(A) of such Code is amended by inserting “6035,” after “6034A,”.
(3) Clerical amendment.--The table of sections for subpart A of part III of subchapter A of chapter 61 of the Internal Revenue Code of 1986 is amended by inserting after the item relating to section 6034A the following new item:
“Sec. 6035. Basis information to persons acquiring property from decedent or by gift.”.
(b) Consistent Use of Basis.--
(1) Property acquired from a decedent.--Section 1014 of the Internal Revenue Code of 1986 is amended by adding at the end the following new subsection:
“(f) Basis Must Be Consistent With Information Reports.--Except as provided by the Secretary in regulations, in any case in which the executor of the estate was required to make a return under section 6035, the basis of an interest in property in the hands of the person acquiring such property shall not exceed--
“(1) except as provided in paragraph (2), shall not exceed the value of such interest as determined for purposes of chapter 11, and
“(2) in the case of property to which subsection (a)(4) or (d) applies, shall be calculated using the information reported to such person under section 6035(a).”.
(2) Property acquired by gifts and transfers in trust.--Section 1015 of the Internal Revenue Code of 1986 is amended by adding at the end the following new subsection:
“(f) Basis Must Be Consistent With Information Reports.--Except as provided by the Secretary in regulations, in any case in which the transferor was required to make a return under section 6035, the basis of the property in the hands of the person acquiring such property shall be calculated using the information reported to such person under section 6035(b).”.
(c) Penalty for Inconsistent Reporting.--
(1) In general.--Subsection (b) of section 6662 of the Internal Revenue Code of 1986 is amended by inserting after paragraph (7) the following new paragraph:
“(8) Any inconsistent estate or gift basis reporting.”.
(2) Inconsistent basis reporting.--Section 6662 of such Code is amended by adding at the end the following new subsection:
“(k) Inconsistent Estate or Gift Basis Reporting.--For purposes of this section, the term ‘inconsistent estate or gift basis reporting' means the portion of the understatement which is attributable to the failure by the taxpayer to use the information reported to such taxpayer under section 6035 in calculating the basis of any property acquired from a decedent or by gift or transfer in trust.”.
(d) Effective Date.--The amendments made by this section shall apply to transfers for which returns are filed after the date of the enactment of this Act.
SEC. __07. VALUATION RULES FOR CERTAIN TRANSFERS OF NONBUSINESS ASSETS; LIMITATION ON MINORITY DISCOUNTS.
(a) In General.--Section 2031 of the Internal Revenue Code of 1986 (relating to definition of gross estate) is amended by redesignating subsection (d) as subsection (f) and by inserting after subsection (c) the following new subsections:
“(d) Valuation Rules for Certain Transfers of Nonbusiness Assets.--For purposes of this chapter and chapter 12--
“(1) In general.--In the case of the transfer of any interest in an entity other than an interest which is actively traded (within the meaning of section 1092)--
“(A) the value of any nonbusiness assets held by the entity with respect to such interest shall be determined as if the transferor had transferred such assets directly to the transferee (and no valuation discount shall be allowed with respect to such nonbusiness assets), and
“(B) such nonbusiness assets shall not be taken into account in determining the value of the interest in the entity.
“(2) Nonbusiness assets.--For purposes of this subsection--
“(A) In general.--The term ‘nonbusiness asset' means any asset which is not used in the active conduct of 1 or more trades or businesses.
“(B) Exception for certain passive assets.--Except as provided in subparagraph (C), a passive asset shall not be treated for purposes of subparagraph (A) as used in the active conduct of a trade or business unless--
“(i) the asset is property described in paragraph (1) or (4) of section 1221(a) or is a hedge with respect to such property, or
“(ii) the asset is real property used in the active conduct of 1 or more real property trades or businesses (within the meaning of section 469(c)(7)(C)) in which the transferor materially participates and with respect to which the transferor meets the requirements of section 469(c)(7)(B)(ii).
For purposes of clause (ii), material participation shall be determined under the rules of section 469(h), except that section 469(h)(3) shall be applied without regard to the limitation to farming activity.
“(C) Exception for working capital.--Any asset (including a passive asset) which is held as a part of the reasonably required working capital needs of a trade or business shall be treated as used in the active conduct of a trade or business.
“(3) Passive asset.--For purposes of this subsection, the term ‘passive asset' means any--
“(A) cash or cash equivalents,
“(B) except to the extent provided by the Secretary, stock in a corporation or any other equity, profits, or capital interest in any entity,
“(C) evidence of indebtedness, option, forward or futures contract, notional principal contract, or derivative,
“(D) asset described in clause (iii), (iv), or (v) of section 351(e)(1)(B),
“(E) annuity,
“(F) real property used in 1 or more real property trades or businesses (as defined in section 469(c)(7)(C)),
“(G) asset (other than a patent, trademark, or copyright) which produces royalty income,
“(H) commodity,
“(I) collectible (within the meaning of section 401(m)), or
“(J) any other asset specified in regulations prescribed by the Secretary.
“(4) Look-thru rules.--
“(A) In general.--If a nonbusiness asset of an entity consists of a 10-percent interest in any other entity, this subsection shall be applied by disregarding the 10-percent interest and by treating the entity as holding directly its ratable share of the assets of the other entity. This subparagraph shall be applied successively to any 10-percent interest of such other entity in any other entity.
“(B) 10-percent interest.--The term ‘10-percent interest' means--
“(i) in the case of an interest in a corporation, ownership of at least 10 percent (by vote or value) of the stock in such corporation,
“(ii) in the case of an interest in a partnership, ownership of at least 10 percent of the capital or profits interest in the partnership, and
“(iii) in any other case, ownership of at least 10 percent of the beneficial interests in the entity.
“(5) Coordination with subsection (b).--Subsection (b) shall apply after the application of this subsection.
“(e) Limitation on Minority Discounts.--For purposes of this chapter and chapter 12, in the case of the transfer of any interest in an entity other than an interest which is actively traded (within the meaning of section 1092), no discount shall be allowed by reason of the fact that the transferee does not have control of such entity if the transferee and members of the family (as defined in section 2032A(e)(2)) of the transferee have control of such entity.”.
(b) Effective Date.--The amendments made by this section shall apply to transfers after the date of the enactment of this Act.
SEC. __08. REQUIRED MINIMUM 10-YEAR TERM, ETC., FOR GRANTOR RETAINED ANNUITY TRUSTS.
(a) In General.--Subsection (b) of section 2702 of the Internal Revenue Code of 1986 is amended--
(1) by redesignating paragraphs (1), (2), and (3) as subparagraphs (A), (B), and (C), respectively, and by moving such subparagraphs (as so redesignated) 2 ems to the right;
(2) by striking “For purposes of” and inserting the following:
“(1) In general.--For purposes of”;
(3) by striking “paragraph (1) or (2)” in paragraph (1)(C) (as so redesignated) and inserting “subparagraph (A) or (B)”; and
(4) by adding at the end the following new paragraph:
“(2) Additional requirements with respect to grantor retained annuities.--For purposes of subsection (a), in the case of an interest described in paragraph (1)(A) (determined without regard to this paragraph) which is retained by the transferor, such interest shall be treated as described in such paragraph only if--
“(A) the right to receive the fixed amounts referred to in such paragraph is for a term of not less than 10 years,
“(B) such fixed amounts, when determined on an annual basis, do not decrease relative to any prior year during the first 10 years of the term referred to in subparagraph (A), and
“(C) the remainder interest has a value greater than zero determined as of the time of the transfer.”.
(b) Effective Date.--The amendments made by this section shall apply to transfers made after the date of the enactment of this Act.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
July 20, 2010