Of a perfecting nature.
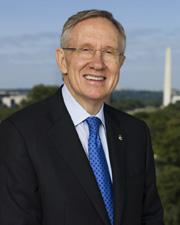 Sen. Harry Reid (D-NV)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Roll call votes on amendments in Senate: Motion to table amendment SA 2524 agreed to in Senate by Yea-Nay Vote. 73 - 24. Record Vote Number: 175.(consideration: CR S4936)
July 12, 2012
View full timeline
Roll call votes on amendments in Senate: Motion to table amendment SA 2524 agreed to in Senate by Yea-Nay Vote. 73 - 24. Record Vote Number: 175.(consideration: CR S4936)
July 12, 2012
Considered by Senate. (consideration: CR S4932)
July 12, 2012
Motion to table amendment SA 2524 agreed to in Senate by Yea-Nay Vote. 73 - 24. Record Vote Number: 175. (consideration: CR S4936)
July 12, 2012
Senate amendment submitted
July 11, 2012
Senate amendment proposed (on the floor): Amendment SA 2524 proposed by Senator Reid to language proposed to be stricken by amendment no. SA 2521.(consideration: CR S4884)
July 11, 2012
Amendment SA 2524 proposed by Senator Reid to language proposed to be stricken by amendment no. SA 2521. (consideration: CR S4884) Of a perfecting nature.
July 11, 2012
Votes
1 roll call on this amendment
Amendments
1 amendmentOffered to this amendment
Amendments
1 amendmentOffered to this amendment
Text
Submitted
SA 2524. Mr. REID proposed an amendment to the bill S. 2237, to
provide a temporary income tax credit for increased payroll and extend
bonus depreciation for an additional year, and for other purposes; as
follows:

Strike all after the first word and insert the following:

1. SHORT TITLE.

This Act may be cited as the ``Small Business Tax Cut
Act''.

SEC. 2. DEDUCTION FOR DOMESTIC BUSINESS INCOME OF QUALIFIED
SMALL BUSINESSES.

(a) In General.--Part VI of subchapter B of chapter 1 of
the Internal Revenue Code of 1986 is amended by adding at the
end the following new section:

``SEC. 200. DOMESTIC BUSINESS INCOME OF QUALIFIED SMALL
BUSINESSES.

``(a) Allowance of Deduction.--In the case of a qualified
small business, there shall be allowed as a deduction an
amount equal to 20 percent of the lesser of--
``(1) the qualified domestic business income of the
taxpayer for the taxable year, or
``(2) taxable income (determined without regard to this
section) for the taxable year.
``(b) Deduction Limited Based on Wages Paid.--
``(1) In general.--The amount of the deduction allowable
under subsection (a) for any taxable year shall not exceed 50
percent of the greater of--
``(A) the W-2 wages of the taxpayer paid to non-owners, or
``(B) the sum of--
``(i) the W-2 wages of the taxpayer paid to individuals who
are non-owner family members of direct owners, plus
``(ii) any W-2 wages of the taxpayer paid to 10-percent-or-
less direct owners.
``(2) Definitions related to ownership.--For purposes of
this section--
``(A) Non-owner.--The term `non-owner' means, with respect
to any qualified small business, any person who does not own
(and is not considered as owning within the meaning of
subsection (c) or (e)(3) of section 267, as the case may be)
any stock of such business (or, if such business is other
than a corporation, any capital or profits interest of such
business).
``(B) Non-owner family members.--An individual is a non-
owner family member of a direct owner if--
``(i) such individual is family (within the meaning of
section 267(c)(4)) of a direct owner, and
``(ii) such individual would be a non-owner if subsections
(c) and (e)(3) of section 267 were applied without regard to
section 267(c)(2).
``(C) Direct owner.--The term `direct owner' means, with
respect to any qualified small business, any person who owns
(or is considered as owning under the applicable non-family
attribution rules) any stock of such business (or, if such
business is other than a corporation, any capital or profits
interest of such business).
``(D) 10-percent-or-less direct owners.--The term `10-
percent-or-less direct owner' means, with respect to any
qualified small business, any direct owner of such business
who owns (or is considered as owning under the applicable
non-family attribution rules)--
``(i) in the case of a qualified small business which is a
corporation, not more than 10 percent of the outstanding
stock of the corporation or stock possessing more than 10
percent of the total combined voting power of all stock of
the corporation, or
``(ii) in the case of a qualified small business which is
not a corporation, not more than 10 percent of the capital or
profits interest of such business.
``(E) Applicable non-family attribution rules.--The term
`applicable non-family attribution rules' means the
attribution rules of subsection (c) or (e)(3) of section 267,
as the case may be, but in each case applied without regard
to section 267(c)(2).
``(3) W-2 wages.--For purposes of this section--
``(A) In general.--The term `W-2 wages' means, with respect
to any person for any taxable year of such person, the sum of
the amounts described in paragraphs (3) and (8) of section
6051(a) paid by such person with respect to employment of
employees by such person during the calendar year ending
during such taxable year.

[[Page S4913]]

``(B) Limitation to wages attributable to qualified
domestic business income.--Such term shall not include any
amount which is not properly allocable to domestic business
gross receipts for purposes of subsection (c)(1).
``(C) Other requirements.--Except in the case of amounts
treated as W-2 wages under paragraph (4)--
``(i) such term shall not include any amount which is not
allowed as a deduction under section 162 for the taxable
year, and
``(ii) such term shall not include any amount which is not
properly included in a return filed with the Social Security
Administration on or before the 60th day after the due date
(including extensions) for such return.
``(4) Certain partnership distributions treated as w-2
wages.--
``(A) In general.--In the case of a qualified small
business which is a partnership and elects the application of
this paragraph for the taxable year--
``(i) the qualified domestic business taxable income of
such partnership for such taxable year (determined after the
application of clause (ii)) which is allocable under rules
similar to the rules of section 199(d)(1)(A)(ii) to each
qualified service-providing partner shall be treated for
purposes of this section as W-2 wages paid during such
taxable year to such partner as an employee, and
``(ii) the domestic business gross receipts of such
partnership for such taxable year shall be reduced by the
amount so treated.
``(B) Qualified service-providing partner.--For purposes of
this paragraph, the term `qualified service-providing
partner' means, with respect to any qualified domestic
business taxable income, any partner who is a 10-percent-or-
less direct owner and who materially participates in the
trade or business to which such income relates.
``(5) Acquisitions and dispositions.--The Secretary shall
provide for the application of this subsection in cases where
the taxpayer acquires, or disposes of, the major portion of a
trade or business or the major portion of a separate unit of
a trade or business during the taxable year.
``(c) Qualified Domestic Business Income.--For purposes of
this section--
``(1) In general.--The term `qualified domestic business
income' for any taxable year means an amount equal to the
excess (if any) of--
``(A) the taxpayer's domestic business gross receipts for
such taxable year, over
``(B) the sum of--
``(i) the cost of goods sold that are allocable to such
receipts, and
``(ii) other expenses, losses, or deductions (other than
the deduction allowed under this section), which are properly
allocable to such receipts.
``(2) Domestic business gross receipts.--
``(A) In general.--The term `domestic business gross
receipts' means the gross receipts of the taxpayer which are
effectively connected with the conduct of a trade or business
within the United States within the meaning of section 864(c)
but determined--
``(i) without regard to paragraphs (3), (4), and (5)
thereof, and
``(ii) by substituting `qualified small business (within
the meaning of section 200)' for `nonresident alien
individual or a foreign corporation' each place it appears
therein.
``(B) Exceptions.--For purposes of paragraph (1), domestic
business gross receipts shall not include any of the
following:
``(i) Gross receipts derived from the sale or exchange of--

``(I) a capital asset, or
``(II) property used in the trade or business (as defined
in section 1231(b)).

``(ii) Royalties, rents, dividends, interest, or annuities.
``(iii) Any amount which constitutes wages (as defined in
section 3401).
``(3) Application of certain rules.--Rules similar to the
rules of paragraphs (2) and (3) of section 199(c) shall apply
for purposes of this section (applied with respect to
qualified domestic business income in lieu of qualified
production activities income and with respect to domestic
business gross receipts in lieu of domestic production gross
receipts).
``(d) Qualified Small Business.--For purposes of this
section--
``(1) In general.--The term `qualified small business'
means any employer engaged in a trade or business if such
employer had fewer than 500 full-time equivalent employees
for either calendar year 2010 or 2011.
``(2) Full-time equivalent employees.--The term `full-time
equivalent employees' has the meaning given such term by
subsection (d)(2) of section 45R applied--
``(A) without regard to subsection (d)(5) of such section,
``(B) with regard to subsection (e)(1) of such section, and
``(C) by substituting `calendar year' for `taxable year'
each place it appears therein.
``(3) Employers not in existence prior to 2012.--In the
case of an employer which was not in existence on January 1,
2012, the determination under paragraph (1) shall be made
with respect to calendar year 2012.
``(4) Application to calendar years in which employer in
existence for portion of calendar year.--In the case of any
calendar year during which the employer comes into existence,
the number of full-time equivalent employees determined under
paragraph (2) with respect to such calendar year shall be
increased by multiplying the number so determined (without
regard to this paragraph) by the quotient obtained by
dividing--
``(A) the number of days in such calendar year, by
``(B) the number of days during such calendar year which
such employer is in existence.
``(5) Special rules.--
``(A) Aggregation rule.--For purposes of paragraph (1), any
person treated as a single employer under subsection (a) or
(b) of section 52 (applied without regard to section 1563(b))
or subsection (m) or (o) of section 414 shall be treated as a
single employer for purposes of this subsection.
``(B) Predecessors.--Any reference in this subsection to an
employer shall include a reference to any predecessor of such
employer.
``(e) Special Rules.--
``(1) Elective application of deduction.--Except as
otherwise provided by the Secretary, the taxpayer may elect
not to take any item of income into account as domestic
business gross receipts for purposes of this section.
``(2) Coordination with section 199.--If a deduction is
allowed under this section with respect to any taxpayer for
any taxable year--
``(A) any gross receipts of the taxpayer which are taken
into account under this section for such taxable year shall
not be taken into account under section 199 for such taxable
year, and
``(B) the W-2 wages of the taxpayer which are taken into
account under this section shall not be taken into account
under section 199 for such taxable year.
``(3) Application of certain rules.--Rules similar to the
rules of paragraphs (1), (2), (3), (4), (6), and (7) of
section 199(d) shall apply for purposes of this section
(applied with respect to qualified domestic business income
in lieu of qualified production activities income).
``(f) Regulations.--The Secretary shall prescribe such
regulations as are necessary to carry out the purposes of
this section, including regulations which prevent a taxpayer
which reorganizes from being treated as a qualified small
business if such taxpayer would not have been treated as a
qualified small business prior to such reorganization.
``(g) Application.--Subsection (a) shall apply only with
respect to the first taxable year of the taxpayer beginning
after December 31, 2011.''.
(b) Conforming Amendments.--
(1) Section 56(d)(1)(A) of such Code is amended by striking
``deduction under section 199'' both places it appears and
inserting ``deductions under sections 199 and 200''.
(2) Section 56(g)(4)(C) of such Code is amended by adding
at the end the following new clause:
``(vii) Deduction for domestic business income of qualified
small businesses.--Clause (i) shall not apply to any amount
allowable as a deduction under section 200.''.
(3) The following provisions of such Code are each amended
by inserting ``200,'' after ``199,''.
(A) Section 86(b)(2)(A).
(B) Section 135(c)(4)(A).
(C) Section 137(b)(3)(A).
(D) Section 219(g)(3)(A)(ii).
(E) Section 221(b)(2)(C)(i).
(F) Section 222(b)(2)(C)(i).
(G) Section 246(b)(1).
(H) Section 469(i)(3)(F)(iii).
(4) Section 163(j)(6)(A)(i) of such Code is amended by
striking ``and'' at the end of subclause (III) and by
inserting after subclause (IV) the following new subclause:

``(V) any deduction allowable under section 200, and''.

(5) Section 170(b)(2)(C) of such Code is amended by
striking ``and'' at the end of clause (iv), by striking the
period at the end of clause (v) and inserting ``, and'', and
by inserting after clause (v) the following new clause:
``(vi) section 200.''.
(6) Section 172(d) of such Code is amended by adding at the
end the following new paragraph:
``(8) Domestic business income of qualified small
businesses.--The deduction under section 200 shall not be
allowed.''.
(7) Section 613(a) of such Code is amended by striking
``deduction under section 199'' and inserting ``deductions
under sections 199 and 200''.
(8) Section 613A(d)(1) of such Code is amended by
redesignating subparagraphs (C), (D), and (E) as
subparagraphs (D), (E), and (F), respectively, and by
inserting after subparagraph (B) the following new
subparagraph:
``(C) any deduction allowable under section 200,''.
(9) Section 1402(a) of such Code is amended by striking
``and'' at the end of paragraph (16), by redesignating
paragraph (17) as paragraph (18), and by inserting after
paragraph (16) the following new paragraph:
``(17) the deduction provided by section 200 shall not be
allowed; and''.
(c) Clerical Amendment.--The table of sections for part VI
of subchapter B of chapter 1 of such Code is amended by
adding at the end the following new item:

``Sec. 200. Domestic business income of qualified small businesses.''.
______