S.Amdt. 2529
What it does: Adds SEC. __. MODIFICATION AND PERMANENT EXTENSION OF THE INCENTIVES TO REINVEST FOREIGN EARNINGS IN THE UNITED STATES at the end of the bill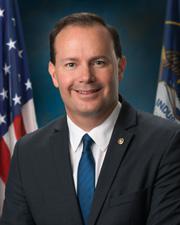 Sen. Mike Lee (R-UT)
What it changes
1 change to S. 2237 · shown in the bill's text
Adds SEC. __. MODIFICATION AND PERMANENT EXTENSION OF THE INCENTIVES TO REINVEST FOREIGN EARNINGS IN THE UNITED STATES at the end of the bill
Adds a sectionIn S. 2237 · Placed on Calendar Senate
(ii) multiplying the limitation under subparagraph (B)(ii) of such paragraph (as so in effect) by a fraction the numerator of which is the number of days in the taxable year after December 31, 2011, and the denominator of which is the number of days in the taxable year.
Inserted: SEC. __. MODIFICATION AND PERMANENT EXTENSION OF THE INCENTIVES TO REINVEST FOREIGN EARNINGS IN THE UNITED STATES.
Inserted: (a) Repatriation Subject to 5 Percent Tax Rate.--Subsection (a)(1) of section 965 of the Internal Revenue Code of 1986 is amended by striking "85 percent" and inserting "85.7 percent".
Inserted: (b) Permanent Extension To Elect Repatriation.--Subsection (f) of section 965 of the Internal Revenue Code of 1986 is amended to read as follows:
Inserted: "(f) Election.--The taxpayer may elect to apply this section to any taxable year only if made on or before the due date (including extensions) for filing the return of tax for such taxable year.".
Inserted: (c) Repatriation Includes Current and Accumulated Foreign Earnings.--
Inserted: (1) In general.--Paragraph (1) of section 965(b) of the Internal Revenue Code of 1986 is amended to read as follows:
Inserted: "(1) In general.--The amount of dividends taken into account under subsection (a) shall not exceed the sum of the current and accumulated earnings and profits described in section 959(c)(3) for the year a deduction is claimed under subsection (a), without diminution by reason of any distributions made during the election year, for all controlled foreign corporations of the United States shareholder.".
Inserted: (2) Conforming amendments.--
Inserted: (A) Section 965(b) of such Code is amended by striking paragraphs (2) and (4) and by redesignating paragraph (3) as paragraph (2).
Inserted: (B) Section 965(c) of such Code is amended by striking paragraphs (1) and (2) and by redesignating paragraphs (3), (4), and (5) as paragraphs (1), (2), and (3), respectively.
Inserted: (C) Paragraph (3) of section 965(c) of such Code, as redesignated by subparagraph (B), is amended to read as follows:
Inserted: "(3) Controlled groups.--All United States shareholders which are members of an affiliated group filing a consolidated return under section 1501 shall be treated as one United States shareholder.".
Show 4 more inserted paragraphsShow less
Inserted: (d) Clerical Amendments.--
Inserted: (1) The heading for section 965 of the Internal Revenue Code of 1986 is amended by striking "TEMPORARY".
Inserted: (2) The table of sections for subpart F of part III of subchapter N of chapter 1 of such Code is amended by striking "Temporary dividends" and inserting "Dividends".
Inserted: (e) Effective Date.--The amendments made by this section shall apply to taxable years ending after the date of the enactment of this Act.
Original wording
At the end, add the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 2529. Mr. LEE submitted an amendment intended to be proposed by him to the bill S. 2237, to provide a temporary income tax credit for increased payroll and extend bonus depreciation for an additional year, and for other purposes; which was ordered to lie on the table; as follows:
At the end, add the following:
SEC. __. MODIFICATION AND PERMANENT EXTENSION OF THE INCENTIVES TO REINVEST FOREIGN EARNINGS IN THE UNITED STATES.
(a) Repatriation Subject to 5 Percent Tax Rate.--Subsection (a)(1) of section 965 of the Internal Revenue Code of 1986 is amended by striking “85 percent” and inserting “85.7 percent”.
(b) Permanent Extension To Elect Repatriation.--Subsection (f) of section 965 of the Internal Revenue Code of 1986 is amended to read as follows:
“(f) Election.--The taxpayer may elect to apply this section to any taxable year only if made on or before the due date (including extensions) for filing the return of tax for such taxable year.”.
(c) Repatriation Includes Current and Accumulated Foreign Earnings.--
(1) In general.--Paragraph (1) of section 965(b) of the Internal Revenue Code of 1986 is amended to read as follows:
“(1) In general.--The amount of dividends taken into account under subsection (a) shall not exceed the sum of the current and accumulated earnings and profits described in section 959(c)(3) for the year a deduction is claimed under subsection (a), without diminution by reason of any distributions made during the election year, for all controlled foreign corporations of the United States shareholder.”.
(2) Conforming amendments.--
(A) Section 965(b) of such Code is amended by striking paragraphs (2) and (4) and by redesignating paragraph (3) as paragraph (2).
(B) Section 965(c) of such Code is amended by striking paragraphs (1) and (2) and by redesignating paragraphs (3), (4), and (5) as paragraphs (1), (2), and (3), respectively.
(C) Paragraph (3) of section 965(c) of such Code, as redesignated by subparagraph (B), is amended to read as follows:
“(3) Controlled groups.--All United States shareholders which are members of an affiliated group filing a consolidated return under section 1501 shall be treated as one United States shareholder.”.
(d) Clerical Amendments.--
(1) The heading for section 965 of the Internal Revenue Code of 1986 is amended by striking “TEMPORARY”.
(2) The table of sections for subpart F of part III of subchapter N of chapter 1 of such Code is amended by striking “Temporary dividends” and inserting “Dividends”.
(e) Effective Date.--The amendments made by this section shall apply to taxable years ending after the date of the enactment of this Act.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
July 11, 2012