S.Amdt. 2534
What it does: Adds SEC. _. NO MORTGAGE INTEREST DEDUCTION FOR MILLIONAIRES AND BILLIONAIRES wherever appropriate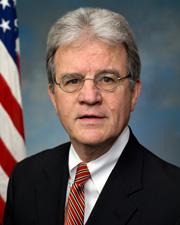 Sen. Tom Coburn (R-OK)
What it changes
1 change to S. 2237
Adds SEC. _. NO MORTGAGE INTEREST DEDUCTION FOR MILLIONAIRES AND BILLIONAIRES wherever appropriate
Adds a sectionInserted: SEC. _. NO MORTGAGE INTEREST DEDUCTION FOR MILLIONAIRES AND BILLIONAIRES.
Inserted: (a) In General.--Section 163(h)(4) of the Internal Revenue Code of 1986 is amended by adding at the end the following new subparagraph:
Inserted: "(G) No deduction for millionaires and billionaires.--
Inserted: "(i) In general.--Except as provided in clause (ii), no deduction shall be allowed by reason of paragraph (2)(D) for any taxable year with respect to any taxpayer with an adjusted gross income equal to or greater than $1,000,000 for such taxable year.
Inserted: "(ii) Termination.--Clause (i) shall not apply to any taxable year beginning after the date on which the aggregate savings from the elimination of the deductions and credits for millionaires attributable to the enactment of sections 4 through 11 of the Small Business Jobs and Tax Relief Act matches dollar for dollar the decrease in revenue attributable to the enactment of sections 2 and 3 of such Act.".
Inserted: (b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2011.
Inserted: SEC. _. NO RENTAL EXPENSE DEDUCTION FOR MILLIONAIRES AND BILLIONAIRES.
Inserted: (a) In General.--Section 212 of the Internal Revenue Code of 1986 is amended by adding at the end the following new flush sentence:
Inserted: "Paragraph (2) shall not apply for any taxable year with respect to any taxpayer with an adjusted gross income equal to or greater than $1,000,000 for such taxable year. The preceding sentence shall not apply to any taxable year beginning after the date on which the aggregate savings from the elimination of the deductions and credits for millionaires attributable to the enactment of sections 4 through 11 of the Small Business Jobs and Tax Relief Act matches dollar for dollar the decrease in revenue attributable to the enactment of sections 2 and 3 of such Act.".
Inserted: (b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2011.
Inserted: SEC. _. NO GAMBLING LOSS DEDUCTION FOR MILLIONAIRES AND BILLIONAIRES.
Inserted: (a) In General.--Section 165(d) of the Internal Revenue Code of 1986 is amended by adding at the end the following: "In the case of a taxpayer with an adjusted gross income equal to or greater than $1,000,000 for the taxable year, the preceding sentence shall not apply for any taxable year beginning before the date on which the aggregate savings from the elimination of the deductions and credits for millionaires attributable to the enactment of sections 4 through 11 of the Small Business Jobs and Tax Relief Act matches dollar for dollar the decrease in revenue attributable to the enactment of sections 2 and 3 of such Act.".
Show 25 more inserted paragraphsShow less
Inserted: (b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2011.
Inserted: SEC. _. NO DISCHARGE OF INDEBTEDNESS DEDUCTION FOR MILLIONAIRES AND BILLIONAIRES.
Inserted: (a) In General.--Section 108 of the Internal Revenue Code of 1986 is amended by adding at the end the following new subsection:
Inserted: "(j) No Deduction for Millionaires and Billionaires.--
Inserted: "(1) In general.--Except as provided in paragraph (2), no exclusion shall be allowed by reason of this section for any taxable year with respect to any taxpayer with an adjusted gross income equal to or greater than $1,000,000 for such taxable year.
Inserted: "(2) Termination.--Paragraph (1) shall not apply to any taxable year beginning after the date on which the aggregate savings from the elimination of the deductions and credits for millionaires attributable to the enactment of sections 4 through 11 of the Small Business Jobs and Tax Relief Act matches dollar for dollar the decrease in revenue attributable to the enactment of sections 2 and 3 of such Act.".
Inserted: (b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2011.
Inserted: SEC. _. NO ELECTRIC PLUG-IN VEHICLE TAX CREDIT FOR MILLIONAIRES AND BILLIONAIRES.
Inserted: (a) In General.--Section 30D(f) of the Internal Revenue Code of 1986 is amended by adding at the end the following new paragraph:
Inserted: "(8) No credit for millionaires and billionaires.--
Inserted: "(A) In general.--Except as provided in subparagraph (B), no credit described in subsection (c)(2) shall be allowed under this section for any taxable year with respect to any taxpayer with an adjusted gross income equal to or greater than $1,000,000 for such taxable year.
Inserted: "(B) Termination.--Subparagraph (A) shall not apply to any taxable year beginning after the date on which the aggregate savings from the elimination of the deductions and credits for millionaires attributable to the enactment of sections 4 through 11 of the Small Business Jobs and Tax Relief Act matches dollar for dollar the decrease in revenue attributable to the enactment of sections 2 and 3 of such Act.".
Inserted: (b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2011.
Inserted: SEC. _. NO HOUSEHOLD AND DEPENDENT CARE CREDIT FOR MILLIONAIRES AND BILLIONAIRES.
Inserted: (a) In General.--Section 21 of the Internal Revenue Code of 1986 is amended by redesignating subsection (f) as subsection (g) and by inserting after subsection (e) the following new subsection:
Inserted: "(f) No Credit for Millionaires and Billionaires.--
Inserted: "(1) In general.--Except as provided in paragraph (2), no credit shall be allowed under this section for any taxable year with respect to any taxpayer with an adjusted gross income equal to or greater than $1,000,000 for such taxable year.
Inserted: "(2) Termination.--Paragraph (1) shall not apply to any taxable year beginning after the date on which the aggregate savings from the elimination of the deductions and credits for millionaires attributable to the enactment of sections 4 through 11 of the Small Business Jobs and Tax Relief Act matches dollar for dollar the decrease in revenue attributable to the enactment of sections 2 and 3 of such Act.".
Inserted: (b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2011.
Inserted: SEC. _. NO RESIDENTIAL ENERGY EFFICIENT PROPERTY CREDIT FOR MILLIONAIRES AND BILLIONAIRES.
Inserted: (a) In General.--Section 25D(e) of the Internal Revenue Code of 1986 is amended by adding at the end the following new paragraph:
Inserted: "(9) No credit for millionaires and billionaires.--
Inserted: "(A) In general.--Except as provided in subparagraph (B), no credit shall be allowed under this section for any taxable year with respect to any taxpayer with an adjusted gross income equal to or greater than $1,000,000 for such taxable year.
Inserted: "(B) Termination.--Subparagraph (A) shall not apply to any taxable year beginning after the date on which the aggregate savings from the elimination of the deductions and credits for millionaires attributable to the enactment of sections 4 through 11 of the Small Business Jobs and Tax Relief Act matches dollar for dollar the decrease in revenue attributable to the enactment of sections 2 and 3 of such Act.".
Inserted: (b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2011.
The amendment doesn't say where this goes; the clerk decides.
Original wording
At the appropriate place, insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 2534. Mr. COBURN submitted an amendment intended to be proposed by him to the bill S. 2237, to provide a temporary income tax credit for increased payroll and extend bonus depreciation for an additional year, and for other purposes; which was ordered to lie on the table; as follows:
At the appropriate place, insert the following:
SEC. _. NO MORTGAGE INTEREST DEDUCTION FOR MILLIONAIRES AND BILLIONAIRES.
(a) In General.--Section 163(h)(4) of the Internal Revenue Code of 1986 is amended by adding at the end the following new subparagraph:
“(G) No deduction for millionaires and billionaires.--
“(i) In general.--Except as provided in clause (ii), no deduction shall be allowed by reason of paragraph (2)(D) for any taxable year with respect to any taxpayer with an adjusted gross income equal to or greater than $1,000,000 for such taxable year.
“(ii) Termination.--Clause (i) shall not apply to any taxable year beginning after the date on which the aggregate savings from the elimination of the deductions and credits for millionaires attributable to the enactment of sections 4 through 11 of the Small Business Jobs and Tax Relief Act matches dollar for dollar the decrease in revenue attributable to the enactment of sections 2 and 3 of such Act.”.
(b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2011.
SEC. _. NO RENTAL EXPENSE DEDUCTION FOR MILLIONAIRES AND BILLIONAIRES.
(a) In General.--Section 212 of the Internal Revenue Code of 1986 is amended by adding at the end the following new flush sentence:
“Paragraph (2) shall not apply for any taxable year with respect to any taxpayer with an adjusted gross income equal to or greater than $1,000,000 for such taxable year. The preceding sentence shall not apply to any taxable year beginning after the date on which the aggregate savings from the elimination of the deductions and credits for millionaires attributable to the enactment of sections 4 through 11 of the Small Business Jobs and Tax Relief Act matches dollar for dollar the decrease in revenue attributable to the enactment of sections 2 and 3 of such Act.”.
(b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2011.
SEC. _. NO GAMBLING LOSS DEDUCTION FOR MILLIONAIRES AND BILLIONAIRES.
(a) In General.--Section 165(d) of the Internal Revenue Code of 1986 is amended by adding at the end the following: “In the case of a taxpayer with an adjusted gross income equal to or greater than $1,000,000 for the taxable year, the preceding sentence shall not apply for any taxable year beginning before the date on which the aggregate savings from the elimination of the deductions and credits for millionaires attributable to the enactment of sections 4 through 11 of the Small Business Jobs and Tax Relief Act matches dollar for dollar the decrease in revenue attributable to the enactment of sections 2 and 3 of such Act.”.
(b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2011.
SEC. _. NO DISCHARGE OF INDEBTEDNESS DEDUCTION FOR MILLIONAIRES AND BILLIONAIRES.
(a) In General.--Section 108 of the Internal Revenue Code of 1986 is amended by adding at the end the following new subsection:
“(j) No Deduction for Millionaires and Billionaires.--
“(1) In general.--Except as provided in paragraph (2), no exclusion shall be allowed by reason of this section for any taxable year with respect to any taxpayer with an adjusted gross income equal to or greater than $1,000,000 for such taxable year.
“(2) Termination.--Paragraph (1) shall not apply to any taxable year beginning after the date on which the aggregate savings from the elimination of the deductions and credits for millionaires attributable to the enactment of sections 4 through 11 of the Small Business Jobs and Tax Relief Act matches dollar for dollar the decrease in revenue attributable to the enactment of sections 2 and 3 of such Act.”.
(b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2011.
SEC. _. NO ELECTRIC PLUG-IN VEHICLE TAX CREDIT FOR MILLIONAIRES AND BILLIONAIRES.
(a) In General.--Section 30D(f) of the Internal Revenue Code of 1986 is amended by adding at the end the following new paragraph:
“(8) No credit for millionaires and billionaires.--
“(A) In general.--Except as provided in subparagraph (B), no credit described in subsection (c)(2) shall be allowed under this section for any taxable year with respect to any taxpayer with an adjusted gross income equal to or greater than $1,000,000 for such taxable year.
“(B) Termination.--Subparagraph (A) shall not apply to any taxable year beginning after the date on which the aggregate savings from the elimination of the deductions and credits for millionaires attributable to the enactment of sections 4 through 11 of the Small Business Jobs and Tax Relief Act matches dollar for dollar the decrease in revenue attributable to the enactment of sections 2 and 3 of such Act.”.
(b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2011.
SEC. _. NO HOUSEHOLD AND DEPENDENT CARE CREDIT FOR MILLIONAIRES AND BILLIONAIRES.
(a) In General.--Section 21 of the Internal Revenue Code of 1986 is amended by redesignating subsection (f) as subsection (g) and by inserting after subsection (e) the following new subsection:
“(f) No Credit for Millionaires and Billionaires.--
“(1) In general.--Except as provided in paragraph (2), no credit shall be allowed under this section for any taxable year with respect to any taxpayer with an adjusted gross income equal to or greater than $1,000,000 for such taxable year.
“(2) Termination.--Paragraph (1) shall not apply to any taxable year beginning after the date on which the aggregate savings from the elimination of the deductions and credits for millionaires attributable to the enactment of sections 4 through 11 of the Small Business Jobs and Tax Relief Act matches dollar for dollar the decrease in revenue attributable to the enactment of sections 2 and 3 of such Act.”.
(b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2011.
SEC. _. NO RESIDENTIAL ENERGY EFFICIENT PROPERTY CREDIT FOR MILLIONAIRES AND BILLIONAIRES.
(a) In General.--Section 25D(e) of the Internal Revenue Code of 1986 is amended by adding at the end the following new paragraph:
“(9) No credit for millionaires and billionaires.--
“(A) In general.--Except as provided in subparagraph (B), no credit shall be allowed under this section for any taxable year with respect to any taxpayer with an adjusted gross income equal to or greater than $1,000,000 for such taxable year.
“(B) Termination.--Subparagraph (A) shall not apply to any taxable year beginning after the date on which the aggregate savings from the elimination of the deductions and credits for millionaires attributable to the enactment of sections 4 through 11 of the Small Business Jobs and Tax Relief Act matches dollar for dollar the decrease in revenue attributable to the enactment of sections 2 and 3 of such Act.”.
(b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2011.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
July 12, 2012