An amendment to insert a new section providing funding for affordable rental housing for extremely low-income families by improving targeting of mortgage interest deductions.
What it does: Inserts new text on page 156, line 16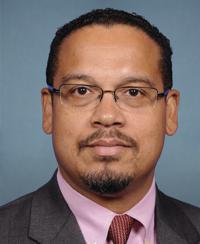 Rep. Keith Ellison (D-MN)
What it changes
1 change to H.R. 4745
Inserts new text on page 156, line 16
InsertsPrinted pageInserted: providing funding for affordable rental housing for extremely low-income families by improving targeting of mortgage interest deduction
Inserted: Sec. 417. (a) Replacement of Mortgage Interest Deduction With Mortgage Interest Credit.--
Inserted: (1) Nonrefundable Credit.--Subpart A of part IV of subchapter A of chapter 1 of the Internal Revenue Code of 1986 (relating to nonrefundable personal credits) is amended by inserting after section 25D the following new section:
Inserted: "SEC. 25E. INTEREST ON INDEBTEDNESS SECURED BY QUALIFIED RESIDENCE.
Inserted: "(a) Allowance of Credit.--In the case of an individual, there shall be allowed as a credit against the tax imposed by this chapter for the taxable year an amount equal to 15 percent of the qualified residence interest paid or accrued during the taxable year.
Inserted: "(b) Qualified Residence Interest.-- For purposes of this section:
Inserted: "(1) In general.--The term 'qualified residence interest' means interest which is paid or accrued during the taxable year on--
Inserted: "(A) acquisition indebtedness with respect to any qualified residence of the taxpayer, or
Inserted: "(B) home equity indebtedness with respect to any qualified residence of the taxpayer.
Inserted: For purposes of the preceding sentence, the determination of whether any property is a qualified residence of the taxpayer shall be made as of the time the interest is accrued.
Inserted: "(2) Overall limitation.--The aggregate amount of indebtedness taken into account for any period for purposes of this section shall not exceed $500,000 ($250,000 in the case of a married individual filing a separate return).
Inserted: "(3) Acquisition indebtedness.--The term 'acquisition indebtedness' means any indebtedness which--
Show 44 more inserted paragraphsShow less
Inserted: "(A) is incurred in acquiring, constructing, or substantially improving any qualified residence of the taxpayer, and
Inserted: "(B) is secured by such residence.
Inserted: Such term also includes any indebtedness secured by such residence resulting from the refinancing of indebtedness meeting the requirements of the preceding sentence (or this sentence), but only to the extent the amount of the indebtedness resulting from such refinancing does not exceed the amount of the refinanced indebtedness.
Inserted: "(4) Home equity indebtedness.--
Inserted: "(A) In general.--The term 'home equity indebtedness' means any indebtedness (other than acquisition indebtedness) secured by a qualified residence to the extent the aggregate amount of such indebtedness does not exceed--
Inserted: "(i) the fair market value of such qualified residence, reduced by
Inserted: "(ii) the amount of acquisition indebtedness with respect to such residence.
Inserted: "(B) Limitation.--The aggregate amount treated as home equity indebtedness for any period shall not exceed $100,000 ($50,000 in the case of a married individual filing a separate return).
Inserted: "(c) Special Rules.--For purposes of this section:
Inserted: "(1) Qualified residence.--The term 'qualified residence' means--
Inserted: "(A) the principal residence (within the meaning of section 121) of the taxpayer, and
Inserted: "(B) 1 other residence of the taxpayer which is selected by the taxpayer for purposes of this subsection for the taxable year and which is used by the taxpayer as a residence (within the meaning of section 280A(d)(1)).
Inserted: "(2) Married individuals filing separate returns.--If a married couple does not file a joint return for the taxable year--
Inserted: "(A) such couple shall be treated as 1 taxpayer for purposes of paragraph (1), and
Inserted: "(B) each individual shall be entitled to take into account 1 residence unless both individuals consent in writing to 1 individual taking into account the principal residence and 1 other residence.
Inserted: "(3) Residence not rented.--For purposes of paragraph (1)(B), notwithstanding section 280A(d)(1), if the taxpayer does not rent a dwelling unit at any time during a taxable year, such unit may be treated as a residence for such taxable year.
Inserted: "(4) Unenforceable security interests.--Indebtedness shall not fail to be treated as secured by any property solely because, under any applicable State or local homestead or other debtor protection law in effect on August 16, 1986, the security interest is ineffective or the enforceability of the security interest is restricted.
Inserted: "(5) Special rules for estates and trusts.--For purposes of determining whether any interest paid or accrued by an estate or trust is qualified residence interest, any residence held by such estate or trust shall be treated as a qualified residence of such estate or trust if such estate or trust establishes that such residence is a qualified residence of a beneficiary who has a present interest in such estate or trust or an interest in the residuary of such estate or trust.
Inserted: "(d) Coordination With Deduction.--In the case of any taxable year beginning in calendar years 2014 through 2018, the taxpayer may elect to apply this section in lieu of the deduction under section 163 for qualified residence interest.".
Inserted: (2) Phaseout of Deduction.--Section 163(h) of such Code is amended by adding at the end the following new paragraph:
Inserted: "(6) Phaseout.--
Inserted: "(A) In general.--In the case of any taxable year beginning in a calendar year after 2013, the amount otherwise allowable as a deduction by reason of paragraph (2)(D) shall be the applicable percentage of such amount.
Inserted: "(B) Applicable percentage.--For purposes of subparagraph (A), the applicable percentage shall be determined in accordance with the following table:
Inserted: ------------------------------------------------------------------------The applicable "For taxable years beginning in calendar year: percentage is:
Inserted: 2014.................................................... 100% 2015.................................................... 80% 2016.................................................... 60% 2017.................................................... 40% 2018.................................................... 20% 2019 and thereafter..................................... 0%.".
Inserted: (3) Phasedown of Mortgage Limit.--Subparagraph (B) of section 163(h)(3) of such Code is amended by adding at the end the following:
Inserted: "(iii) Phasedown.--
Inserted: "(I) In general.--In the case of any taxable year beginning in calendar years 2014 through 2018, clause (ii) shall be applied by substituting the amounts specified in the table in subclause (II) of this clause for '$1,000,000' and '$500,000', respectively.
Inserted: "(II) Phasedown amounts.--For purposes of subclause (I), the amounts specified in this subclause for a taxable year shall be the amounts specified in the following table:
Inserted: ------------------------------------------------------------------------Amount Amount "For taxable years beginning in calendar substituted substituted year: for for $1,000,000: $500,000:
Inserted: 2014.......................................... $1,000,000 $500,000 2015.......................................... $900,000 $450,000 2016.......................................... $800,000 $400,000 2017.......................................... $700,000 $350,000 2018.......................................... $600,000 $300,000
Inserted: (4) Clerical Amendment.--The table of sections for subpart A of part IV of subchapter A of chapter 1 of such Code is amended by inserting after section 25D the following new item:
Inserted: "Sec. 25E. Interest on indebtedness secured by qualified residence.".
Inserted: (5) Effective Date.--The amendments made by this subsection shall apply with respect to interest paid or accrued after December 31, 2013.
Inserted: (b) Use of Mortgage Interest Savings for Affordable Housing Programs.--
Inserted: (1) Use of Savings.--For each year, the Secretary of the Treasury shall determine the amount of revenues accruing to the general fund of the Treasury by reason of the enactment of subsection (a) of this section and shall credit an amount equal to such remaining revenues as follows:
Inserted: (A) Housing trust fund.--The Secretary shall credit the Housing Trust Fund established under section 1338 of the Federal Housing Enterprises Financial Safety and Soundness Act of 1992 (12 U.S.C. 4568) with an amount equal to 40 percent revenues.
Inserted: (B) Section 8 rental assistance.--The Secretary shall credit an amount equal to 40 percent of the amount of such remaining revenues to the Secretary of Housing and Urban Development for use only for providing tenant- and project-based rental assistance under section 8 of the United States Housing Act of 1937 (42 U.S.C. 1437f).
Inserted: (C) Public housing capital fund.--The Secretary shall credit an amount equal to 20 percent of the amount of such remaining revenues to the Public Housing Capital Fund under section 9(d) of the United States Housing Act of 1937 (42 U.S.C. 1437g(d)).
Inserted: (2) Changes to Housing Trust Fund.--Not later than the expiration of the 6-month period beginning on the date of the enactment of this Act, the Secretary of Housing and Urban Development shall revise the regulations relating to the Housing Trust Fund established under section 1338 of the Federal Housing Enterprises Financial Safety and Soundness Act of 1992 (12 U.S.C. 4568) to provide that such section is carried out with the maximum amount of flexibility possible while complying with such section, which shall include revising such regulations--
Inserted: (A) to increase the limitation on amounts from the Fund that are available for use for operating assistance for housing;
Inserted: (B) to allow public housing agencies and tribally designated housing entities to be recipient of grants amounts from the Fund that are allocated to a State or State designated entity; and
Inserted: (C) to eliminate the applicability of rules for the Fund that are based on the HOME Investment Partnerships Act (42 U.S.C. 1721 et seq.).
Inserted: (3) Expansion of Rental Assistance Demonstration.--The fourth proviso in the heading "Rental Assistance Demonstration" in title II of the Transportation, Housing and Urban Development, and Related Agencies Appropriations Act, 2012 (division C of Public Law 112-55; 125 Stat. 673) is amended by striking "60,000" and inserting "250,000".
Original wording
Page 156, after line 16, insert the following new section:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
Page 156, after line 16, insert the following new section:
providing funding for affordable rental housing for extremely low-
income families by improving targeting of mortgage interest deduction
Sec. 417. (a) Replacement of Mortgage Interest Deduction With Mortgage Interest Credit.--
(1) Nonrefundable Credit.--Subpart A of part IV of subchapter A of chapter 1 of the Internal Revenue Code of 1986 (relating to nonrefundable personal credits) is amended by inserting after section 25D the following new section:
“SEC. 25E. INTEREST ON INDEBTEDNESS SECURED BY QUALIFIED RESIDENCE.
“(a) Allowance of Credit.--In the case of an individual, there shall be allowed as a credit against the tax imposed by this chapter for the taxable year an amount equal to 15 percent of the qualified residence interest paid or accrued during the taxable year.
“(b) Qualified Residence Interest.-- For purposes of this section:
“(1) In general.--The term ‘qualified residence interest' means interest which is paid or accrued during the taxable year on--
“(A) acquisition indebtedness with respect to any qualified residence of the taxpayer, or
“(B) home equity indebtedness with respect to any qualified residence of the taxpayer.
For purposes of the preceding sentence, the determination of whether any property is a qualified residence of the taxpayer shall be made as of the time the interest is accrued.
“(2) Overall limitation.--The aggregate amount of indebtedness taken into account for any period for purposes of this section shall not exceed $500,000 ($250,000 in the case of a married individual filing a separate return).
“(3) Acquisition indebtedness.--The term ‘acquisition indebtedness' means any indebtedness which--
“(A) is incurred in acquiring, constructing, or substantially improving any qualified residence of the taxpayer, and
“(B) is secured by such residence.
Such term also includes any indebtedness secured by such residence resulting from the refinancing of indebtedness meeting the requirements of the preceding sentence (or this sentence), but only to the extent the amount of the indebtedness resulting from such refinancing does not exceed the amount of the refinanced indebtedness.
“(4) Home equity indebtedness.--
“(A) In general.--The term ‘home equity indebtedness' means any indebtedness (other than acquisition indebtedness) secured by a qualified residence to the extent the aggregate amount of such indebtedness does not exceed--
“(i) the fair market value of such qualified residence, reduced by
“(ii) the amount of acquisition indebtedness with respect to such residence.
“(B) Limitation.--The aggregate amount treated as home equity indebtedness for any period shall not exceed $100,000 ($50,000 in the case of a married individual filing a separate return).
“(c) Special Rules.--For purposes of this section:
“(1) Qualified residence.--The term ‘qualified residence' means--
“(A) the principal residence (within the meaning of section 121) of the taxpayer, and
“(B) 1 other residence of the taxpayer which is selected by the taxpayer for purposes of this subsection for the taxable year and which is used by the taxpayer as a residence (within the meaning of section 280A(d)(1)).
“(2) Married individuals filing separate returns.--If a married couple does not file a joint return for the taxable year--
“(A) such couple shall be treated as 1 taxpayer for purposes of paragraph (1), and
“(B) each individual shall be entitled to take into account 1 residence unless both individuals consent in writing to 1 individual taking into account the principal residence and 1 other residence.
“(3) Residence not rented.--For purposes of paragraph (1)(B), notwithstanding section 280A(d)(1), if the taxpayer does not rent a dwelling unit at any time during a taxable year, such unit may be treated as a residence for such taxable year.
“(4) Unenforceable security interests.--Indebtedness shall not fail to be treated as secured by any property solely because, under any applicable State or local homestead or other debtor protection law in effect on August 16, 1986, the security interest is ineffective or the enforceability of the security interest is restricted.
“(5) Special rules for estates and trusts.--For purposes of determining whether any interest paid or accrued by an estate or trust is qualified residence interest, any residence held by such estate or trust shall be treated as a qualified residence of such estate or trust if such estate or trust establishes that such residence is a qualified residence of a beneficiary who has a present interest in such estate or trust or an interest in the residuary of such estate or trust.
“(d) Coordination With Deduction.--In the case of any taxable year beginning in calendar years 2014 through 2018, the taxpayer may elect to apply this section in lieu of the deduction under section 163 for qualified residence interest.”.
(2) Phaseout of Deduction.--Section 163(h) of such Code is amended by adding at the end the following new paragraph:
“(6) Phaseout.--
“(A) In general.--In the case of any taxable year beginning in a calendar year after 2013, the amount otherwise allowable as a deduction by reason of paragraph (2)(D) shall be the applicable percentage of such amount.
“(B) Applicable percentage.--For purposes of subparagraph (A), the applicable percentage shall be determined in accordance with the following table:
------------------------------------------------------------------------The applicable “For taxable years beginning in calendar year: percentage is:
------------------------------------------------------------------------
2014.................................................... 100%
2015.................................................... 80%
2016.................................................... 60%
2017.................................................... 40%
2018.................................................... 20%
2019 and thereafter..................................... 0%.”.
------------------------------------------------------------------------
(3) Phasedown of Mortgage Limit.--Subparagraph (B) of section 163(h)(3) of such Code is amended by adding at the end the following:
“(iii) Phasedown.--
“(I) In general.--In the case of any taxable year beginning in calendar years 2014 through 2018, clause (ii) shall be applied by substituting the amounts specified in the table in subclause (II) of this clause for ‘$1,000,000' and ‘$500,000', respectively.
“(II) Phasedown amounts.--For purposes of subclause (I), the amounts specified in this subclause for a taxable year shall be the amounts specified in the following table:
------------------------------------------------------------------------Amount Amount
“For taxable years beginning in calendar substituted substituted year: for for $1,000,000: $500,000:
------------------------------------------------------------------------
2014.......................................... $1,000,000 $500,000
2015.......................................... $900,000 $450,000
2016.......................................... $800,000 $400,000
2017.......................................... $700,000 $350,000
2018.......................................... $600,000 $300,000
------------------------------------------------------------------------
(4) Clerical Amendment.--The table of sections for subpart A of part IV of subchapter A of chapter 1 of such Code is amended by inserting after section 25D the following new item:
“Sec. 25E. Interest on indebtedness secured by qualified residence.”.
(5) Effective Date.--The amendments made by this subsection shall apply with respect to interest paid or accrued after December 31, 2013.
(b) Use of Mortgage Interest Savings for Affordable Housing Programs.--
(1) Use of Savings.--For each year, the Secretary of the Treasury shall determine the amount of revenues accruing to the general fund of the Treasury by reason of the enactment of subsection (a) of this section and shall credit an amount equal to such remaining revenues as follows:
(A) Housing trust fund.--The Secretary shall credit the Housing Trust Fund established under section 1338 of the Federal Housing Enterprises Financial Safety and Soundness Act of 1992 (12 U.S.C. 4568) with an amount equal to 40 percent revenues.
(B) Section 8 rental assistance.--The Secretary shall credit an amount equal to 40 percent of the amount of such remaining revenues to the Secretary of Housing and Urban Development for use only for providing tenant- and project-based rental assistance under section 8 of the United States Housing Act of 1937 (42 U.S.C. 1437f).
(C) Public housing capital fund.--The Secretary shall credit an amount equal to 20 percent of the amount of such remaining revenues to the Public Housing Capital Fund under section 9(d) of the United States Housing Act of 1937 (42 U.S.C. 1437g(d)).
(2) Changes to Housing Trust Fund.--Not later than the expiration of the 6-month period beginning on the date of the enactment of this Act, the Secretary of Housing and Urban Development shall revise the regulations relating to the Housing Trust Fund established under section 1338 of the Federal Housing Enterprises Financial Safety and Soundness Act of 1992 (12 U.S.C. 4568) to provide that such section is carried out with the maximum amount of flexibility possible while complying with such section, which shall include revising such regulations--
(A) to increase the limitation on amounts from the Fund that are available for use for operating assistance for housing;
(B) to allow public housing agencies and tribally designated housing entities to be recipient of grants amounts from the Fund that are allocated to a State or State designated entity; and
(C) to eliminate the applicability of rules for the Fund that are based on the HOME Investment Partnerships Act (42 U.S.C. 1721 et seq.).
(3) Expansion of Rental Assistance Demonstration.--The fourth proviso in the heading “Rental Assistance Demonstration” in title II of the Transportation, Housing and Urban Development, and Related Agencies Appropriations Act, 2012 (division C of Public Law 112-55; 125 Stat. 673) is amended by striking “60,000” and inserting “250,000”.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
House amendment offered
June 10, 2014
View full timeline
House amendment offered
June 10, 2014
House amendment offered/reported by: Amendment (A059) offered by Mr. Ellison.(consideration: CR H5224-5225; text: CR H5224)
June 10, 2014 • 4:44 PM
Amendment (A059) offered by Mr. Ellison. (consideration: CR H5224-5225; text: CR H5224)
June 10, 2014 • 4:44 PM
By unanimous consent, the Ellison amendment was withdrawn. (consideration: CR H5225)
June 10, 2014 • 4:48 PM