S.Amdt. 2413
What it does: Rewrites title LII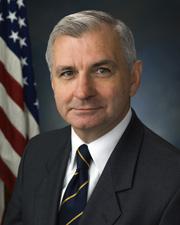 Sen. Jack Reed (D-RI)
What it changes
1 change to H.R. 22
Rewrites title LII
ReplacesRemoves title LII.
Inserted: TITLE LII--OFFSETS
Inserted: SEC. 52101. EXPANSION OF DENIAL OF DEDUCTION FOR CERTAIN EXCESSIVE EMPLOYEE REMUNERATION.
Inserted: (a) Application to All Current and Former Employees.--
Inserted: (1) In general.--Section 162(m) of the Internal Revenue Code of 1986 is amended--
Inserted: (A) by striking "covered employee" each place it appears in paragraphs (1) and (4) and inserting "covered individual", and
Inserted: (B) by striking "such employee" each place it appears in subparagraphs (A) and (G) of paragraph (4) and inserting "such individual".
Inserted: (2) Covered individual.--Paragraph (3) of section 162(m) of such Code is amended to read as follows:
Inserted: "(3) Covered individual.--For purposes of this subsection, the term 'covered individual' means any individual who is an officer, director, or employee of the taxpayer or a former officer, director, or employee of the taxpayer.".
Inserted: (3) Conforming amendments.--
Inserted: (A) Section 48D(b)(3)(A) of such Code is amended by inserting "(as in effect for taxable years beginning before January 1, 2015)" after "section 162(m)(3)".
Inserted: (B) Section 409A(b)(3)(D)(ii) of such Code is amended by inserting "(as in effect for taxable years beginning before January 1, 2015)" after "section 162(m)(3)".
Inserted: (b) Expansion of Applicable Employee Remuneration.--
Show 27 more inserted paragraphsShow less
Inserted: (1) Elimination of exception for commission-based pay.--
Inserted: (A) In general.--Paragraph (4) of section 162(m) of such Code, as amended by subsection (a), is amended by striking subparagraph (B) and by redesignating subparagraphs (C) through (G) as subparagraphs (B) through (F), respectively.
Inserted: (B) Conforming amendments.--
Inserted: (i) Section 162(m)(5) of such Code is amended--
Inserted: (I) by striking "subparagraphs (B), (C), and (D) thereof" in subparagraph (E) and inserting "subparagraphs (B) and (C) thereof", and
Inserted: (II) by striking "subparagraphs (F) and (G)" in subparagraph (G) and inserting "subparagraphs (E) and (F)".
Inserted: (ii) Section 162(m)(6) of such Code is amended--
Inserted: (I) by striking "subparagraphs (B), (C), and (D) thereof" in subparagraph (D) and inserting "subparagraphs (B) and (C) thereof", and
Inserted: (II) by striking "subparagraphs (F) and (G)" in subparagraph (G) and inserting "subparagraphs (E) and (F)".
Inserted: (2) Inclusion of performance-based compensation.--
Inserted: (A) In general.--Paragraph (4) of section 162(m) of the Internal Revenue Code of 1986, as amended by subsection (a) and paragraph (1) of this subsection, is amended by striking subparagraph (B) and redesignating subparagraphs (C) through (F) as subparagraphs (B) through (E), respectively.
Inserted: (B) Conforming amendments.--
Inserted: (i) Section 162(m)(5) of such Code, as amended by paragraph (1), is amended--
Inserted: (I) by striking "subparagraphs (B) and (C) thereof" in subparagraph (E) and inserting "subparagraph (B) thereof", and
Inserted: (II) by striking "subparagraphs (E) and (F)" in subparagraph (G) and inserting "subparagraphs (D) and (E)".
Inserted: (ii) Section 162(m)(6) of such Code, as amended by paragraph (1), is amended--
Inserted: (I) by striking "subparagraphs (B) and (C) thereof" in subparagraph (D) and inserting "subparagraph (B) thereof", and
Inserted: (II) by striking "subparagraphs (E) and (F)" in subparagraph (G) and inserting "subparagraphs (D) and (E)".
Inserted: (c) Expansion of Applicable Employer.--Paragraph (2) of section 162(m) of the Internal Revenue Code of 1986 is amended to read as follows:
Inserted: "(2) Publicly held corporation.--For purposes of this subsection, the term 'publicly held corporation' means any corporation which is an issuer (as defined in section 3 of the Securities Exchange Act of 1934 (15 U.S.C. 78c))--
Inserted: "(A) the securities of which are registered under section 12 of such Act (15 U.S.C. 78l), or
Inserted: "(B) that is required to file reports under section 15(d) of such Act (15 U.S.C. 780(d)).".
Inserted: (d) Regulatory Authority.--
Inserted: (1) In general.--Section 162(m) of the Internal Revenue Code of 1986 is amended by adding at the end the following new paragraph:
Inserted: "(7) Regulations.--The Secretary may prescribe such guidance, rules, or regulations, including with respect to reporting, as are necessary to carry out the purposes of this subsection.".
Inserted: (2) Conforming amendment.--Paragraph (6) of section 162(m) of such Code is amended by striking subparagraph (H).
Inserted: (e) Effective Date.--The amendments made by this section shall apply to taxable years beginning after December 31, 2015.
Original wording
Strike title LII and insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 2413. Mr. REED (for himself and Mr. Brown) submitted an amendment intended to be proposed by him to the bill H.R. 22, to amend the Internal Revenue Code of 1986 to exempt employees with health coverage under TRICARE or the Veterans Administration from being taken into account for purposes of determining the employers to which the employer mandate applies under the Patient Protection and Affordable Care Act; which was ordered to lie on the table; as follows:
Strike title LII and insert the following:
TITLE LII--OFFSETS
SEC. 52101. EXPANSION OF DENIAL OF DEDUCTION FOR CERTAIN EXCESSIVE EMPLOYEE REMUNERATION.
(a) Application to All Current and Former Employees.--
(1) In general.--Section 162(m) of the Internal Revenue Code of 1986 is amended--
(A) by striking “covered employee” each place it appears in paragraphs (1) and (4) and inserting “covered individual”, and
(B) by striking “such employee” each place it appears in subparagraphs (A) and (G) of paragraph (4) and inserting “such individual”.
(2) Covered individual.--Paragraph (3) of section 162(m) of such Code is amended to read as follows:
“(3) Covered individual.--For purposes of this subsection, the term ‘covered individual' means any individual who is an officer, director, or employee of the taxpayer or a former officer, director, or employee of the taxpayer.”.
(3) Conforming amendments.--
(A) Section 48D(b)(3)(A) of such Code is amended by inserting “(as in effect for taxable years beginning before January 1, 2015)” after “section 162(m)(3)”.
(B) Section 409A(b)(3)(D)(ii) of such Code is amended by inserting “(as in effect for taxable years beginning before January 1, 2015)” after “section 162(m)(3)”.
(b) Expansion of Applicable Employee Remuneration.--
(1) Elimination of exception for commission-based pay.--
(A) In general.--Paragraph (4) of section 162(m) of such Code, as amended by subsection (a), is amended by striking subparagraph (B) and by redesignating subparagraphs (C) through (G) as subparagraphs (B) through (F), respectively.
(B) Conforming amendments.--
(i) Section 162(m)(5) of such Code is amended--
(I) by striking “subparagraphs (B), (C), and (D) thereof” in subparagraph (E) and inserting “subparagraphs (B) and (C) thereof”, and
(II) by striking “subparagraphs (F) and (G)” in subparagraph (G) and inserting “subparagraphs (E) and (F)”.
(ii) Section 162(m)(6) of such Code is amended--
(I) by striking “subparagraphs (B), (C), and (D) thereof” in subparagraph (D) and inserting “subparagraphs (B) and (C) thereof”, and
(II) by striking “subparagraphs (F) and (G)” in subparagraph (G) and inserting “subparagraphs (E) and (F)”.
(2) Inclusion of performance-based compensation.--
(A) In general.--Paragraph (4) of section 162(m) of the Internal Revenue Code of 1986, as amended by subsection (a) and paragraph (1) of this subsection, is amended by striking subparagraph (B) and redesignating subparagraphs (C) through (F) as subparagraphs (B) through (E), respectively.
(B) Conforming amendments.--
(i) Section 162(m)(5) of such Code, as amended by paragraph (1), is amended--
(I) by striking “subparagraphs (B) and (C) thereof” in subparagraph (E) and inserting “subparagraph (B) thereof”, and
(II) by striking “subparagraphs (E) and (F)” in subparagraph (G) and inserting “subparagraphs (D) and (E)”.
(ii) Section 162(m)(6) of such Code, as amended by paragraph (1), is amended--
(I) by striking “subparagraphs (B) and (C) thereof” in subparagraph (D) and inserting “subparagraph (B) thereof”, and
(II) by striking “subparagraphs (E) and (F)” in subparagraph (G) and inserting “subparagraphs (D) and (E)”.
(c) Expansion of Applicable Employer.--Paragraph (2) of section 162(m) of the Internal Revenue Code of 1986 is amended to read as follows:
“(2) Publicly held corporation.--For purposes of this subsection, the term ‘publicly held corporation' means any corporation which is an issuer (as defined in section 3 of the Securities Exchange Act of 1934 (15 U.S.C. 78c))--
“(A) the securities of which are registered under section 12 of such Act (15 U.S.C. 78l), or
“(B) that is required to file reports under section 15(d) of such Act (15 U.S.C. 780(d)).”.
(d) Regulatory Authority.--
(1) In general.--Section 162(m) of the Internal Revenue Code of 1986 is amended by adding at the end the following new paragraph:
“(7) Regulations.--The Secretary may prescribe such guidance, rules, or regulations, including with respect to reporting, as are necessary to carry out the purposes of this subsection.”.
(2) Conforming amendment.--Paragraph (6) of section 162(m) of such Code is amended by striking subparagraph (H).
(e) Effective Date.--The amendments made by this section shall apply to taxable years beginning after December 31, 2015.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
July 26, 2015
View full timeline
Senate amendment submitted
July 26, 2015
Senate amendment submitted
July 26, 2015