S.Amdt. 2425
What it does: Adds TITLE LXII--FUEL TAXES at the end of division F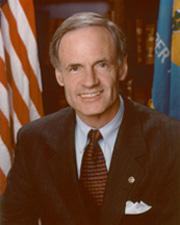 Sen. Thomas R. Carper (D-DE)
What it changes
1 change to H.R. 22
Adds TITLE LXII--FUEL TAXES at the end of division F
Adds a titleInserted: TITLE LXII--FUEL TAXES
Inserted: SEC. 62001. ADJUSTING TAX ON GASOLINE FOR INFLATION.
Inserted: (a) Adjustment for Inflation.--
Inserted: (1) In general.--Paragraph (2) of section 4081(a) of the Internal Revenue Code of 1986 is amended by adding at the end the following new subparagraph:
Inserted: "(E) Adjustment for inflation.--
Inserted: "(i) In general.--In the case of gasoline removed, entered, or sold in a calendar year after 2015, the 18.3 cents amount in subparagraph (A)(i) shall be increased by an amount equal to--
Inserted: "(I) such cents amount, multiplied by
Inserted: "(II) the cost-of-living adjustment determined under section 1(f)(3) for such calendar year by substituting 'calendar year 2014' for 'calendar year 1992' in subparagraph (B) thereof.
Inserted: "(ii) Rounding.--If the amount as increased under clause (i) is not a multiple of 0.1 cents, such amount shall be rounded to the nearest multiple of 0.1 cents.".
Inserted: (2) Effective date.--The amendment made by this subsection shall apply to gasoline removed, entered, or sold after December 31, 2015.
Inserted: (b) Conforming Amendment Relating to Tax on Compressed Natural Gas.--
Inserted: (1) In general.--The second sentence of subparagraph (A) of section 4041(a)(3) of the Internal Revenue Code of 1986 is amended by striking "18.3 cents" and inserting "equal to the rate of tax in effect under section 4081(a)(2)(A)(i) for the calendar year in which such gas is sold or used,".
Show 52 more inserted paragraphsShow less
Inserted: (2) Effective date.--The amendment made by this subsection shall apply to compressed natural gas sold or used on or after the first day of the first calendar quarter beginning not less than 60 days after the date of the enactment of this Act.
Inserted: (c) Conforming Amendment Relating to Tax on Methanol and Ethanol.--
Inserted: (1) In general.--Paragraph (1) of section 4041(m) of the Internal Revenue Code of 1986 is amended by striking "shall be--" and all that follows and inserting "shall be equal to 61.7 percent of the rate of tax in effect under section 4081(a)(2)(A)(i) for the calendar year in which such fuel is sold or used.".
Inserted: (2) Effective date.--The amendment made by this subsection shall apply to methanol and ethanol fuel sold or used on or after the first day of the first calendar quarter beginning not less than 60 days after the date of the enactment of this Act.
Inserted: SEC. 62002. ADJUSTING TAX ON DIESEL FUEL AND KEROSENE FOR INFLATION.
Inserted: (a) Adjustment for Inflation.--Subparagraph (E) of section 4081(a)(2) of the Internal Revenue Code of 1986, as added by this title, is amended--
Inserted: (1) by redesignating clause (ii) as clause (iii),
Inserted: (2) by striking "If the amount as increased under clause (i)" in clause (iii), as so redesignated, and inserting "If any amount as increased under clause (i) or (ii)",
Inserted: (3) by striking "In general" in the heading of clause (i) and inserting "Tax on gasoline", and
Inserted: (4) by inserting after clause (i) the following new clause:
Inserted: "(ii) Tax on diesel fuel or kerosene.--In the case of diesel fuel or kerosene removed, entered, or sold in a calendar year after 2015, the 24.3 cents amount in subparagraph (A)(iii) shall be increased by an amount equal to--
Inserted: "(I) such cents amount, multiplied by
Inserted: "(II) the cost-of-living adjustment determined under section 1(f)(3) for such calendar year by substituting 'calendar year 2014' for 'calendar year 1992' in subparagraph (B) thereof.".
Inserted: (b) Conforming Amendment Relating to Tax on Diesel-water Fuel Emulsions.--Subparagraph (D) of section 4081(a)(2) of the Internal Revenue Code of 1986 is amended by striking "subparagraph (A)(iii) shall be applied by substituting '19.7 cents' for '24.3 cents' " and inserting "the rate of tax shall be equal to 81 percent of the rate of tax in effect under subparagraph (A)(iii) for the calendar year in which such emulsion is removed, entered, or sold".
Inserted: (c) Conforming Amendment Relating to Tax on Certain Alternative Fuels.--Clause (ii) of section 4041(a)(2)(B) of the Internal Revenue Code of 1986 is amended by striking "24.3 cents per gallon" and inserting "the rate of tax specified in section 4081(a)(2)(A)(iii) which is in effect at the time of such sale or use".
Inserted: (d) Conforming Amendment Relating to Rate of Tax on Buses.--Paragraph (2) of section 6427(b) of such Code is amended by adding at the end the following new subparagraph:
Inserted: "(E) Adjustment for inflation.--In the case of fuel used in a calendar year after 2015, the 7.4 cents amount in subparagraph (A) shall be increased by an amount equal to--
Inserted: "(i) such cents amount, multiplied by
Inserted: "(ii) the cost-of-living adjustment determined under section 1(f)(3) for such calendar year by substituting 'calendar year 2014' for 'calendar year 1992' in subparagraph (B) thereof.".
Inserted: (e) Effective Date.--The amendments made by this section shall apply to diesel fuel, kerosene, and diesel-water fuel emulsions removed, entered, or sold on or after the first day of the first calendar quarter beginning not less than 60 days after the date of the enactment of this Act.
Inserted: SEC. 62003. ALLOCATION IN ACCOUNTS IN HIGHWAY TRUST FUND.
Inserted: Section 9503(e) of the Internal Revenue Code of 1986 is amended by adding at the end the following new paragraph:
Inserted: "(6) Adjustment for inflation.--
Inserted: "(A) In general.--In the case of any calendar year beginning after 2015, the amount in subparagraph (A) of paragraph (2) shall be increased by an amount equal to--
Inserted: "(i) such amount, multiplied by
Inserted: "(ii) the cost-of-living adjustment determined under section 1(f)(3) for such calendar year by substituting 'calendar year 2014' for 'calendar year 1992' in subparagraph (B) thereof.
Inserted: "(B) Rounding.--Any increase under subparagraph (A) shall be rounded to the nearest 0.1 cents.".
Inserted: SEC. 62004. FLOOR STOCKS TAXES.
Inserted: (a) Imposition of Tax.--In the case of any taxable fuel which is held on the floor stocks tax date by any person, there is hereby imposed a floor stocks tax equal to the excess of the tax which would be imposed on such fuel under section 4041 or 4081 of the Internal Revenue Code of 1986 had the taxable event occurred on the floor stocks tax date over the tax paid under any such section on such fuel.
Inserted: (b) Liability for Tax and Method of Payment.--
Inserted: (1) Liability for tax.--A person holding a fuel on the floor stocks tax date to which the tax imposed by subsection (a) applies shall be liable for such tax.
Inserted: (2) Method of payment.--The tax imposed by subsection (a) shall be paid in such manner as the Secretary shall prescribe.
Inserted: (3) Time of payment.--The tax imposed by subsection (a) shall be paid on or before the date which is 6 months after the floor stocks tax date.
Inserted: (c) Definitions.--For purposes of this section--
Inserted: (1) Held by a person.--A fuel shall be considered as held by a person if title thereto has passed to such person (whether or not delivery to the person has been made).
Inserted: (2) Taxable fuel.--The term "taxable fuel" means--
Inserted: (A) gasoline (other than aviation gasoline), diesel fuel, kerosene (other than aviation-grade kerosene), and diesel-water fuel emulsions;
Inserted: (B) fuel taxed under section 4041(a)(2) of the Internal Revenue Code of 1986 (including methanol and ethanol to which section 4041(m) of such Code applies); and
Inserted: (C) compressed natural gas.
Inserted: (3) Floor stocks date.--The term "floor stocks tax date" means January 1 of any calendar year beginning after the date of the enactment of this Act on which a rate of tax under section 4041 or 4081 of such Code increases pursuant to an amendment made by section 62001 or 62002.
Inserted: (4) Secretary.--The term "Secretary" means the Secretary of the Treasury.
Inserted: (d) Exception for Exempt Uses.--The tax imposed by subsection (a) shall not apply to taxable fuel held by any person exclusively for any use to the extent a credit or refund of the tax imposed by a section of such Code is allowable for such use.
Inserted: (e) Exception for Fuel Held in Vehicle Tank.--No tax shall be imposed by subsection (a) on taxable fuel held in the tank of a motor vehicle or motorboat.
Inserted: (f) Exception for Certain Amounts of Fuel.--
Inserted: (1) In general.--No tax shall be imposed by subsection (a) on any fuel held on the floor stocks tax date by any person if the aggregate amount of fuel held by such person on such date does not exceed 2,000 gallons. The preceding sentence shall apply only if such person submits to the Secretary (at the time and in the manner required by the Secretary) such information as the Secretary shall require for purposes of this paragraph.
Inserted: (2) Exempt fuel.--For purposes of paragraph (1), there shall not be taken into account fuel held by any person which is exempt from the tax imposed by subsection (a) by reason of subsection (d) or (e).
Inserted: (3) Controlled groups.--For purposes of this section--
Inserted: (A) Corporations.--
Inserted: (i) In general.--All persons treated as a controlled group shall be treated as 1 person.
Inserted: (ii) Controlled group.--The term "controlled group" has the meaning given to such term by subsection (a) of section 1563 of such Code; except that for such purposes the phrase "more than 50 percent" shall be substituted for the phrase "at least 80 percent" each place it appears in such subsection.
Inserted: (B) Nonincorporated persons under common control.--Under regulations prescribed by the Secretary, principles similar to the principles of clause (i) shall apply to a group of persons under common control where one or more of such persons is not a corporation.
Inserted: (g) Other Laws Applicable.--All provisions of law, including penalties, applicable with respect to the taxes imposed by chapter 31 or 32 of such Code shall, insofar as applicable and not inconsistent with the provisions of this section, apply with respect to the floor stock taxes imposed by subsection (a) to the same extent as if such taxes were imposed by such chapter.
Original wording
At the end of division F, add the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 2425. Mr. CARPER submitted an amendment intended to be proposed by him to the bill H.R. 22, to amend the Internal Revenue Code of 1986 to exempt employees with health coverage under TRICARE or the Veterans Administration from being taken into account for purposes of determining the employers to which the employer mandate applies under the Patient Protection and Affordable Care Act; which was ordered to lie on the table; as follows:
At the end of division F, add the following:
TITLE LXII--FUEL TAXES
SEC. 62001. ADJUSTING TAX ON GASOLINE FOR INFLATION.
(a) Adjustment for Inflation.--
(1) In general.--Paragraph (2) of section 4081(a) of the Internal Revenue Code of 1986 is amended by adding at the end the following new subparagraph:
“(E) Adjustment for inflation.--
“(i) In general.--In the case of gasoline removed, entered, or sold in a calendar year after 2015, the 18.3 cents amount in subparagraph (A)(i) shall be increased by an amount equal to--
“(I) such cents amount, multiplied by
“(II) the cost-of-living adjustment determined under section 1(f)(3) for such calendar year by substituting ‘calendar year 2014' for ‘calendar year 1992' in subparagraph (B) thereof.
“(ii) Rounding.--If the amount as increased under clause (i) is not a multiple of 0.1 cents, such amount shall be rounded to the nearest multiple of 0.1 cents.”.
(2) Effective date.--The amendment made by this subsection shall apply to gasoline removed, entered, or sold after December 31, 2015.
(b) Conforming Amendment Relating to Tax on Compressed Natural Gas.--
(1) In general.--The second sentence of subparagraph (A) of section 4041(a)(3) of the Internal Revenue Code of 1986 is amended by striking “18.3 cents” and inserting “equal to the rate of tax in effect under section 4081(a)(2)(A)(i) for the calendar year in which such gas is sold or used,”.
(2) Effective date.--The amendment made by this subsection shall apply to compressed natural gas sold or used on or after the first day of the first calendar quarter beginning not less than 60 days after the date of the enactment of this Act.
(c) Conforming Amendment Relating to Tax on Methanol and Ethanol.--
(1) In general.--Paragraph (1) of section 4041(m) of the Internal Revenue Code of 1986 is amended by striking “shall be--” and all that follows and inserting “shall be equal to 61.7 percent of the rate of tax in effect under section 4081(a)(2)(A)(i) for the calendar year in which such fuel is sold or used.”.
(2) Effective date.--The amendment made by this subsection shall apply to methanol and ethanol fuel sold or used on or after the first day of the first calendar quarter beginning not less than 60 days after the date of the enactment of this Act.
SEC. 62002. ADJUSTING TAX ON DIESEL FUEL AND KEROSENE FOR INFLATION.
(a) Adjustment for Inflation.--Subparagraph (E) of section 4081(a)(2) of the Internal Revenue Code of 1986, as added by this title, is amended--
(1) by redesignating clause (ii) as clause (iii),
(2) by striking “If the amount as increased under clause (i)” in clause (iii), as so redesignated, and inserting “If any amount as increased under clause (i) or (ii)”,
(3) by striking “In general” in the heading of clause (i) and inserting “Tax on gasoline”, and
(4) by inserting after clause (i) the following new clause:
“(ii) Tax on diesel fuel or kerosene.--In the case of diesel fuel or kerosene removed, entered, or sold in a calendar year after 2015, the 24.3 cents amount in subparagraph (A)(iii) shall be increased by an amount equal to--
“(I) such cents amount, multiplied by
“(II) the cost-of-living adjustment determined under section 1(f)(3) for such calendar year by substituting ‘calendar year 2014' for ‘calendar year 1992' in subparagraph (B) thereof.”.
(b) Conforming Amendment Relating to Tax on Diesel-water Fuel Emulsions.--Subparagraph (D) of section 4081(a)(2) of the Internal Revenue Code of 1986 is amended by striking “subparagraph (A)(iii) shall be applied by substituting ‘19.7 cents' for ‘24.3 cents' ” and inserting “the rate of tax shall be equal to 81 percent of the rate of tax in effect under subparagraph (A)(iii) for the calendar year in which such emulsion is removed, entered, or sold”.
(c) Conforming Amendment Relating to Tax on Certain Alternative Fuels.--Clause (ii) of section 4041(a)(2)(B) of the Internal Revenue Code of 1986 is amended by striking “24.3 cents per gallon” and inserting “the rate of tax specified in section 4081(a)(2)(A)(iii) which is in effect at the time of such sale or use”.
(d) Conforming Amendment Relating to Rate of Tax on Buses.--Paragraph (2) of section 6427(b) of such Code is amended by adding at the end the following new subparagraph:
“(E) Adjustment for inflation.--In the case of fuel used in a calendar year after 2015, the 7.4 cents amount in subparagraph (A) shall be increased by an amount equal to--
“(i) such cents amount, multiplied by
“(ii) the cost-of-living adjustment determined under section 1(f)(3) for such calendar year by substituting ‘calendar year 2014' for ‘calendar year 1992' in subparagraph (B) thereof.”.
(e) Effective Date.--The amendments made by this section shall apply to diesel fuel, kerosene, and diesel-water fuel emulsions removed, entered, or sold on or after the first day of the first calendar quarter beginning not less than 60 days after the date of the enactment of this Act.
SEC. 62003. ALLOCATION IN ACCOUNTS IN HIGHWAY TRUST FUND.
Section 9503(e) of the Internal Revenue Code of 1986 is amended by adding at the end the following new paragraph:
“(6) Adjustment for inflation.--
“(A) In general.--In the case of any calendar year beginning after 2015, the amount in subparagraph (A) of paragraph (2) shall be increased by an amount equal to--
“(i) such amount, multiplied by
“(ii) the cost-of-living adjustment determined under section 1(f)(3) for such calendar year by substituting ‘calendar year 2014' for ‘calendar year 1992' in subparagraph (B) thereof.
“(B) Rounding.--Any increase under subparagraph (A) shall be rounded to the nearest 0.1 cents.”.
SEC. 62004. FLOOR STOCKS TAXES.
(a) Imposition of Tax.--In the case of any taxable fuel which is held on the floor stocks tax date by any person, there is hereby imposed a floor stocks tax equal to the excess of the tax which would be imposed on such fuel under section 4041 or 4081 of the Internal Revenue Code of 1986 had the taxable event occurred on the floor stocks tax date over the tax paid under any such section on such fuel.
(b) Liability for Tax and Method of Payment.--
(1) Liability for tax.--A person holding a fuel on the floor stocks tax date to which the tax imposed by subsection (a) applies shall be liable for such tax.
(2) Method of payment.--The tax imposed by subsection (a) shall be paid in such manner as the Secretary shall prescribe.
(3) Time of payment.--The tax imposed by subsection (a) shall be paid on or before the date which is 6 months after the floor stocks tax date.
(c) Definitions.--For purposes of this section--
(1) Held by a person.--A fuel shall be considered as held by a person if title thereto has passed to such person (whether or not delivery to the person has been made).
(2) Taxable fuel.--The term “taxable fuel” means--
(A) gasoline (other than aviation gasoline), diesel fuel, kerosene (other than aviation-grade kerosene), and diesel-water fuel emulsions;
(B) fuel taxed under section 4041(a)(2) of the Internal Revenue Code of 1986 (including methanol and ethanol to which section 4041(m) of such Code applies); and
(C) compressed natural gas.
(3) Floor stocks date.--The term “floor stocks tax date” means January 1 of any calendar year beginning after the date of the enactment of this Act on which a rate of tax under section 4041 or 4081 of such Code increases pursuant to an amendment made by section 62001 or 62002.
(4) Secretary.--The term “Secretary” means the Secretary of the Treasury.
(d) Exception for Exempt Uses.--The tax imposed by subsection (a) shall not apply to taxable fuel held by any person exclusively for any use to the extent a credit or refund of the tax imposed by a section of such Code is allowable for such use.
(e) Exception for Fuel Held in Vehicle Tank.--No tax shall be imposed by subsection (a) on taxable fuel held in the tank of a motor vehicle or motorboat.
(f) Exception for Certain Amounts of Fuel.--
(1) In general.--No tax shall be imposed by subsection (a) on any fuel held on the floor stocks tax date by any person if the aggregate amount of fuel held by such person on such date does not exceed 2,000 gallons. The preceding sentence shall apply only if such person submits to the Secretary (at the time and in the manner required by the Secretary) such information as the Secretary shall require for purposes of this paragraph.
(2) Exempt fuel.--For purposes of paragraph (1), there shall not be taken into account fuel held by any person which is exempt from the tax imposed by subsection (a) by reason of subsection (d) or (e).
(3) Controlled groups.--For purposes of this section--
(A) Corporations.--
(i) In general.--All persons treated as a controlled group shall be treated as 1 person.
(ii) Controlled group.--The term “controlled group” has the meaning given to such term by subsection (a) of section 1563 of such Code; except that for such purposes the phrase “more than 50 percent” shall be substituted for the phrase “at least 80 percent” each place it appears in such subsection.
(B) Nonincorporated persons under common control.--Under regulations prescribed by the Secretary, principles similar to the principles of clause (i) shall apply to a group of persons under common control where one or more of such persons is not a corporation.
(g) Other Laws Applicable.--All provisions of law, including penalties, applicable with respect to the taxes imposed by chapter 31 or 32 of such Code shall, insofar as applicable and not inconsistent with the provisions of this section, apply with respect to the floor stock taxes imposed by subsection (a) to the same extent as if such taxes were imposed by such chapter.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
July 26, 2015
View full timeline
Senate amendment submitted
July 26, 2015
Senate amendment submitted
July 26, 2015