S.Amdt. 2521
What it does: Adds SEC. _____. EXTENSION AND SIMPLIFICATION OF RESEARCH CREDIT wherever appropriate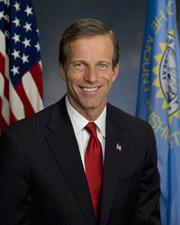 Sen. John Thune (R-SD)
What it changes
1 change to H.R. 22
Adds SEC. _____. EXTENSION AND SIMPLIFICATION OF RESEARCH CREDIT wherever appropriate
Adds a sectionInserted: SEC. _____. EXTENSION AND SIMPLIFICATION OF RESEARCH CREDIT.
Inserted: (a) In General.--Subsection (a) of section 41 of the Internal Revenue Code of 1986 is amended to read as follows:
Inserted: "(a) In General.--For purposes of section 38, the research credit determined under this section for the taxable year shall be an amount equal to the sum of--
Inserted: "(1) 20 percent of so much of the qualified research expenses for the taxable year as exceeds 50 percent of the average qualified research expenses for the 3 taxable years preceding the taxable year for which the credit is being determined,
Inserted: "(2) 20 percent of so much of the basic research payments for the taxable year as exceeds 50 percent of the average basic research payments for the 3 taxable years preceding the taxable year for which the credit is being determined, plus
Inserted: "(3) 20 percent of the amounts paid or incurred by the taxpayer in carrying on any trade or business of the taxpayer during the taxable year (including as contributions) to an energy research consortium for energy research.".
Inserted: (b) Special Rules and Termination of Base Amount Calculation.--
Inserted: (1) In general.--Subsection (c) of section 41 of the Internal Revenue Code of 1986 is amended to read as follows:
Inserted: "(c) Special Rules.--
Inserted: "(1) Special rule in case of no qualified research expenses in any of 3 preceding taxable years.--In the case of a taxpayer that has no qualified research expenses in any one of the 3 taxable years preceding the taxable year for which the credit is being determined--
Inserted: "(A) the amount of the credit under this section for such taxable year relating to qualified research expenses shall be determined under this paragraph and not under subsection (a)(1), and
Inserted: "(B) such credit shall be equal to 10 percent of the qualified research expenses for the taxable year.
Show 132 more inserted paragraphsShow less
Inserted: "(2) Special rule in case of no basic research payments in any of 3 preceding taxable years.--In the case of a taxpayer that has no basic research payments in any one of the 3 taxable years preceding the taxable year for which the credit is being determined--
Inserted: "(A) the credit under this section for such taxable year relating to basic research payments shall be determined under this paragraph and not under subsection (a)(2), and
Inserted: "(B) such credit shall be equal to 10 percent of the basic research payments for the taxable year.
Inserted: "(3) Consistent treatment of expenses.--
Inserted: "(A) In general.--Notwithstanding whether the period for filing a claim for credit or refund has expired for any taxable year taken into account in determining the average qualified research expenses or average basic research payments for purposes of subsection (a), the qualified research expenses and basic research payments taken into account in determining such averages shall be determined on a basis consistent with the determination of qualified research expenses and basic research payments, respectively, for the credit year.
Inserted: "(B) Prevention of distortions.--The Secretary may prescribe regulations to prevent distortions in calculating a taxpayer's qualified research expenses or basic research payments caused by a change in accounting methods used by such taxpayer between the current year and a year taken into account in determining the average qualified research expenses or average basic research payments for purposes of subsection (a).".
Inserted: (2) Simplification of basic research payments calculation.--Subsection (e) of section 41 of such Code is amended--
Inserted: (A) by striking all that precedes paragraph (6) and inserting the following:
Inserted: "(e) Basic Research Payments.--For purposes of this section--
Inserted: "(1) In general.--The term 'basic research payment' means, with respect to any taxable year, any amount paid in cash during such taxable year by a corporation to any qualified organization for basic research but only if--
Inserted: "(A) such payment is pursuant to a written agreement between such corporation and such qualified organization, and
Inserted: "(B) such basic research is to be performed by such qualified organization.
Inserted: "(2) Exception to requirement that research be performed by the organization.--In the case of a qualified organization described in subparagraph (C) or (D) of paragraph (3), subparagraph (B) of paragraph (1) shall not apply.",
Inserted: (B) by redesignating paragraphs (6) and (7) as paragraphs (3) and (4), respectively, and
Inserted: (C) in paragraph (4) (as so redesignated), by striking subparagraphs (B) and (C) and by redesignating subparagraphs (D) and (E) as subparagraphs (B) and (C), respectively.
Inserted: (3) Inclusion of qualified research expenses of an acquired person.--
Inserted: (A) Partial inclusion of pre-acquisition expenditures.--Subparagraph (A) of section 41(f)(3) of such Code is amended to read as follows:
Inserted: "(A) Acquisitions.--
Inserted: "(i) In general.--If a person acquires the major portion of a trade or business of another person (hereinafter in this paragraph referred to as the 'predecessor') or the major portion of a separate unit of a trade or business of a predecessor, then the amount of qualified research expenses or basic research payments paid or incurred by the acquiring person during the 3 taxable years preceding the taxable year in which the credit under this section is determined shall be increased by--
Inserted: "(I) for purposes of applying this section for the taxable year in which such acquisition is made, the amount determined under clause (ii), and
Inserted: "(II) for purposes of applying this section for any taxable year after the taxable year in which such acquisition is made, so much of the qualified research expenses or basic research payments paid or incurred by the predecessor with respect to the acquired trade or business during the portion of the measurement period that is part of the 3-taxable-year period preceding the taxable year for which the credit is determined as is attributable to the portion of such trade or business or separate unit acquired by such person.
Inserted: "(ii) Amount determined.--The amount determined under this clause is the amount equal to the product of--
Inserted: "(I) so much of the qualified research expenses or basic research payments paid or incurred by the predecessor with respect to the acquired trade or business during the 3 taxable years before the taxable year in which the acquisition is made as is attributable to the portion of such trade or business or separate unit acquired by the acquiring person, and
Inserted: "(II) the number of months in the period beginning on the date of the acquisition and ending on the last day of the taxable year in which the acquisition is made, divided by 12.
Inserted: "(iii) Special rules for coordinating taxable years.--In the case of an acquiring person and a predecessor whose taxable years do not begin on the same date--
Inserted: "(I) each reference to a taxable year in clauses (i) and (ii) shall refer to the appropriate taxable year of the acquiring person,
Inserted: "(II) the qualified research expenses or basic research payments paid or incurred by the predecessor during each taxable year of the predecessor any portion of which is part of the measurement period shall be allocated equally among the months of such taxable year, and
Inserted: "(III) the amount of such qualified research expenses or basic research payments taken into account under clauses (i) and (ii) with respect to a taxable year of the acquiring person shall be equal to the total of the expenses attributable under subclause (II) to the months occurring during such taxable year.
Inserted: "(iv) Measurement period.--For purposes of this subparagraph, the term 'measurement period' means the taxable year of the acquiring person in which the acquisition is made and the 3 taxable years of the acquiring person preceding such taxable year.
Inserted: "(v) Separation of expenditures.--This subparagraph shall be applied separately with respect to qualified research expenses and basic research payments.".
Inserted: (B) Expenses of a predecessor.--Subparagraph (B) of section 41(f)(3) of such Code is amended to read as follows:
Inserted: "(B) Dispositions.--If the predecessor furnished to the acquiring person such information as is necessary for the application of subparagraph (A), then, for purposes of applying this section for any taxable year ending after such disposition, the amount of qualified research expenses or basic research payments paid or incurred by the predecessor during the 3 taxable years preceding such taxable year shall be reduced--
Inserted: "(i) in the case of the taxable year in which such disposition is made, by an amount equal to the product of--
Inserted: "(I) the amount of qualified research expenses or basic research payments paid or incurred during such 3 taxable years with respect to the acquired business, and
Inserted: "(II) the number of days in the period beginning on the date of acquisition (as determined for purposes of subparagraph (A)(ii)(II)) and ending on the last day of the taxable year of the predecessor in which the disposition is made, divided by the number of days in the taxable year of the predecessor, and
Inserted: "(ii) in the case of any taxable year ending after the taxable year in which such disposition is made, the amount described in clause (i)(I).
Inserted: This subparagraph shall be applied separately with respect to qualified research expenses and basic research payments.".
Inserted: (C) Conforming amendments.--
Inserted: (i) Paragraph (3) of section 41(f) of such Code is amended by striking subparagraph (C).
Inserted: (ii) Paragraph (4) of section 41(f) of such Code is amended by striking "gross receipts" and inserting "basic research payments".
Inserted: (c) Permanent Extension.--
Inserted: (1) Section 41 of the Internal Revenue Code of 1986 is amended by striking subsection (h).
Inserted: (2) Paragraph (1) of section 45C(b) of such Code is amended by striking subparagraph (D).
Inserted: (d) Cross-references.--
Inserted: (1) Paragraph (2) of section 45C(c) of the Internal Revenue Code of 1986 is amended--
Inserted: (A) by striking "base period research expenses" and inserting "average qualified research expenses", and
Inserted: (B) by striking "base period research expenses" in the heading and inserting "average qualified research expenses".
Inserted: (2) Subsection (c) of section 280C of such Code is amended--
Inserted: (A) by striking "basic research expenses (as defined in section 41(e)(2))" in paragraph (1) and inserting "basic research payments (as defined in section 41(e)(1))", and
Inserted: (B) by striking "basic research expenses" in paragraph (2)(B) and inserting "basic research payments".
Inserted: (e) Credit Allowed Against Alternative Minimum Tax in Case of Eligible Small Business.--Section 38(c)(4)(B) of the Internal Revenue Code of 1986 is amended by redesignating clauses (ii) through (ix) as clauses (iii) through (x), respectively, and by inserting after clause (i) the following new clause:
Inserted: "(ii) the credit determined under section 41 for the taxable year with respect to an eligible small business (as defined in paragraph (5)(C), after application of rules similar to the rules of paragraph (5)(D)),".
Inserted: (f) Technical Corrections.--Section 409 of the Internal Revenue Code of 1986 is amended--
Inserted: (1) by inserting ", as in effect before the enactment of the Tax Reform Act of 1986)" after "section 41(c)(1)(B)" in subsection (b)(1)(A),
Inserted: (2) by inserting ", as in effect before the enactment of the Tax Reform Act of 1986" after "relating to the employee stock ownership credit" in subsection (b)(4),
Inserted: (3) by inserting "(as in effect before the enactment of the Tax Reform Act of 1986)" after "section 41(c)(1)(B)" in subsection (i)(1)(A), and
Inserted: (4) by striking ", or subparagraph (A) or (B) of section 48(n)(1)" in subsection (m) and inserting "(as in effect before the enactment of the Tax Reform Act of 1986)".
Inserted: (g) Effective Date.--
Inserted: (1) In general.--Except as provided in paragraphs (2) and (3), the amendments made by this section shall apply to taxable years beginning after December 31, 2014.
Inserted: (2) Permanent extension.--The amendments made by subsection (c) shall apply to amounts paid or incurred after December 31, 2014.
Inserted: (3) Technical corrections.--The amendments made by subsection (f) shall take effect on the date of the enactment of this Act.
Inserted: SEC. _____. RULE ALLOWING CERTAIN TAX-FREE DISTRIBUTIONS FROM INDIVIDUAL RETIREMENT ACCOUNTS FOR CHARITABLE PURPOSES MADE PERMANENT.
Inserted: (a) In General.--Section 408(d)(8) of the Internal Revenue Code of 1986 is amended by striking subparagraph (F).
Inserted: (b) Effective Date.--The amendment made by this section shall apply to distributions made in taxable years beginning after December 31, 2014.
Inserted: SEC. _____. EXTENSION AND EXPANSION OF CHARITABLE DEDUCTION FOR CONTRIBUTIONS OF FOOD INVENTORY.
Inserted: (a) Permanent Extension.--Section 170(e)(3)(C) of the Internal Revenue Code of 1986 is amended by striking clause (iv).
Inserted: (b) Increase in Limitation.--Section 170(e)(3)(C) of the Internal Revenue Code of 1986, as amended by subsection (a), is amended by striking clause (ii), by redesignating clause (iii) as clause (iv), and by inserting after clause (i) the following new clauses:
Inserted: "(ii) Limitation.--The aggregate amount of such contributions for any taxable year which may be taken into account under this section shall not exceed--
Inserted: "(I) in the case of any taxpayer other than a C corporation, 15 percent of the taxpayer's aggregate net income for such taxable year from all trades or businesses from which such contributions were made for such year, computed without regard to this section, and
Inserted: "(II) in the case of a C corporation, 15 percent of taxable income (as defined in subsection (b)(2)(D)).
Inserted: "(iii) Rules related to limitation.--
Inserted: "(I) Carryover.--If such aggregate amount exceeds the limitation imposed under clause (ii), such excess shall be treated (in a manner consistent with the rules of subsection (d)) as a charitable contribution described in clause (i) in each of the 5 succeeding taxable years in order of time.
Inserted: "(II) Coordination with overall corporate limitation.--In the case of any charitable contribution allowable under clause (ii)(II), subsection (b)(2)(A) shall not apply to such contribution, but the limitation imposed by such subsection shall be reduced (but not below zero) by the aggregate amount of such contributions. For purposes of subsection (b)(2)(B), such contributions shall be treated as allowable under subsection (b)(2)(A).".
Inserted: (c) Determination of Basis for Certain Taxpayers.--Section 170(e)(3)(C) of the Internal Revenue Code of 1986, as amended by subsections (a) and (b), is amended by adding at the end the following new clause:
Inserted: "(v) Determination of basis for certain taxpayers.--If a taxpayer--
Inserted: "(I) does not account for inventories under section 471, and
Inserted: "(II) is not required to capitalize indirect costs under section 263A, the taxpayer may elect, solely for purposes of subparagraph (B), to treat the basis of any apparently wholesome food as being equal to 25 percent of the fair market value of such food.".
Inserted: (d) Determination of Fair Market Value.--Section 170(e)(3)(C) of the Internal Revenue Code of 1986, as amended by subsections (a), (b), and (c), is amended by adding at the end the following new clause:
Inserted: "(vi) Determination of fair market value.--In the case of any such contribution of apparently wholesome food which cannot or will not be sold solely by reason of internal standards of the taxpayer, lack of market, or similar circumstances, or by reason of being produced by the taxpayer exclusively for the purposes of transferring the food to an organization described in subparagraph (A), the fair market value of such contribution shall be determined--
Inserted: "(I) without regard to such internal standards, such lack of market, such circumstances, or such exclusive purpose, and
Inserted: "(II) by taking into account the price at which the same or substantially the same food items (as to both type and quality) are sold by the taxpayer at the time of the contribution (or, if not so sold at such time, in the recent past).".
Inserted: (e) Effective Date.--
Inserted: (1) In general.--Except as otherwise provided in this subsection, the amendments made by this section shall apply to contributions made after the date of the enactment of this Act, in taxable years ending after such date.
Inserted: (2) Limitation; applicability to c corporations.--The amendments made by subsection (b) shall apply to contributions made in taxable years ending after the date of the enactment of this Act.
Inserted: SEC. _____. SPECIAL RULE FOR QUALIFIED CONSERVATION CONTRIBUTIONS MADE PERMANENT.
Inserted: (a) In General.--
Inserted: (1) Individuals.--Subparagraph (E) of section 170(b)(1) of the Internal Revenue Code of 1986 (relating to contributions of qualified conservation contributions) is amended by striking clause (vi).
Inserted: (2) Corporations.--Subparagraph (B) of section 170(b)(2) of such Code (relating to qualified conservation contributions) is amended by striking clause (iii).
Inserted: (b) Contributions of Capital Gain Real Property Made for Conservation Purposes by Native Corporations.--
Inserted: (1) In general.--Section 170(b)(2) of the Internal Revenue Code of 1986 is amended by redesignating subparagraph (C) as subparagraph (D), and by inserting after subparagraph (B) the following new subparagraph:
Inserted: "(C) Qualified conservation contributions by certain native corporations.--
Inserted: "(i) In general.--Any qualified conservation contribution (as defined in subsection (h)(1)) which--
Inserted: "(I) is made by a Native Corporation, and
Inserted: "(II) is a contribution of property which was land conveyed under the Alaska Native Claims Settlement Act, shall be allowed to the extent that the aggregate amount of such contributions does not exceed the excess of the taxpayer's taxable income over the amount of charitable contributions allowable under subparagraph (A).
Inserted: "(ii) Carryover.--If the aggregate amount of contributions described in clause (i) exceeds the limitation of clause (i), such excess shall be treated (in a manner consistent with the rules of subsection (d)(2)) as a charitable contribution to which clause (i) applies in each of the 15 succeeding taxable years in order of time.
Inserted: "(iii) Native corporation.--For purposes of this subparagraph, the term 'Native Corporation' has the meaning given such term by section 3(m) of the Alaska Native Claims Settlement Act.".
Inserted: (2) Conforming amendments.--
Inserted: (A) Section 170(b)(2)(A) of such Code is amended by striking "subparagraph (B) applies" and inserting "subparagraph (B) or (C) applies".
Inserted: (B) Section 170(b)(2)(B)(ii) of such Code is amended by striking "15 succeeding years" and inserting "15 succeeding taxable years".
Inserted: (3) Valid existing rights preserved.--Nothing in this subsection (or any amendment made by this subsection) shall be construed to modify the existing property rights validly conveyed to Native Corporations (within the meaning of section 3(m) of the Alaska Native Claims Settlement Act) under such Act.
Inserted: (c) Effective Date.--The amendments made by this section shall apply to contributions made in taxable years beginning after December 31, 2014.
Inserted: SEC. _____. EXPENSING CERTAIN DEPRECIABLE BUSINESS ASSETS FOR SMALL BUSINESS.
Inserted: (a) In General.--
Inserted: (1) Dollar limitation.--Section 179(b)(1) of the Internal Revenue Code of 1986 is amended by striking "shall not exceed--" and all that follows and inserting "shall not exceed $500,000.".
Inserted: (2) Reduction in limitation.--Section 179(b)(2) of such Code is amended by striking "exceeds--" and all that follows and inserting "exceeds $2,000,000.".
Inserted: (b) Computer Software.--Section 179(d)(1)(A)(ii) of the Internal Revenue Code of 1986 is amended by striking ", to which section 167 applies, and which is placed in service in a taxable year beginning after 2002 and before 2015" and inserting "and to which section 167 applies".
Inserted: (c) Election.--Section 179(c)(2) of the Internal Revenue Code of 1986 is amended--
Inserted: (1) by striking "may not be revoked" and all that follows through "and before 2015"; and
Inserted: (2) by striking "irrevocable" in the heading thereof.
Inserted: (d) Air Conditioning and Heating Units.--Section 179(d)(1) of the Internal Revenue Code of 1986 is amended by striking "and shall not include air conditioning or heating units".
Inserted: (e) Qualified Real Property.--Section 179(f) of the Internal Revenue Code of 1986 is amended--
Inserted: (1) by striking "beginning after 2009 and before 2015" in paragraph (1); and
Inserted: (2) by striking paragraphs (3) and (4).
Inserted: (f) Inflation Adjustment.--Section 179(b) of the Internal Revenue Code of 1986 is amended by adding at the end the following new paragraph:
Inserted: "(6) Inflation adjustment.--
Inserted: "(A) In general.--In the case of any taxable year beginning after 2015, the dollar amounts in paragraphs (1) and (2) shall each be increased by an amount equal to--
Inserted: "(i) such dollar amount, multiplied by
Inserted: "(ii) the cost-of-living adjustment determined under section 1(f)(3) for the calendar year in which the taxable year begins, determined by substituting 'calendar year 2014' for 'calendar year 1992' in subparagraph (B) thereof.
Inserted: "(B) Rounding.--The amount of any increase under subparagraph (A) shall be rounded to the nearest multiple of $10,000.".
Inserted: (g) Effective Date.--The amendments made by this section shall apply to taxable years beginning after December 31, 2014.
Inserted: SEC. _____. REDUCED RECOGNITION PERIOD FOR BUILT-IN GAINS OF S CORPORATIONS MADE PERMANENT.
Inserted: (a) In General.--Paragraph (7) of section 1374(d) of the Internal Revenue Code of 1986 is amended to read as follows:
Inserted: "(7) Recognition period.--
Inserted: "(A) In general.--The term 'recognition period' means the 5-year period beginning with the first day of the first taxable year for which the corporation was an S corporation. For purposes of applying this section to any amount includible in income by reason of distributions to shareholders pursuant to section 593(e), the preceding sentence shall be applied without regard to the phrase '5-year'.
Inserted: "(B) Installment sales.--If an S corporation sells an asset and reports the income from the sale using the installment method under section 453, the treatment of all payments received shall be governed by the provisions of this paragraph applicable to the taxable year in which such sale was made.".
Inserted: (b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2014.
Inserted: SEC. _____. PERMANENT RULE REGARDING BASIS ADJUSTMENT TO STOCK OF S CORPORATIONS MAKING CHARITABLE CONTRIBUTIONS OF PROPERTY.
Inserted: (a) In General.--Section 1367(a)(2) of the Internal Revenue Code of 1986 is amended by striking the last sentence.
Inserted: (b) Effective Date.--The amendment made by this section shall apply to contributions made in taxable years beginning after December 31, 2014.
Inserted: SEC. _____. PERMANENT EXTENSION OF DEDUCTION OF STATE AND LOCAL GENERAL SALES TAXES.
Inserted: (a) In General.--Section 164(b)(5) of the Internal Revenue Code of 1986 is amended by striking subparagraph (I).
Inserted: (b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2014.
The amendment doesn't say where this goes; the clerk decides.
Original wording
At the appropriate place, insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 2521. Mr. THUNE submitted an amendment intended to be proposed by him to the bill H.R. 22, to amend the Internal Revenue Code of 1986 to exempt employees with health coverage under TRICARE or the Veterans Administration from being taken into account for purposes of determining the employers to which the employer mandate applies under the Patient Protection and Affordable Care Act; which was ordered to lie on the table; as follows:
At the appropriate place, insert the following:
SEC. _____. EXTENSION AND SIMPLIFICATION OF RESEARCH CREDIT.
(a) In General.--Subsection (a) of section 41 of the Internal Revenue Code of 1986 is amended to read as follows:
“(a) In General.--For purposes of section 38, the research credit determined under this section for the taxable year shall be an amount equal to the sum of--
“(1) 20 percent of so much of the qualified research expenses for the taxable year as exceeds 50 percent of the average qualified research expenses for the 3 taxable years preceding the taxable year for which the credit is being determined,
“(2) 20 percent of so much of the basic research payments for the taxable year as exceeds 50 percent of the average basic research payments for the 3 taxable years preceding the taxable year for which the credit is being determined, plus
“(3) 20 percent of the amounts paid or incurred by the taxpayer in carrying on any trade or business of the taxpayer during the taxable year (including as contributions) to an energy research consortium for energy research.”.
(b) Special Rules and Termination of Base Amount Calculation.--
(1) In general.--Subsection (c) of section 41 of the Internal Revenue Code of 1986 is amended to read as follows:
“(c) Special Rules.--
“(1) Special rule in case of no qualified research expenses in any of 3 preceding taxable years.--In the case of a taxpayer that has no qualified research expenses in any one of the 3 taxable years preceding the taxable year for which the credit is being determined--
“(A) the amount of the credit under this section for such taxable year relating to qualified research expenses shall be determined under this paragraph and not under subsection (a)(1), and
“(B) such credit shall be equal to 10 percent of the qualified research expenses for the taxable year.
“(2) Special rule in case of no basic research payments in any of 3 preceding taxable years.--In the case of a taxpayer that has no basic research payments in any one of the 3 taxable years preceding the taxable year for which the credit is being determined--
“(A) the credit under this section for such taxable year relating to basic research payments shall be determined under this paragraph and not under subsection (a)(2), and
“(B) such credit shall be equal to 10 percent of the basic research payments for the taxable year.
“(3) Consistent treatment of expenses.--
“(A) In general.--Notwithstanding whether the period for filing a claim for credit or refund has expired for any taxable year taken into account in determining the average qualified research expenses or average basic research payments for purposes of subsection (a), the qualified research expenses and basic research payments taken into account in determining such averages shall be determined on a basis consistent with the determination of qualified research expenses and basic research payments, respectively, for the credit year.
“(B) Prevention of distortions.--The Secretary may prescribe regulations to prevent distortions in calculating a taxpayer's qualified research expenses or basic research payments caused by a change in accounting methods used by such taxpayer between the current year and a year taken into account in determining the average qualified research expenses or average basic research payments for purposes of subsection (a).”.
(2) Simplification of basic research payments calculation.--Subsection (e) of section 41 of such Code is amended--
(A) by striking all that precedes paragraph (6) and inserting the following:
“(e) Basic Research Payments.--For purposes of this section--
“(1) In general.--The term ‘basic research payment' means, with respect to any taxable year, any amount paid in cash during such taxable year by a corporation to any qualified organization for basic research but only if--
“(A) such payment is pursuant to a written agreement between such corporation and such qualified organization, and
“(B) such basic research is to be performed by such qualified organization.
“(2) Exception to requirement that research be performed by the organization.--In the case of a qualified organization described in subparagraph (C) or (D) of paragraph (3), subparagraph (B) of paragraph (1) shall not apply.”,
(B) by redesignating paragraphs (6) and (7) as paragraphs (3) and (4), respectively, and
(C) in paragraph (4) (as so redesignated), by striking subparagraphs (B) and (C) and by redesignating subparagraphs (D) and (E) as subparagraphs (B) and (C), respectively.
(3) Inclusion of qualified research expenses of an acquired person.--
(A) Partial inclusion of pre-acquisition expenditures.--Subparagraph (A) of section 41(f)(3) of such Code is amended to read as follows:
“(A) Acquisitions.--
“(i) In general.--If a person acquires the major portion of a trade or business of another person (hereinafter in this paragraph referred to as the ‘predecessor') or the major portion of a separate unit of a trade or business of a predecessor, then the amount of qualified research expenses or basic research payments paid or incurred by the acquiring person during the 3 taxable years preceding the taxable year in which the credit under this section is determined shall be increased by--
“(I) for purposes of applying this section for the taxable year in which such acquisition is made, the amount determined under clause (ii), and
“(II) for purposes of applying this section for any taxable year after the taxable year in which such acquisition is made, so much of the qualified research expenses or basic research payments paid or incurred by the predecessor with respect to the acquired trade or business during the portion of the measurement period that is part of the 3-taxable-year period preceding the taxable year for which the credit is determined as is attributable to the portion of such trade or business or separate unit acquired by such person.
“(ii) Amount determined.--The amount determined under this clause is the amount equal to the product of--
“(I) so much of the qualified research expenses or basic research payments paid or incurred by the predecessor with respect to the acquired trade or business during the 3 taxable years before the taxable year in which the acquisition is made as is attributable to the portion of such trade or business or separate unit acquired by the acquiring person, and
“(II) the number of months in the period beginning on the date of the acquisition and ending on the last day of the taxable year in which the acquisition is made, divided by 12.
“(iii) Special rules for coordinating taxable years.--In the case of an acquiring person and a predecessor whose taxable years do not begin on the same date--
“(I) each reference to a taxable year in clauses (i) and (ii) shall refer to the appropriate taxable year of the acquiring person,
“(II) the qualified research expenses or basic research payments paid or incurred by the predecessor during each taxable year of the predecessor any portion of which is part of the measurement period shall be allocated equally among the months of such taxable year, and
“(III) the amount of such qualified research expenses or basic research payments taken into account under clauses (i) and (ii) with respect to a taxable year of the acquiring person shall be equal to the total of the expenses attributable under subclause (II) to the months occurring during such taxable year.
“(iv) Measurement period.--For purposes of this subparagraph, the term ‘measurement period' means the taxable year of the acquiring person in which the acquisition is made and the 3 taxable years of the acquiring person preceding such taxable year.
“(v) Separation of expenditures.--This subparagraph shall be applied separately with respect to qualified research expenses and basic research payments.”.
(B) Expenses of a predecessor.--Subparagraph (B) of section 41(f)(3) of such Code is amended to read as follows:
“(B) Dispositions.--If the predecessor furnished to the acquiring person such information as is necessary for the application of subparagraph (A), then, for purposes of applying this section for any taxable year ending after such disposition, the amount of qualified research expenses or basic research payments paid or incurred by the predecessor during the 3 taxable years preceding such taxable year shall be reduced--
“(i) in the case of the taxable year in which such disposition is made, by an amount equal to the product of--
“(I) the amount of qualified research expenses or basic research payments paid or incurred during such 3 taxable years with respect to the acquired business, and
“(II) the number of days in the period beginning on the date of acquisition (as determined for purposes of subparagraph (A)(ii)(II)) and ending on the last day of the taxable year of the predecessor in which the disposition is made, divided by the number of days in the taxable year of the predecessor, and
“(ii) in the case of any taxable year ending after the taxable year in which such disposition is made, the amount described in clause (i)(I).
This subparagraph shall be applied separately with respect to qualified research expenses and basic research payments.”.
(C) Conforming amendments.--
(i) Paragraph (3) of section 41(f) of such Code is amended by striking subparagraph (C).
(ii) Paragraph (4) of section 41(f) of such Code is amended by striking “gross receipts” and inserting “basic research payments”.
(c) Permanent Extension.--
(1) Section 41 of the Internal Revenue Code of 1986 is amended by striking subsection (h).
(2) Paragraph (1) of section 45C(b) of such Code is amended by striking subparagraph (D).
(d) Cross-references.--
(1) Paragraph (2) of section 45C(c) of the Internal Revenue Code of 1986 is amended--
(A) by striking “base period research expenses” and inserting “average qualified research expenses”, and
(B) by striking “base period research expenses” in the heading and inserting “average qualified research expenses”.
(2) Subsection (c) of section 280C of such Code is amended--
(A) by striking “basic research expenses (as defined in section 41(e)(2))” in paragraph (1) and inserting “basic research payments (as defined in section 41(e)(1))”, and
(B) by striking “basic research expenses” in paragraph (2)(B) and inserting “basic research payments”.
(e) Credit Allowed Against Alternative Minimum Tax in Case of Eligible Small Business.--Section 38(c)(4)(B) of the Internal Revenue Code of 1986 is amended by redesignating clauses (ii) through (ix) as clauses (iii) through (x), respectively, and by inserting after clause (i) the following new clause:
“(ii) the credit determined under section 41 for the taxable year with respect to an eligible small business (as defined in paragraph (5)(C), after application of rules similar to the rules of paragraph (5)(D)),”.
(f) Technical Corrections.--Section 409 of the Internal Revenue Code of 1986 is amended--
(1) by inserting “, as in effect before the enactment of the Tax Reform Act of 1986)” after “section 41(c)(1)(B)” in subsection (b)(1)(A),
(2) by inserting “, as in effect before the enactment of the Tax Reform Act of 1986” after “relating to the employee stock ownership credit” in subsection (b)(4),
(3) by inserting “(as in effect before the enactment of the Tax Reform Act of 1986)” after “section 41(c)(1)(B)” in subsection (i)(1)(A), and
(4) by striking “, or subparagraph (A) or (B) of section 48(n)(1)” in subsection (m) and inserting “(as in effect before the enactment of the Tax Reform Act of 1986)”.
(g) Effective Date.--
(1) In general.--Except as provided in paragraphs (2) and (3), the amendments made by this section shall apply to taxable years beginning after December 31, 2014.
(2) Permanent extension.--The amendments made by subsection (c) shall apply to amounts paid or incurred after December 31, 2014.
(3) Technical corrections.--The amendments made by subsection (f) shall take effect on the date of the enactment of this Act.
SEC. _____. RULE ALLOWING CERTAIN TAX-FREE DISTRIBUTIONS FROM INDIVIDUAL RETIREMENT ACCOUNTS FOR CHARITABLE PURPOSES MADE PERMANENT.
(a) In General.--Section 408(d)(8) of the Internal Revenue Code of 1986 is amended by striking subparagraph (F).
(b) Effective Date.--The amendment made by this section shall apply to distributions made in taxable years beginning after December 31, 2014.
SEC. _____. EXTENSION AND EXPANSION OF CHARITABLE DEDUCTION FOR CONTRIBUTIONS OF FOOD INVENTORY.
(a) Permanent Extension.--Section 170(e)(3)(C) of the Internal Revenue Code of 1986 is amended by striking clause (iv).
(b) Increase in Limitation.--Section 170(e)(3)(C) of the Internal Revenue Code of 1986, as amended by subsection (a), is amended by striking clause (ii), by redesignating clause (iii) as clause (iv), and by inserting after clause (i) the following new clauses:
“(ii) Limitation.--The aggregate amount of such contributions for any taxable year which may be taken into account under this section shall not exceed--
“(I) in the case of any taxpayer other than a C corporation, 15 percent of the taxpayer's aggregate net income for such taxable year from all trades or businesses from which such contributions were made for such year, computed without regard to this section, and
“(II) in the case of a C corporation, 15 percent of taxable income (as defined in subsection (b)(2)(D)).
“(iii) Rules related to limitation.--
“(I) Carryover.--If such aggregate amount exceeds the limitation imposed under clause (ii), such excess shall be treated (in a manner consistent with the rules of subsection (d)) as a charitable contribution described in clause (i) in each of the 5 succeeding taxable years in order of time.
“(II) Coordination with overall corporate limitation.--In the case of any charitable contribution allowable under clause (ii)(II), subsection (b)(2)(A) shall not apply to such contribution, but the limitation imposed by such subsection shall be reduced (but not below zero) by the aggregate amount of such contributions. For purposes of subsection (b)(2)(B), such contributions shall be treated as allowable under subsection (b)(2)(A).”.
(c) Determination of Basis for Certain Taxpayers.--Section 170(e)(3)(C) of the Internal Revenue Code of 1986, as amended by subsections (a) and (b), is amended by adding at the end the following new clause:
“(v) Determination of basis for certain taxpayers.--If a taxpayer--
“(I) does not account for inventories under section 471, and
“(II) is not required to capitalize indirect costs under section 263A, the taxpayer may elect, solely for purposes of subparagraph (B), to treat the basis of any apparently wholesome food as being equal to 25 percent of the fair market value of such food.”.
(d) Determination of Fair Market Value.--Section 170(e)(3)(C) of the Internal Revenue Code of 1986, as amended by subsections (a), (b), and (c), is amended by adding at the end the following new clause:
“(vi) Determination of fair market value.--In the case of any such contribution of apparently wholesome food which cannot or will not be sold solely by reason of internal standards of the taxpayer, lack of market, or similar circumstances, or by reason of being produced by the taxpayer exclusively for the purposes of transferring the food to an organization described in subparagraph (A), the fair market value of such contribution shall be determined--
“(I) without regard to such internal standards, such lack of market, such circumstances, or such exclusive purpose, and
“(II) by taking into account the price at which the same or substantially the same food items (as to both type and quality) are sold by the taxpayer at the time of the contribution (or, if not so sold at such time, in the recent past).”.
(e) Effective Date.--
(1) In general.--Except as otherwise provided in this subsection, the amendments made by this section shall apply to contributions made after the date of the enactment of this Act, in taxable years ending after such date.
(2) Limitation; applicability to c corporations.--The amendments made by subsection (b) shall apply to contributions made in taxable years ending after the date of the enactment of this Act.
SEC. _____. SPECIAL RULE FOR QUALIFIED CONSERVATION CONTRIBUTIONS MADE PERMANENT.
(a) In General.--
(1) Individuals.--Subparagraph (E) of section 170(b)(1) of the Internal Revenue Code of 1986 (relating to contributions of qualified conservation contributions) is amended by striking clause (vi).
(2) Corporations.--Subparagraph (B) of section 170(b)(2) of such Code (relating to qualified conservation contributions) is amended by striking clause (iii).
(b) Contributions of Capital Gain Real Property Made for Conservation Purposes by Native Corporations.--
(1) In general.--Section 170(b)(2) of the Internal Revenue Code of 1986 is amended by redesignating subparagraph (C) as subparagraph (D), and by inserting after subparagraph (B) the following new subparagraph:
“(C) Qualified conservation contributions by certain native corporations.--
“(i) In general.--Any qualified conservation contribution (as defined in subsection (h)(1)) which--
“(I) is made by a Native Corporation, and
“(II) is a contribution of property which was land conveyed under the Alaska Native Claims Settlement Act, shall be allowed to the extent that the aggregate amount of such contributions does not exceed the excess of the taxpayer's taxable income over the amount of charitable contributions allowable under subparagraph (A).
“(ii) Carryover.--If the aggregate amount of contributions described in clause (i) exceeds the limitation of clause (i), such excess shall be treated (in a manner consistent with the rules of subsection (d)(2)) as a charitable contribution to which clause (i) applies in each of the 15 succeeding taxable years in order of time.
“(iii) Native corporation.--For purposes of this subparagraph, the term ‘Native Corporation' has the meaning given such term by section 3(m) of the Alaska Native Claims Settlement Act.”.
(2) Conforming amendments.--
(A) Section 170(b)(2)(A) of such Code is amended by striking “subparagraph (B) applies” and inserting “subparagraph (B) or (C) applies”.
(B) Section 170(b)(2)(B)(ii) of such Code is amended by striking “15 succeeding years” and inserting “15 succeeding taxable years”.
(3) Valid existing rights preserved.--Nothing in this subsection (or any amendment made by this subsection) shall be construed to modify the existing property rights validly conveyed to Native Corporations (within the meaning of section 3(m) of the Alaska Native Claims Settlement Act) under such Act.
(c) Effective Date.--The amendments made by this section shall apply to contributions made in taxable years beginning after December 31, 2014.
SEC. _____. EXPENSING CERTAIN DEPRECIABLE BUSINESS ASSETS FOR SMALL BUSINESS.
(a) In General.--
(1) Dollar limitation.--Section 179(b)(1) of the Internal Revenue Code of 1986 is amended by striking “shall not exceed--” and all that follows and inserting “shall not exceed $500,000.”.
(2) Reduction in limitation.--Section 179(b)(2) of such Code is amended by striking “exceeds--” and all that follows and inserting “exceeds $2,000,000.”.
(b) Computer Software.--Section 179(d)(1)(A)(ii) of the Internal Revenue Code of 1986 is amended by striking “, to which section 167 applies, and which is placed in service in a taxable year beginning after 2002 and before 2015” and inserting “and to which section 167 applies”.
(c) Election.--Section 179(c)(2) of the Internal Revenue Code of 1986 is amended--
(1) by striking “may not be revoked” and all that follows through “and before 2015”; and
(2) by striking “irrevocable” in the heading thereof.
(d) Air Conditioning and Heating Units.--Section 179(d)(1) of the Internal Revenue Code of 1986 is amended by striking “and shall not include air conditioning or heating units”.
(e) Qualified Real Property.--Section 179(f) of the Internal Revenue Code of 1986 is amended--
(1) by striking “beginning after 2009 and before 2015” in paragraph (1); and
(2) by striking paragraphs (3) and (4).
(f) Inflation Adjustment.--Section 179(b) of the Internal Revenue Code of 1986 is amended by adding at the end the following new paragraph:
“(6) Inflation adjustment.--
“(A) In general.--In the case of any taxable year beginning after 2015, the dollar amounts in paragraphs (1) and (2) shall each be increased by an amount equal to--
“(i) such dollar amount, multiplied by
“(ii) the cost-of-living adjustment determined under section 1(f)(3) for the calendar year in which the taxable year begins, determined by substituting ‘calendar year 2014' for ‘calendar year 1992' in subparagraph (B) thereof.
“(B) Rounding.--The amount of any increase under subparagraph (A) shall be rounded to the nearest multiple of $10,000.”.
(g) Effective Date.--The amendments made by this section shall apply to taxable years beginning after December 31, 2014.
SEC. _____. REDUCED RECOGNITION PERIOD FOR BUILT-IN GAINS OF S CORPORATIONS MADE PERMANENT.
(a) In General.--Paragraph (7) of section 1374(d) of the Internal Revenue Code of 1986 is amended to read as follows:
“(7) Recognition period.--
“(A) In general.--The term ‘recognition period' means the 5-year period beginning with the first day of the first taxable year for which the corporation was an S corporation. For purposes of applying this section to any amount includible in income by reason of distributions to shareholders pursuant to section 593(e), the preceding sentence shall be applied without regard to the phrase ‘5-year'.
“(B) Installment sales.--If an S corporation sells an asset and reports the income from the sale using the installment method under section 453, the treatment of all payments received shall be governed by the provisions of this paragraph applicable to the taxable year in which such sale was made.”.
(b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2014.
SEC. _____. PERMANENT RULE REGARDING BASIS ADJUSTMENT TO STOCK OF S CORPORATIONS MAKING CHARITABLE CONTRIBUTIONS OF PROPERTY.
(a) In General.--Section 1367(a)(2) of the Internal Revenue Code of 1986 is amended by striking the last sentence.
(b) Effective Date.--The amendment made by this section shall apply to contributions made in taxable years beginning after December 31, 2014.
SEC. _____. PERMANENT EXTENSION OF DEDUCTION OF STATE AND LOCAL GENERAL SALES TAXES.
(a) In General.--Section 164(b)(5) of the Internal Revenue Code of 1986 is amended by striking subparagraph (I).
(b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2014.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
July 26, 2015
View full timeline
Senate amendment submitted
July 26, 2015
Senate amendment submitted
July 26, 2015