S.Amdt. 6190
What it does: Adds SEC. _____. CERTAIN AMOUNTS TREATED AS EARNED INCOME FOR KIDDIE TAX wherever appropriate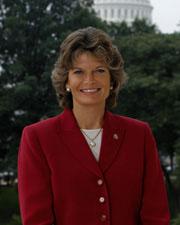 Sen. Lisa Murkowski (R-AK)
What it changes
1 change to S.Amdt. 5499
Adds SEC. _____. CERTAIN AMOUNTS TREATED AS EARNED INCOME FOR KIDDIE TAX wherever appropriate
Adds a sectionInserted: SEC. _____. CERTAIN AMOUNTS TREATED AS EARNED INCOME FOR KIDDIE TAX.
Inserted: (a) In General.--Section 1(g)(4)(C) of the Internal Revenue Code of 1986 is amended to read as follows:
Inserted: "(C) Treatment of certain amounts as earned income.--For purposes of this subsection, each of the following amounts shall be treated as earned income of the child referred to in paragraph (1) to the extent included in the gross income of such child:
Inserted: "(i) Distributions from qualified disability trusts.--Any amount included in the gross income of such child under section 652 or 662 by reason of being a beneficiary of a qualified disability trust (as defined in section 642(b)(2)(C)(ii)).
Inserted: "(ii) Certain indian tribal payments.--Any payment which is included in the gross income of such child and made by an Indian tribal government (as defined in section 139E(c)(1)), or from a trust of which the Indian tribal government is treated as the owner under subpart E of part I of subchapter J, to or for the benefit of such child if--
Inserted: "(I) such child or a family member (within the meaning of section 267(c)(4)) is an enrolled member of the tribe with respect to such Indian tribal government, and
Inserted: "(II) such payment is made by reason of such enrollment.
Inserted: "(iii) Certain payments from native corporations or settlement trusts.--Any payment which is included in the gross income of such child and--
Inserted: "(I) made by a Native corporation (as defined in section 646(h)(2)) to or for the benefit of such child if such child or a family member (within the meaning of section 267(c)(4)) has an equity interest in the Native corporation, or
Inserted: "(II) made by a Settlement Trust (as defined in section 646(h)(4)) to or for the benefit of such child if such child or a family member (within the meaning of section 267(c)(4)) has a beneficial interest in such Settlement Trust.
Inserted: "(iv) Alaska permanent fund dividends.--The amount of any Alaska Permanent Fund dividend which is included in the gross income of such child.".
Inserted: (b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2021.
The amendment doesn't say where this goes; the clerk decides.
Original wording
At the appropriate place, insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 6190. Ms. MURKOWSKI submitted an amendment intended to be proposed to amendment SA 5499 submitted by Mr. Reed (for himself and Mr. Inhofe) and intended to be proposed to the bill H.R. 7900, to authorize appropriations for fiscal year 2023 for military activities of the Department of Defense, for military construction, and for defense activities of the Department of Energy, to prescribe military personnel strengths for such fiscal year, and for other purposes; which was ordered to lie on the table; as follows:
At the appropriate place, insert the following:
SEC. _____. CERTAIN AMOUNTS TREATED AS EARNED INCOME FOR KIDDIE TAX.
(a) In General.--Section 1(g)(4)(C) of the Internal Revenue Code of 1986 is amended to read as follows:
“(C) Treatment of certain amounts as earned income.--For purposes of this subsection, each of the following amounts shall be treated as earned income of the child referred to in paragraph (1) to the extent included in the gross income of such child:
“(i) Distributions from qualified disability trusts.--Any amount included in the gross income of such child under section 652 or 662 by reason of being a beneficiary of a qualified disability trust (as defined in section 642(b)(2)(C)(ii)).
“(ii) Certain indian tribal payments.--Any payment which is included in the gross income of such child and made by an Indian tribal government (as defined in section 139E(c)(1)), or from a trust of which the Indian tribal government is treated as the owner under subpart E of part I of subchapter J, to or for the benefit of such child if--
“(I) such child or a family member (within the meaning of section 267(c)(4)) is an enrolled member of the tribe with respect to such Indian tribal government, and
“(II) such payment is made by reason of such enrollment.
“(iii) Certain payments from native corporations or settlement trusts.--Any payment which is included in the gross income of such child and--
“(I) made by a Native corporation (as defined in section 646(h)(2)) to or for the benefit of such child if such child or a family member (within the meaning of section 267(c)(4)) has an equity interest in the Native corporation, or
“(II) made by a Settlement Trust (as defined in section 646(h)(4)) to or for the benefit of such child if such child or a family member (within the meaning of section 267(c)(4)) has a beneficial interest in such Settlement Trust.
“(iv) Alaska permanent fund dividends.--The amount of any Alaska Permanent Fund dividend which is included in the gross income of such child.”.
(b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after December 31, 2021.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
September 29, 2022