S.Amdt. 3931Senate119th Congress (2025-2027)
S.Amdt. 3931
Sponsored by 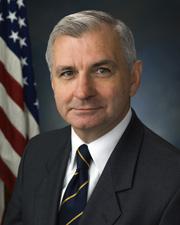 Sen. Jack Reed (D-RI)
Submitted October 9, 2025
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Floor
Latest Action
Senate amendment submitted
October 9, 2025
Text
Submitted
SA 3931. Mr. REED (for himself and Ms. Warren) submitted an amendment
intended to be proposed by him to the bill S. 875, to curtail the
political weaponization of Federal banking agencies by eliminating
reputational risk as a component of the supervision of depository
institutions; which was ordered to lie on the table; as follows:

Strike all after the enacting clause and insert the
following:

SECTION 1. REQUIREMENTS FOR DEPOSIT ACCOUNTS.

(a) Sense of Congress.--It is the sense of Congress that--
(1) appropriate Federal banking agencies have a duty to
ensure that the depository institutions supervised by those
agencies--
(A) are operating in a safe and sound manner; and
(B) have processes and procedures in place to identify
fraudulent or illegal activity, whether activity occurs at a
depository institution or through vendors or customers with
which a depository institution has a relationship;
(2) the duty described in paragraph (1) rests on laws and
regulations, not on personal beliefs or political
motivations;
(3) undue pressure and coercion designed to restrict access
to financial services for lawful businesses have no place at
any appropriate Federal banking agency;
(4) depository institutions should provide banking services
in the communities in which those institutions serve while
carrying out customer identification, risk-based customer
diligence, and suspicious activity monitoring and reporting
obligations under subchapter II of chapter 53 of title 31,
United States Code (referred to in this section as the ``Bank
Secrecy Act''), with respect to the customers of those
institutions;
(5) despite the fact that individual customers of
depository institutions within broader customer categories
present varying degrees of risk, all depository institutions
should take a risk-based approach in assessing individual
customer relationships rather

[[Page S7100]]

than decline to provide banking services to categories of
customers without regard to the risks presented by an
individual customer or the ability of the depository
institution to manage the risk;
(6) depository institutions that properly manage customer
relationships and risks are neither prohibited nor
discouraged from providing services to customers that are
operating in compliance with applicable Federal and State
law; and
(7) each depository institution is responsible for
determining whether providing services to any particular
customer is consistent with the business plan, risk profile,
and management capabilities of the depository institution.
(b) Conditions for Termination.--
(1) In general.--An appropriate Federal banking agency may
not request or require a depository institution to terminate
a specific deposit account or group of deposit accounts ,
unless--
(A) there is a valid reason for that request or
requirement, as described in paragraph (2); and
(B) reputational risk is not the dispositive factor for
that request or requirement.
(2) Valid reasons.--
(A) In general.--To establish a valid reason for a request
or requirement under paragraph (1), the appropriate Federal
banking agency shall document that valid reason, which may
include that the agency has reasonable cause to believe that
the applicable depository institution or any institution-
affiliated party has engaged, is engaged, or is about to
engage in--
(i) an unsafe or unsound practice in conducting business;
(ii) a violation of an applicable law, rule, regulation,
order, condition imposed in writing, formal or informal
enforcement action, or written agency guidance, which shall
include the priorities for anti-money laundering and
countering the financing of terrorism policy established by
the Secretary of the Treasury under section 5318(h)(4) of
title 31, United States Code, or otherwise operating in a
manner that is inconsistent with requirements of the Bank
Secrecy Act; or
(iii) any activity, conduct, or condition that could lead
to, or has led to, the issuance of a matter requiring
attention, a matter requiring immediate attention, a matter
requiring board attention, a document of resolution, or a
supervisory recommendation.
(B) Treatment of national security and illicit finance
threats.--If an appropriate Federal banking agency has
reasonable cause to believe that a specific customer or group
of customers is, or is acting for or on behalf of, an entity
that--
(i) poses a threat to national security;
(ii) is involved in terrorist or other illicit financing;
(iii) is an agent of the Government of Iran, North Korea,
Syria, the People's Republic of China, the Russian
Federation, or any country listed on the State Sponsors of
Terrorism list;
(iv) is in, or is subject to the jurisdiction of, any
country listed on the State Sponsors of Terrorism list;
(v) does business with any entity described in clause (iii)
or (iv), unless the appropriate Federal banking agency
determines that the customer or group of customers has
conducted due diligence to avoid doing business with any
entity described in clause (iii) or (iv); or
(vi) is engaged in--

(I) any other illicit conduct directly or indirectly
supporting a transnational criminal organization, drug
trafficking organization, or money laundering organization;
or
(II) any other criminal activity,

such belief shall satisfy the conditions permitting action by
the appropriate Federal banking agency under paragraph (1).
(c) Notice Requirement.--If an appropriate Federal banking
agency requests or requires a depository institution to
terminate a specific deposit account or a group of deposit
accounts under subsection (b), the agency shall--
(1) provide such request or requirement to the institution
in writing; and
(2) accompany such request or requirement with the valid
reason for the request or requirement, as described in
subsection (b)(2).
(d) Customer Notice.--
(1) Notice required.--Except as provided in paragraph (2),
or as otherwise prohibited from disclosure by law, if an
appropriate Federal banking agency requests or requires a
depository institution to terminate a deposit account under
subsection (b), the depository institution shall notify in
writing the specific customer or group of customers, the
deposit account of which is being terminated, of the valid
reason for that termination, as determined under subsection
(b)(2).
(2) Notice prohibited.--
(A) Notice prohibited in cases of national security and law
enforcement investigations.--
(i) In general.--Neither a depository institution nor an
appropriate Federal banking agency may provide the applicable
customer or group of customers with the notice required under
paragraph (1) if--

(I) a Federal law enforcement agency or an element of the
intelligence community advises the depository institution or
the appropriate Federal banking agency that the notice--

(aa) may interfere with a matter of national security;
(bb) involves a matter described in subsection (b)(2)(B);
or
(cc) may interfere with a law enforcement investigation,
criminal prosecution, or civil action brought by a government
agency; or

(II) the depository institution or appropriate Federal
banking agency knows or should know that, with respect to
that customer or group of customers, a criminal prosecution
or a law enforcement investigation is pending.

(ii) Consultation and recommendations.--An appropriate
Federal banking agency and depository institution shall
consult with, and follow the recommendations of, a Federal
law enforcement agency or element of the intelligence
community, as applicable, regarding whether the notice
described in paragraph (1) is required under that paragraph
or prohibited under clause (i) of this subparagraph.
(B) Notice prohibited in other cases.--If an appropriate
Federal banking agency requests or requires a depository
institution to terminate a specific deposit account or a
group of deposit accounts under subsection (b), neither the
depository institution nor the appropriate Federal banking
agency may notify the customer or group of customers of the
justification for that action, if--
(i) that notice may--

(I) disclose the existence of a report on suspicious
transactions filed under section 5318(g) of title 31, United
States Code; or
(II) reveal confidential supervisory information or a
concern of an appropriate Federal banking agency relating to
an internal control of a depository institution; or

(ii) the appropriate Federal banking agency has reasonable
cause to believe that the depository institution or any
institution-affiliated party has engaged, is engaged, or is
about to engage in--

(I) a violation of an applicable law, rule, regulation,
order, enforcement action, condition imposed in writing, or
formal or informal written agency guidance; or
(II) an unsafe or unsound banking practice relating to that
customer or group of customers.

(e) Reporting Requirement.--Each appropriate Federal
banking agency shall--
(1) submit to the Committee on Banking, Housing, and Urban
Affairs of the Senate and the Committee on Financial Services
of the House of Representatives an annual report stating--
(A) the aggregate number of specific deposit accounts that
the agency requested that a depository institution terminate,
or required a depository institution to terminate, during the
previous year; and
(B) the legal authority on which the agency relied in
making each request and requirement under subparagraph (A)
and the frequency on which the agency relied on each such
authority; and
(2) before submitting each report required under paragraph
(1), provide the Inspector General of the agency with an
opportunity to conduct an evaluation or review of the
activity described in that report, which the Inspector
General shall submit to the committees described in paragraph
(1) concurrently with the submission of the report under
paragraph (1).
(f) Biennial FDIC and NCUA Survey on Access to Deposit
Accounts by Small and Medium-sized Businesses.--
(1) In general.--The Federal Deposit Insurance Corporation
and the National Credit Union Administration shall conduct a
biennial survey on the efforts of depository institutions to
provide greater access to deposit accounts to small and
medium-sized businesses that may have encountered
difficulties in accessing or maintaining deposit accounts.
(2) Considerations.--In conducting each survey required
under paragraph (1), the Federal Deposit Insurance
Corporation and the National Credit Union Administration
shall consider what issues and barriers most frequently
prevent small and medium-sized businesses from accessing or
maintaining deposit accounts that are necessary to operate
those businesses.
(g) Rule of Construction.--Nothing in this section may be
construed to limit or restrict the authority of an
appropriate Federal banking agency to--
(1) identify or discuss potential supervisory findings with
the staff or management of a depository institution,
including findings involving financial condition, governance,
consumer protection, internal controls, or unsafe or unsound
conditions; or
(2) identify or discuss deficiencies in compliance or risks
associated with the Bank Secrecy Act, including anti-money
laundering or countering the financing of terrorism
practices.
(h) Definitions.--In this section:
(1) Appropriate federal banking agency.--The term
``appropriate Federal banking agency'' means--
(A) the appropriate Federal banking agency, as defined in
section 3 of the Federal Deposit Insurance Act (12 U.S.C.
1813); and
(B) the National Credit Union Administration, in the case
of an insured credit union, as defined in section 101 of the
Federal Credit Union Act (12 U.S.C. 1752).
(2) Depository institution.--The term ``depository
institution'' means--
(A) a depository institution, as defined in section 3 of
the Federal Deposit Insurance Act (12 U.S.C. 1813); and
(B) an insured credit union, as defined in section 101 of
the Federal Credit Union Act (12 U.S.C. 1752).
(3) Intelligence community.--The term ``intelligence
community'' has the meaning

[[Page S7101]]

given the term in section 3 of the National Security Act of
1947 (50 U.S.C. 3003).

____________________