S.Amdt. 4321Senate119th Congress (2025-2027)
S.Amdt. 4321
Sponsored by 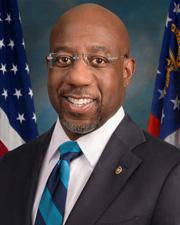 Sen. Raphael G. Warnock (D-GA)
Submitted March 4, 2026
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Floor
Latest Action
Senate amendment submitted
March 4, 2026
Text
Submitted
SA 4321. Mr. WARNOCK submitted an amendment intended to be proposed
by him to the bill H.R. 6644, a bill to increase the supply of housing
in America, and for other purposes; which was ordered to lie on the
table; as follows:

At the appropriate place, insert the following:

SEC. ___. REFUNDABLE CREDIT FOR RENT PAID FOR PRINCIPAL
RESIDENCE.

(a) In General.--Subpart C of part IV of subchapter A of
chapter 1 of the Internal Revenue Code of 1986 is amended by
inserting after section 36B the following new section:

``SEC. 36C. RENT PAID FOR PRINCIPAL RESIDENCE.

``(a) In General.--In the case of an individual who leases
the individual's principal residence (within the meaning of
section 121) during the taxable year and who pays rent with
respect to such residence in excess of 30 percent of the
taxpayer's gross income for such taxable year, there shall be
allowed as a credit against the tax imposed by this subtitle
for such taxable year an amount equal to the applicable
percentage of such excess.
``(b) Credit Limited by 100 Percent of Small Area Fair
Market Rent.--Solely for purposes of determining the amount
of the credit allowed under subsection (a) with respect to a
residence for the taxable year, there shall not be taken into
account rent in excess of an amount equal to 100 percent of
the small area fair market rent (including the utility
allowance) applicable to the residence involved (as most
recently published, as of the beginning of the taxable year,
by the Department of Housing and Urban Development).
``(c) Definitions and Special Rules.--For purposes of this
section--
``(1) Applicable percentage.--
``(A) In general.--Except as provided in subparagraph (B),
the applicable percentage shall be determined in accordance
with the following table:

The applicable
``If gross income is:                                    percentage is:
Not over $25,000.........................................100 percent
Over $25,000, but not over $50,000........................75 percent
Over $50,000, but not over $75,000........................50 percent
Over $75,000, but not over $100,000.......................25 percent
Over $100,000..............................................0 percent.
``(B) High-cost areas.--In the case of an individual whose
principal residence is located in an area designated by the
Secretary of Housing and Urban Development as an area which
has high construction, land, or utility costs relative to
area median gross income for purposes of section 42(d)(5),
each of the dollar amounts in the table contained in
subparagraph (A) shall be increased by $25,000.
``(2) Partial year residence.--The Secretary shall
prescribe such rules as are necessary to carry out the
purposes of this section for taxpayers with respect to whom a
residence is a principal residence for only a portion of the
taxable year.
``(3) Special rule for individuals residing in government-
subsidized housing.--In the case of a principal residence--
``(A) the rent with respect to which is subsidized under a
Federal, State, local, or tribal program, and
``(B) with respect to which the taxpayer elects the
application of this paragraph,
in lieu of the credit determined under subsection (a), there
shall be allowed as a credit against the tax imposed by this
subtitle for such taxable year an amount equal to \1/12\ of
the amount of rent paid by the taxpayer (and not subsidized
under any such program) during the taxable year with respect
to such residence.
``(4) Rent.--The term `rent' includes any amount paid for
utilities of a type taken into account for purposes of
determining the utility allowance under section
42(g)(2)(B)(ii).
``(d) Reconciliation of Credit and Advance Payments.--The
amount of the credit allowed under this section for any
taxable year shall be reduced (but not below zero) by the
aggregate amount of any advance payments of such credit under
section 7527B for such taxable year.''.
(b) Advance Payment.--Chapter 77 of the Internal Revenue
Code of 1986 is amended by inserting after section 7527A the
following new section:

``SEC. 7527B. ADVANCE PAYMENT OF RENT CREDIT.

``(a) In General.--Not later than 6 months after the date
of the enactment of this section, the Secretary shall
establish a program for making advance payments of the credit
allowed under section 36C on a monthly basis to any taxpayer
who--
``(1) the Secretary has determined will be allowed such
credit for the taxable year, and
``(2) has made an election under subsection (c).
``(b) Amount of Advance Payment.--
``(1) In general.--For purposes of subsection (a), the
amount of the monthly advance payment of the credit provided
to a taxpayer during the applicable period shall be equal to
the lesser of--
``(A) an amount equal to--
``(i) the amount of the credit which the Secretary has
determined will be allowed to such taxpayer under section 36C
for the taxable year ending in such applicable period,
divided by
``(ii) 12, or
``(B) such other amount as is elected by the taxpayer.
``(2) Applicable period.--For purposes of this section, the
term `applicable period' means the 12-month period from the
month of July of the taxable year through the month of June
of the subsequent taxable year.
``(c) Election of Advance Payment.--A taxpayer may elect to
receive an advance payment of the credit allowed under
section 36C for any taxable year by including such election
on a timely filed return for the preceding taxable year.
``(d) Internal Revenue Service Notification.--The Internal
Revenue Service shall take such steps as may be appropriate
to ensure that taxpayers who are eligible to receive the
credit under section 36C are aware of the availability of the
advance payment of such credit under this section.
``(e) Authority.--The Secretary may prescribe such
regulations or other guidance as may be appropriate or
necessary for the purposes of carrying out this section.''.
(c) Conforming Amendments.--
(1) Section 6211(b)(4)(A) of the Internal Revenue Code of
1986 is amended by inserting ``, 36C'' after ``36B''.
(2) Paragraph (2) of section 1324(b) of title 31, United
States Code, is amended by inserting ``, 36C'' after ``36B''.
(d) Clerical Amendments.--
(1) In general.--The table of sections for subpart C of
part IV of subchapter A of chapter 1 of the Internal Revenue
Code of 1986 is amended by inserting after the item relating
to section 36B the following new item:
``Sec. 36C. Rent paid for principal residence.''.
(2) Advance payment.--The table of sections for chapter 77
of such Code is amended by inserting after the item relating
to section 7527A the following new item:
``Sec. 7527B. Advance payment of middle class tax credit.''.
(e) Effective Date.--The amendments made by this section
shall apply to taxable years beginning after December 31,
2025.

[[Page S840]]

______