S.Amdt. 5528Senate119th Congress (2025-2027)2nd degree
S.Amdt. 5528
Sponsored by 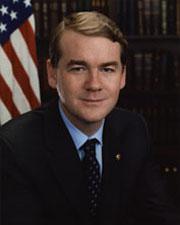 Sen. Michael F. Bennet (D-CO)
Submitted June 3, 2026
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Floor
Latest Action
Senate amendment submitted
June 3, 2026
Text
Submitted
SA 5528. Mr. BENNET submitted an amendment intended to be proposed to
amendment SA 5453 proposed by Mr. Graham to the bill S. 2, to provide
for reconciliation pursuant to title II of S. Con. Res. 33; which was
ordered to lie on the table; as follows:

Strike section 202 and insert the following:

SEC. 202. GASOLINE PRICE REBATES.

(a) In General.--Subchapter B of chapter 65 of the Internal
Revenue Code of 1986 is amended by adding at the end the
following new section:

``SEC. 6436. GASOLINE PRICE REBATES.

``(a) In General.--In the case of an eligible individual,
there shall be allowed as a credit against the tax imposed by
subtitle A for the taxable year beginning after December 31,
2025, an amount equal to the gasoline price rebate amount for
such taxable year.
``(b) Gasoline Price Rebate Amount.--For purposes of this
section--
``(1) In general.--The term `gasoline price rebate amount'
means, with respect to any taxpayer, an amount, as determined
by the Secretary not later than 30 days after the date of
enactment of this section, equal to the quotient of--
``(A) $31,075,000,000, divided by
``(B) the number of eligible individuals.
``(2) Special rule for joint returns.--In the case of an
eligible individual filing a joint return, the gasoline price
rebate amount shall be 150 percent of the amount determined
under paragraph (1) with respect to other taxpayers.
``(3) Limitation based on adjusted gross income.--The
amount of the credit allowed by subsection (a) (determined
without regard to this subsection and subsection (e)) shall
be reduced (but not below zero) by 5 percent of so much of
the eligible individual's adjusted gross income as exceeds--
``(A) $150,000 in the case of a joint return,
``(B) $112,500 in the case of a head of household, and
``(C) $75,000 in any other case.
``(c) Eligible Individual.--For purposes of this section,
the term `eligible individual' means any individual other
than--
``(1) any nonresident alien individual,
``(2) any individual who is a dependent of another taxpayer
for a taxable year beginning in the calendar year in which
the individual's taxable year begins, and
``(3) an estate or trust.
``(d) Definitions and Special Rules.--
``(1) Dependent defined.--For purposes of this section, the
term `dependent' has the meaning given such term by section
152.
``(2) Identification number requirement.--
``(A) In general.--In the case of a return other than a
joint return, the gasoline price rebate amount in subsection
(b)(1) shall be treated as being zero unless the taxpayer
includes the valid identification number of the taxpayer on
the return of tax for the taxable year.
``(B) Joint returns.--In the case of a joint return, the
gasoline price rebate amount in subsection (b)(1) shall be
treated as being--
``(i) 50 percent of the amount otherwise determined without
regard to this paragraph if the valid identification number
of only 1 spouse is included on the return of tax for the
taxable year, and
``(ii) zero if the valid identification number of neither
spouse is so included.
``(C) Valid identification number.--For purposes of this
paragraph, the term `valid identification number' means a
social security number issued to an individual by the Social
Security Administration on or before the due date for filing
the return for the taxable year.
``(D) Special rule for members of the armed forces.--
Subparagraph (B) shall not apply in the case where at least 1
spouse was a member of the Armed Forces of the United States
at any time during the taxable year and the valid
identification number of at least 1 spouse is included on the
return of tax for the taxable year.
``(E) Coordination with certain advance payments.--In the
case of any payment determined pursuant to subsection (f)(6),
a valid identification number shall be treated for purposes
of this paragraph as included on the taxpayer's return of tax
if such valid identification number is available to the
Secretary as described in such subsection.
``(F) Mathematical or clerical error authority.--Any
omission of a correct valid identification number required
under this paragraph shall be treated as a mathematical or
clerical error for purposes of applying section 6213(g)(2) to
such omission.
``(3) Credit treated as refundable.--The credit allowed by
subsection (a) shall be treated as allowed by subpart C of
part IV of subchapter A of chapter 1.
``(e) Regulations.--The Secretary shall prescribe such
regulations or other guidance as may be necessary or
appropriate to carry out the purposes of this section.

[[Page S2539]]

``(f) Outreach.--The Secretary shall carry out a robust and
comprehensive outreach program to ensure that all taxpayers
learn of their eligibility for the credits allowed under this
section and are provided assistance in claiming such
credits.''.
(b) Treatment of Certain Possessions.--
(1) Payments to possessions with mirror code tax systems.--
The Secretary of the Treasury shall pay to each possession of
the United States which has a mirror code tax system amounts
equal to the loss (if any) to that possession by reason of
the amendments made by this section. Such amounts shall be
determined by the Secretary of the Treasury based on
information provided by the government of the respective
possession.
(2) Payments to other possessions.--The Secretary of the
Treasury shall pay to each possession of the United States
which does not have a mirror code tax system amounts
estimated by the Secretary of the Treasury as being equal to
the aggregate benefits (if any) that would have been provided
to residents of such possession by reason of the amendments
made by this section if a mirror code tax system had been in
effect in such possession. The preceding sentence shall not
apply unless the respective possession has a plan, which has
been approved by the Secretary of the Treasury, under which
such possession will promptly distribute such payments to its
residents.
(3) Inclusion of administrative expenses.--The Secretary of
the Treasury shall pay to each possession of the United
States to which the Secretary makes a payment under paragraph
(1) or (2) an amount equal to the increase (if any) of the
administrative expenses of such possession--
(A) in the case of a possession described in paragraph (1),
by reason of the amendments made by this section, and
(B) in the case of a possession described in paragraph (2),
by reason of carrying out the plan described in such
paragraph, or
the amount described in subparagraph (A) shall be determined
by the Secretary of the Treasury based on information
provided by the government of the respective possession.
(4) Coordination with credit allowed against united states
income taxes.--No credit shall be allowed against United
States income taxes under section 6434 of the Internal
Revenue Code of 1986 (as added by this section) to any
person--
(A) to whom a credit is allowed against taxes imposed by
the possession by reason of the amendments made by this
section, or
(B) who is eligible for a payment under a plan described in
paragraph (2).
(5) Mirror code tax system.--For purposes of this
subsection, the term ``mirror code tax system'' means, with
respect to any possession of the United States, the income
tax system of such possession if the income tax liability of
the residents of such possession under such system is
determined by reference to the income tax laws of the United
States as if such possession were the United States.
(6) Treatment of payments.--For purposes of section 1324 of
title 31, United States Code, the payments under this
subsection shall be treated in the same manner as a refund
due from a credit provision referred to in subsection (b)(2)
of such section.
(c) Administrative Provisions.--
(1) Definition of deficiency.--Section 6211(b)(4)(A) of the
Internal Revenue Code of 1986 is amended by striking ``and
6433'' and inserting ``6433, and 6436,''.
(2) Conforming amendments.--
(A) Paragraph (2) of section 1324(b) of title 31, United
States Code, is amended by inserting ``6436,'' after
``6433,''.
(B) The table of sections for subchapter B of chapter 65 of
the Internal Revenue Code of 1986 is amended by adding at the
end the following new item:
``Sec. 6436. Gasoline price rebates.''.
______