S.Amdt. 6710Senate119th Congress (2025-2027)
S.Amdt. 6710
Sponsored by 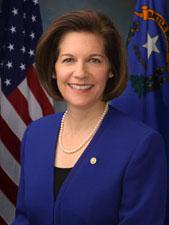 Sen. Catherine Cortez Masto (D-NV)
Submitted July 29, 2026
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Floor
Latest Action
Senate amendment submitted
July 29, 2026
Text
Submitted
SA 6710. Ms. CORTEZ MASTO submitted an amendment intended to be
proposed by her to the bill H.R. 5334, to amend the Internal Revenue
Code of 1986 to allow early childhood educators to take the educator
expense deduction, and for other purposes; which was ordered to lie on
the table; as follows:

At the appropriate place, insert the following:

SEC. ___. DENIAL OF FOREIGN TAX CREDIT WITH RESPECT TO THE
RUSSIAN FEDERATION.

(a) In General.--Section 901(j)(2) of the Internal Revenue
Code of 1986 is amended by adding at the end the following
new subparagraph:
``(C) Special rule for russia.--
``(i) In general.--This subsection shall apply to the
Russian Federation during the period described in clause
(ii).
``(ii) Period of application.--The period described in this
clause with respect to any country is the period--

``(I) beginning on the date that is 30 days after the date
of the enactment of this subparagraph, and
``(II) ending on the date on which the resumption of the
application of the rates of duty set forth in column 1 of the
Harmonized Tariff Schedule of the United States to products
of that country takes effect pursuant to section 4(b) of the
Suspending Normal Trade Relations with Russia and Belarus
Act.''.

(b) Deduction Denied.--Section 901(j)(3) of such Code is
amended by adding at the end the following new sentence:
``The preceding sentence shall not apply to any tax of any
country to which paragraph (2)(C) applies.''.
(c) Effective Dates.--
(1) In general.--Except as provided in paragraph (2), the
amendments made by this section shall take effect on the date
of the enactment of this Act.
(2) Deduction limitation.--The amendment made by subsection
(b) shall apply to taxes paid or accrued (or deemed paid or
accrued under section 960 of the Internal Revenue Code of
1986) after the date that is 90 days after the date of the
enactment of this Act.
(3) Nonapplication of treaty rules.--This section and the
amendments made by this section shall be applied without
regard to any treaty obligation of the United States.
______