Armed Forces Tax Fairness Act of 2003
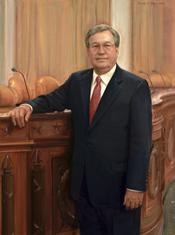 Rep. William M. Thomas (R-CA)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Message on Senate action sent to the House.
March 31, 2003
View full timeline
Introduced in House
March 18, 2003
Referred to the House Committee on Ways and Means.
March 18, 2003
Mr. Thomas moved to suspend the rules and pass the bill.
March 19, 2003 • 10:49 AM
Considered under suspension of the rules. (consideration: CR H1964-1970)
March 19, 2003 • 10:51 AM
DEBATE - The House proceeded with forty minutes of debate on H.R. 1307.
March 19, 2003 • 10:51 AM
At the conclusion of debate, the Yeas and Nays were demanded and ordered. Pursuant to the provisions of clause 8, rule XX, the Chair announced that further proceedings on the motion would be postponed.
March 19, 2003 • 11:19 AM
Considered as unfinished business. (consideration: CR H2136-2137)
March 20, 2003 • 10:40 AM
Passed/agreed to in House: On motion to suspend the rules and pass the bill Agreed to by the Yeas and Nays: (2/3 required): 422 - 0 (Roll no. 76).(text: CR 3/19/2003 H1964-1966)
March 20, 2003 • 10:48 AM
On motion to suspend the rules and pass the bill Agreed to by the Yeas and Nays: (2/3 required): 422 - 0 (Roll no. 76). (text: CR 3/19/2003 H1964-1966)
March 20, 2003 • 10:48 AM
Motion to reconsider laid on the table Agreed to without objection.
March 20, 2003 • 10:48 AM
Received in the Senate.
March 20, 2003
Measure laid before Senate by unanimous consent. (consideration: CR S4472-4483, S4490-4495)
March 27, 2003
Passed Senate with an amendment by Yea-Nay Vote. 97 - 0. Record Vote Number: 110. (text: CR S4490-4495)
March 27, 2003
Message on Senate action sent to the House.
March 31, 2003
Voting History
2 votes recorded • Roll call available
Floor Debate
22 membersWhat members said about H.R. 1307 on the floor


 +17
Floor Debate
22 membersWhat members said about H.R. 1307 on the floor
I suggest the absence of a quorum. Mr. President, I ask unanimous consent that the order for the quorum call be rescinded. Mr. President, thousands of men and women from Montana are currently…
Mr. Speaker, by direction of the Committee on Rules, I call up House Resolution 270 and ask for its immediate consideration. Mr. Speaker, for the purpose of debate only, I yield the customary 30…
Mr. Speaker, I yield myself such time as I may consume. (Mr. FROST asked and was given permission to revise and extend his remarks.) Mr. Speaker, while this bill purports to give low-income people a…
Mr. President, we are now awaiting the arrival of the chairman of the committee. Pending his arrival, I suggest the absence of a quorum. Mr. President, I ask unanimous consent that the order for the…
Mr. President, I am proud to be an original cosponsor of the Armed Forces Tax Fairness Act of 2003, H.R. 1307. This important legislation provides Congress with the opportunity to demonstrate our…
Show 8 more
Mr. Speaker, I thank the gentleman from Texas (Mr. Frost) for yielding me time and for the magnificent way that he has managed this rule today. Little did we know when we were discussing this issue…

Mr. President, it is a privilege for me to be before the Senate again in a working relationship with Senator Baucus, the ranking Democrat of the Senate Finance Committee. It is another example of…

Mr. President, I know that my friends and colleagues, Senator Grassley from Iowa and Senator Baucus from Montana, share my concerns about the safety and welfare of our troops in the field and their…

Mr. Speaker, last week Colorado experienced a very heavy snowstorm--in fact, it was a blizzard in many areas. This was good news for our state, which has been suffering from a serious drought.…

Mr. President, I rise today with great pride to support the Armed Forces Tax Fairness Act. As I speak, America's military is fighting in the dangerous and inhospitable deserts of Iraq. And when I…

Mr. President, I am very pleased that the Finance Committee has moved the important provisions of this bill to the Senate floor and I urge that the bill be passed. The current Tax Code does not…
Mr. Speaker, I move to suspend the rules and pass the bill (H.R. 1664) to amend the Internal Revenue Code of 1986 to provide a special rule for members of the uniformed services in determining the…
Mr. President, I rise in strong support for this piece of legislation. I compliment my long-time friend, the Senator from Montana, for his work. We have enjoyed many projects together over the…
Show 11 more

Mr. Speaker, I rise today to express my support of H.R. 1664, the Armed Forces Tax Fairness Act of 2003. It has been long overdue that we provide real relief to the men and women who serve in our…

Mr. Speaker, following that fascinating display, I would like to rise and indicate that as the economic downturn began during the last 2 quarters of 2000, we worked very hard to ensure that we could…
Mr. Speaker, I rise today in strong opposition to H.R. 1308, the ``Only If you Make Enough Money'' All American Tax Relief Act of 2003. In the Federalist Papers, Alexander Hamilton writes, ``I know…
Mr. President, I rise today to share my strong support for this much needed and much deserved military tax package. I commend Chairman Grassley and my many colleagues who have worked so hard on this…

Mr. Speaker, I have a parliamentary observation. Mr. Speaker, I would make a parliamentary observation. If we keep raising the debt as fast as we are raising it---- Well, I am, because it will be a…
Mr. Speaker, this is a big one. This bill really crystallizes the differences between the two parties, and the American people should know exactly what is going on here today. We are here to answer…
Mr. Speaker, will the gentleman yield? Mr. Speaker, is it not true that the Democrats did not pass a budget last year, and during the period of time after 9/11 when we were trying to fund the troops…
Mr. Speaker, I move to suspend the rules and pass the bill (H.R. 1307) to amend the Internal Revenue Code of 1986 to provide a special rule for members of the uniformed services in determining the…
Mr. Speaker: It is the soldier, not the reporter, Who has given us freedom of the press. It is the soldier, not the poet, Who has given us freedom of speech. It is the soldier, not the organizer, Who…
Mr. Speaker, this Member rises in strong support of H.R. 1307, the Armed Forces Tax Fairness Act of 2003, as it relates to the members of our armed services--active duty, reserve components, and…
Mr. President, I ask unanimous consent that I may speak for up to 5 minutes on the pending bill. Mr. President, in these halls we often talk about the need to provide our military personnel with the…
Bill Text
4 versions available
        [Congressional Bills 108th Congress]
[From the U.S. Government Publishing Office]
[H.R. 1307 Engrossed Amendment Senate (EAS)]

In the Senate of the United States,

March 27, 2003.
Resolved, That the bill from the House of Representatives (H.R.
1307) entitled ``An Act to amend the Internal Revenue Code of 1986 to
provide a special rule for members of the uniformed services in
determining the exclusion of gain from the sale of a principal
residence and to restore the tax exempt status of death gratuity
payments to members of the uniformed services, and for other
purposes.'', do pass with the following

AMENDMENT:

Strike out all after the enacting clause and insert:

SECTION 1. SHORT TITLE; ETC.

(a) Short Title.--This Act may be cited as the ``Armed Forces Tax
Fairness Act of 2003''.
(b) Amendment of 1986 Code.--Except as otherwise expressly
provided, whenever in this Act an amendment or repeal is expressed in
terms of an amendment to, or repeal of, a section or other provision,
the reference shall be considered to be made to a section or other
provision of the Internal Revenue Code of 1986.
(c) Table of Contents.--The table of contents for this Act is as
follows:

Sec. 1. Short title; etc.

TITLE I--IMPROVING TAX EQUITY FOR MILITARY PERSONNEL

Sec. 101. Exclusion of gain from sale of a principal residence by a
member of the uniformed services or the
Foreign Service.
Sec. 102. Exclusion from gross income of certain death gratuity
payments.
Sec. 103. Exclusion for amounts received under Department of Defense
Homeowners Assistance Program.
Sec. 104. Expansion of combat zone filing rules to contingency
operations.
Sec. 105. Modification of membership requirement for exemption from tax
for certain veterans' organizations.
Sec. 106. Clarification of treatment of certain dependent care
assistance programs.
Sec. 107. Clarification relating to exception from additional tax on
certain distributions from qualified
tuition programs, etc. on account of
attendance at military academy.
Sec. 108. Suspension of tax-exempt status of terrorist organizations.
Sec. 109. Above-the-line deduction for overnight travel expenses of
National Guard and Reserve members.
Sec. 110. Tax relief and assistance for families of Space Shuttle
Columbia heroes.

TITLE II--OTHER PROVISIONS

Sec. 201. Extension of IRS user fees.
Sec. 202. Partial payment of tax liability in installment agreements.
Sec. 203. Revision of tax rules on expatriation.

TITLE I--IMPROVING TAX EQUITY FOR MILITARY PERSONNEL

SEC. 101. EXCLUSION OF GAIN FROM SALE OF A PRINCIPAL RESIDENCE BY A
MEMBER OF THE UNIFORMED SERVICES OR THE FOREIGN SERVICE.

(a) In General.--Subsection (d) of section 121 (relating to
exclusion of gain from sale of principal residence) is amended by
redesignating paragraph (9) as paragraph (10) and by inserting after
paragraph (8) the following new paragraph:
``(9) Members of uniformed services and foreign service.--
``(A) In general.--At the election of an individual
with respect to a property, the running of the 5-year
period described in subsections (a) and (c)(1)(B) and
paragraph (7) of this subsection with respect to such
property shall be suspended during any period that such
individual or such individual's spouse is serving on
qualified official extended duty as a member of the
uniformed services or of the Foreign Service of the
United States.
``(B) Maximum period of suspension.--The 5-year
period described in subsection (a) shall not be
extended more than 10 years by reason of subparagraph
(A).
``(C) Qualified official extended duty.--For
purposes of this paragraph--
``(i) In general.--The term `qualified
official extended duty' means any extended duty
while serving at a duty station which is at
least 50 miles from such property or while
residing under Government orders in Government
quarters.
``(ii) Uniformed services.--The term
`uniformed services' has the meaning given such
term by section 101(a)(5) of title 10, United
States Code, as in effect on the date of the
enactment of this paragraph.
``(iii) Foreign service of the united
states.--The term `member of the Foreign
Service of the United States' has the meaning
given the term `member of the Service' by
paragraph (1), (2), (3), (4), or (5) of section
103 of the Foreign Service Act of 1980, as in
effect on the date of the enactment of this
paragraph.
``(iv) Extended duty.--The term `extended
duty' means any period of active duty pursuant
to a call or order to such duty for a period in
excess of 90 days or for an indefinite period.
``(D) Special rules relating to election.--
``(i) Election limited to 1 property at a
time.--An election under subparagraph (A) with
respect to any property may not be made if such
an election is in effect with respect to any
other property.
``(ii) Revocation of election.--An election
under subparagraph (A) may be revoked at any
time.''.
(b) Effective Date; Special Rule.--
(1) Effective date.--The amendments made by this section
shall take effect as if included in the amendments made by
section 312 of the Taxpayer Relief Act of 1997.
(2) Waiver of limitations.--If refund or credit of any
overpayment of tax resulting from the amendments made by this
section is prevented at any time before the close of the 1-year
period beginning on the date of the enactment of this Act by
the operation of any law or rule of law (including res
judicata), such refund or credit may nevertheless be made or
allowed if claim therefor is filed before the close of such
period.

SEC. 102. EXCLUSION FROM GROSS INCOME OF CERTAIN DEATH GRATUITY
PAYMENTS.

(a) In General.--Subsection (b)(3) of section 134 (relating to
certain military benefits) is amended by adding at the end the
following new subparagraph:
``(C) Exception for death gratuity adjustments made
by law.--Subparagraph (A) shall not apply to any
adjustment to the amount of death gratuity payable
under chapter 75 of title 10, United States Code, which
is pursuant to a provision of law enacted after
September 9, 1986.''.
(b) Conforming Amendment.--Subparagraph (A) of section 134(b)(3) is
amended by striking ``subparagraph (B)'' and inserting ``subparagraphs
(B) and (C)''.
(c) Effective Date.--The amendments made by this section shall
apply with respect to deaths occurring after September 10, 2001.

SEC. 103. EXCLUSION FOR AMOUNTS RECEIVED UNDER DEPARTMENT OF DEFENSE
HOMEOWNERS ASSISTANCE PROGRAM.

(a) In General.--Section 132(a) (relating to the exclusion from
gross income of certain fringe benefits) is amended by striking ``or''
at the end of paragraph (6), by striking the period at the end of
paragraph (7) and inserting ``, or'', and by adding at the end the
following new paragraph:
``(8) qualified military base realignment and closure
fringe.''.
(b) Qualified Military Base Realignment and Closure Fringe.--
Section 132 is amended by redesignating subsection (n) as subsection
(o) and by inserting after subsection (m) the following new subsection:
``(n) Qualified Military Base Realignment and Closure Fringe.--For
purposes of this section--
``(1) In general.--The term `qualified military base
realignment and closure fringe' means 1 or more payments under
the authority of section 1013 of the Demonstration Cities and
Metropolitan Development Act of 1966 (42 U.S.C. 3374) (as in
effect on the date of the enactment of this subsection) to
offset the adverse effects on housing values as a result of a
military base realignment or closure.
``(2) Limitation.--With respect to any property, such term
shall not include any payment referred to in paragraph (1) to
the extent that the sum of all of such payments related to such
property exceeds the maximum amount described in clause (1) of
subsection (c) of such section (as in effect on such date).''.
(c) Effective Date.--The amendments made by this section shall
apply to payments made after the date of the enactment of this Act.

SEC. 104. EXPANSION OF COMBAT ZONE FILING RULES TO CONTINGENCY
OPERATIONS.

(a) In General.--Section 7508(a) (relating to time for performing
certain acts postponed by reason of service in combat zone) is
amended--
(1) by inserting ``, or when deployed outside the United
States away from the individual's permanent duty station while
participating in an operation designated by the Secretary of
Defense as a contingency operation (as defined in section
101(a)(13) of title 10, United States Code) or which became
such a contingency operation by operation of law'' after
``section 112'',
(2) by inserting in the first sentence ``or at any time
during the period of such contingency operation'' after ``for
purposes of such section'',
(3) by inserting ``or operation'' after ``such an area'',
and
(4) by inserting ``or operation'' after ``such area''.
(b) Conforming Amendments.--
(1) Section 7508(d) is amended by inserting ``or
contingency operation'' after ``area''.
(2) The heading for section 7508 is amended by inserting
``or contingency operation'' after ``combat zone''.
(3) The item relating to section 7508 in the table of
sections for chapter 77 is amended by inserting ``or
contingency operation'' after ``combat zone''.
(c) Effective Date.--The amendments made by this section shall
apply to any period for performing an act which has not expired before
the date of the enactment of this Act.

SEC. 105. MODIFICATION OF MEMBERSHIP REQUIREMENT FOR EXEMPTION FROM TAX
FOR CERTAIN VETERANS' ORGANIZATIONS.

(a) In General.--Subparagraph (B) of section 501(c)(19) (relating
to list of exempt organizations) is amended by striking ``or widowers''
and inserting ``, widowers, ancestors, or lineal descendants''.
(b) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after the date of the enactment of
this Act.

SEC. 106. CLARIFICATION OF THE TREATMENT OF CERTAIN DEPENDENT CARE
ASSISTANCE PROGRAMS.

(a) In General.--Section 134(b) (defining qualified military
benefit) is amended by adding at the end the following new paragraph:
``(4) Clarification of certain benefits.--For purposes of
paragraph (1), such term includes any dependent care assistance
program (as in effect on the date of the enactment of this
paragraph) for any individual described in paragraph (1)(A).''.
(b) Conforming Amendments.--
(1) Section 134(b)(3)(A), as amended by section 102, is
amended by inserting ``and paragraph (4)'' after
``subparagraphs (B) and (C)''.
(2) Section 3121(a)(18) is amended by striking ``or 129''
and inserting ``, 129, or 134(b)(4)''.
(3) Section 3306(b)(13) is amended by striking ``or 129''
and inserting ``, 129, or 134(b)(4)''.
(4) Section 3401(a)(18) is amended by striking ``or 129''
and inserting ``, 129, or 134(b)(4)''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2002.
(d) No Inference.--No inference may be drawn from the amendments
made by this section with respect to the tax treatment of any amounts
under the program described in section 134(b)(4) of the Internal
Revenue Code of 1986 (as added by this section) for any taxable year
beginning before January 1, 2003.

SEC. 107. CLARIFICATION RELATING TO EXCEPTION FROM ADDITIONAL TAX ON
CERTAIN DISTRIBUTIONS FROM QUALIFIED TUITION PROGRAMS,
ETC. ON ACCOUNT OF ATTENDANCE AT MILITARY ACADEMY.

(a) In General.--Subparagraph (B) of section 530(d)(4) (relating to
exceptions from additional tax for distributions not used for
educational purposes) is amended by striking ``or'' at the end of
clause (iii), by redesignating clause (iv) as clause (v), and by
inserting after clause (iii) the following new clause:
``(iv) made on account of the attendance of
the designated beneficiary at the United States
Military Academy, the United States Naval
Academy, the United States Air Force Academy,
the United States Coast Guard Academy, or the
United States Merchant Marine Academy, to the
extent that the amount of the payment or
distribution does not exceed the costs of
advanced education (as defined by section
2005(e)(3) of title 10, United States Code, as
in effect on the date of the enactment of this
section) attributable to such attendance, or''.
(b) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2002.

SEC. 108. SUSPENSION OF TAX-EXEMPT STATUS OF TERRORIST ORGANIZATIONS.

(a) In General.--Section 501 (relating to exemption from tax on
corporations, certain trusts, etc.) is amended by redesignating
subsection (p) as subsection (q) and by inserting after subsection (o)
the following new subsection:
``(p) Suspension of Tax-Exempt Status of Terrorist Organizations.--
``(1) In general.--The exemption from tax under subsection
(a) with respect to any organization described in paragraph
(2), and the eligibility of any organization described in
paragraph (2) to apply for recognition of exemption under
subsection (a), shall be suspended during the period described
in paragraph (3).
``(2) Terrorist organizations.--An organization is
described in this paragraph if such organization is designated
or otherwise individually identified--
``(A) under section 212(a)(3)(B)(vi)(II) or 219 of
the Immigration and Nationality Act as a terrorist
organization or foreign terrorist organization,
``(B) in or pursuant to an Executive order which is
related to terrorism and issued under the authority of
the International Emergency Economic Powers Act or
section 5 of the United Nations Participation Act of
1945 for the purpose of imposing on such organization
an economic or other sanction, or
``(C) in or pursuant to an Executive order issued
under the authority of any Federal law if--
``(i) the organization is designated or
otherwise individually identified in or
pursuant to such Executive order as supporting
or engaging in terrorist activity (as defined
in section 212(a)(3)(B) of the Immigration and
Nationality Act) or supporting terrorism (as
defined in section 140(d)(2) of the Foreign
Relations Authorization Act, Fiscal Years 1988
and 1989); and
``(ii) such Executive order refers to this
subsection.
``(3) Period of suspension.--With respect to any
organization described in paragraph (2), the period of
suspension--
``(A) begins on the later of--
``(i) the date of the first publication of
a designation or identification described in
paragraph (2) with respect to such
organization, or
``(ii) the date of the enactment of this
subsection, and
``(B) ends on the first date that all designations
and identifications described in paragraph (2) with
respect to such organization are rescinded pursuant to
the law or Executive order under which such designation
or identification was made.
``(4) Denial of deduction.--No deduction shall be allowed
under any provision of this title, including sections 170,
545(b)(2), 556(b)(2), 642(c), 2055, 2106(a)(2), and 2522, with
respect to any contribution to an organization described in
paragraph (2) during the period described in paragraph (3).
``(5) Denial of administrative or judicial challenge of
suspension or denial of deduction.--Notwithstanding section
7428 or any other provision of law, no organization or other
person may challenge a suspension under paragraph (1), a
designation or identification described in paragraph (2), the
period of suspension described in paragraph (3), or a denial of
a deduction under paragraph (4) in any administrative or
judicial proceeding relating to the Federal tax liability of
such organization or other person.
``(6) Erroneous designation.--
``(A) In general.--If--
``(i) the tax exemption of any organization
described in paragraph (2) is suspended under
paragraph (1),
``(ii) each designation and identification
described in paragraph (2) which has been made
with respect to such organization is determined
to be erroneous pursuant to the law or
Executive order under which such designation or
identification was made, and
``(iii) the erroneous designations and
identifications result in an overpayment of
income tax for any taxable year by such
organization,
credit or refund (with interest) with respect to such
overpayment shall be made.
``(B) Waiver of limitations.--If the credit or
refund of any overpayment of tax described in
subparagraph (A)(iii) is prevented at any time by the
operation of any law or rule of law (including res
judicata), such credit or refund may nevertheless be
allowed or made if the claim therefor is filed before
the close of the 1-year period beginning on the date of
the last determination described in subparagraph
(A)(ii).
``(7) Notice of Suspensions.--If the tax exemption of any
organization is suspended under this subsection, the Internal
Revenue Service shall update the listings of tax-exempt
organizations and shall publish appropriate notice to taxpayers
of such suspension and of the fact that contributions to such
organization are not deductible during the period of such
suspension.''.
(b) Effective Date.--The amendments made by this section shall
apply to designations made before, on, or after the date of the
enactment of this Act.

SEC. 109. ABOVE-THE-LINE DEDUCTION FOR OVERNIGHT TRAVEL EXPENSES OF
NATIONAL GUARD AND RESERVE MEMBERS.

(a) Deduction Allowed.--Section 162 (relating to certain trade or
business expenses) is amended by redesignating subsection (p) as
subsection (q) and inserting after subsection (o) the following new
subsection:
``(p) Treatment of Expenses of Members of Reserve Component of
Armed Forces of the United States.--For purposes of subsection (a)(2),
in the case of an individual who performs services as a member of a
reserve component of the Armed Forces of the United States at any time
during the taxable year, such individual shall be deemed to be away
from home in the pursuit of a trade or business for any period during
which such individual is away from home in connection with such
service.''.
(b) Deduction Allowed Whether or Not Taxpayer Elects To Itemize.--
Section 62(a)(2) (relating to certain trade and business deductions of
employees) is amended by adding at the end the following new
subparagraph:
``(E) Certain expenses of members of reserve
components of the armed forces of the united states.--
The deductions allowed by section 162 which consist of
expenses, determined at a rate not in excess of the
rates for travel expenses (including per diem in lieu
of subsistence) authorized for employees of agencies
under subchapter I of chapter 57 of title 5, United
States Code, paid or incurred by the taxpayer in
connection with the performance of services by such
taxpayer as a member of a reserve component of the
Armed Forces of the United States for any period during
which such individual is more than 100 miles away from
home in connection with such services.''.
(c) Effective Date.--The amendments made by this section shall
apply to amounts paid or incurred in taxable years beginning after
December 31, 2002.

SEC. 110. TAX RELIEF AND ASSISTANCE FOR FAMILIES OF SPACE SHUTTLE
COLUMBIA HEROES.

(a) Income Tax Relief.--
(1) In general.--Subsection (d) of section 692 (relating to
income taxes of members of Armed Forces and victims of certain
terrorist attacks on death) is amended by adding at the end the
following new paragraph:
``(5) Relief with respect to astronauts.--The provisions of
this subsection shall apply to any astronaut whose death occurs
in the line of duty, except that paragraph (3)(B) shall be
applied by using the date of the death of the astronaut rather
than September 11, 2001.''.
(2) Conforming amendments.--
(A) Section 5(b)(1) is amended by inserting ``,
astronauts,'' after ``Forces''.
(B) Section 6013(f)(2)(B) is amended by inserting
``, astronauts,'' after ``Forces''.
(3) Clerical amendments.--
(A) The heading of section 692 is amended by
inserting ``, astronauts,'' after ``forces''.
(B) The item relating to section 692 in the table
of sections for part II of subchapter J of chapter 1 is
amended by inserting ``, astronauts,'' after
``Forces''.
(4) Effective date.--The amendments made by this subsection
shall apply with respect to any astronaut whose death occurs
after December 31, 2002.
(b) Death Benefit Relief.--
(1) In general.--Subsection (i) of section 101 (relating to
certain death benefits) is amended by adding at the end the
following new paragraph:
``(4) Relief with respect to astronauts.--The provisions of
this subsection shall apply to any astronaut whose death occurs
in the line of duty.''.
(2) Clerical amendment.--The heading for subsection (i) of
section 101 is amended by inserting ``or Astronauts'' after
``Victims''.
(3) Effective date.--The amendments made by this subsection
shall apply to amounts paid after December 31, 2002, with
respect to deaths occurring after such date.
(c) Estate Tax Relief.--
(1) In general.--Section 2201(b) (defining qualified
decedent) is amended by striking ``and'' at the end of
paragraph (1)(B), by striking the period at the end of
paragraph (2) and inserting ``, and'', and by adding at the end
the following new paragraph:
``(3) any astronaut whose death occurs in the line of
duty.''.
(2) Clerical amendments.--
(A) The heading of section 2201 is amended by
inserting ``, deaths of astronauts,'' after ``forces''.
(B) The item relating to section 2201 in the table
of sections for subchapter C of chapter 11 is amended
by inserting ``, deaths of astronauts,'' after
``Forces''.
(3) Effective date.--The amendments made by this subsection
shall apply to estates of decedents dying after December 31,
2002.

TITLE II--OTHER PROVISIONS

SEC. 201. EXTENSION OF INTERNAL REVENUE SERVICE USER FEES.

(a) In General.--Chapter 77 (relating to miscellaneous provisions)
is amended by adding at the end the following new section:

``SEC. 7528. INTERNAL REVENUE SERVICE USER FEES.

``(a) General Rule.--The Secretary shall establish a program
requiring the payment of user fees for--
``(1) requests to the Internal Revenue Service for ruling
letters, opinion letters, and determination letters, and
``(2) other similar requests.
``(b) Program Criteria.--
``(1) In general.--The fees charged under the program
required by subsection (a)--
``(A) shall vary according to categories (or
subcategories) established by the Secretary,
``(B) shall be determined after taking into account
the average time for (and difficulty of) complying with
requests in each category (and subcategory), and
``(C) shall be payable in advance.
``(2) Exemptions, etc.--
``(A) In general.--The Secretary shall provide for
such exemptions (and reduced fees) under such program
as the Secretary determines to be appropriate.
``(B) Exemption for certain requests regarding
pension plans.--The Secretary shall not require payment
of user fees under such program for requests for
determination letters with respect to the qualified
status of a pension benefit plan maintained solely by 1
or more eligible employers or any trust which is part
of the plan. The preceding sentence shall not apply to
any request--
``(i) made after the later of--
``(I) the fifth plan year the
pension benefit plan is in existence,
or
``(II) the end of any remedial
amendment period with respect to the
plan beginning within the first 5 plan
years, or
``(ii) made by the sponsor of any prototype
or similar plan which the sponsor intends to
market to participating employers.
``(C) Definitions and special rules.--For purposes
of subparagraph (B)--
``(i) Pension benefit plan.--The term
`pension benefit plan' means a pension, profit-
sharing, stock bonus, annuity, or employee
stock ownership plan.
``(ii) Eligible employer.--The term
`eligible employer' means an eligible employer
(as defined in section 408(p)(2)(C)(i)(I))
which has at least 1 employee who is not a
highly compensated employee (as defined in
section 414(q)) and is participating in the
plan. The determination of whether an employer
is an eligible employer under subparagraph (B)
shall be made as of the date of the request
described in such subparagraph.
``(iii) Determination of average fees
charged.--For purposes of any determination of
average fees charged, any request to which
subparagraph (B) applies shall not be taken
into account.
``(3) Average fee requirement.--The average fee charged
under the program required by subsection (a) shall not be less
than the amount determined under the following table:

Average
``Category                                                          fee
Employee plan ruling and opinion..............                $250
Exempt organization ruling....................                $350
Employee plan determination...................                $300
Exempt organization determination.............                $275
Chief counsel ruling..........................                $200.
``(c) Termination.--No fee shall be imposed under this section with
respect to requests made after September 30, 2013.''.
(b) Conforming Amendments.--
(1) The table of sections for chapter 77 is amended by
adding at the end the following new item:

``Sec. 7528. Internal Revenue Service
user fees.''.
(2) Section 10511 of the Revenue Act of 1987 is repealed.
(3) Section 620 of the Economic Growth and Tax Relief
Reconciliation Act of 2001 is repealed.
(c) Limitations.--Notwithstanding any other provision of law, any
fees collected pursuant to section 7528 of the Internal Revenue Code of
1986, as added by subsection (a), shall not be expended by the Internal
Revenue Service unless provided by an appropriations Act.
(d) Effective Date.--The amendments made by this section shall
apply to requests made after the date of the enactment of this Act.

SEC. 202. PARTIAL PAYMENT OF TAX LIABILITY IN INSTALLMENT AGREEMENTS.

(a) In General.--
(1) Section 6159(a) (relating to authorization of
agreements) is amended--
(A) by striking ``satisfy liability for payment
of'' and inserting ``make payment on'', and
(B) by inserting ``full or partial'' after
``facilitate''.
(2) Section 6159(c) (relating to Secretary required to
enter into installment agreements in certain cases) is amended
in the matter preceding paragraph (1) by inserting ``full''
before ``payment''.
(b) Requirement To Review Partial Payment Agreements Every Two
Years.--Section 6159 is amended by redesignating subsections (d) and
(e) as subsections (e) and (f), respectively, and inserting after
subsection (c) the following new subsection:
``(d) Secretary Required To Review Installment Agreements for
Partial Collection Every Two Years.--In the case of an agreement
entered into by the Secretary under subsection (a) for partial
collection of a tax liability, the Secretary shall review the agreement
at least once every 2 years.''.
(c) Effective Date.--The amendments made by this section shall
apply to agreements entered into on or after the date of the enactment
of this Act.

SEC. 203. REVISION OF TAX RULES ON EXPATRIATION.

(a) In General.--Subpart A of part II of subchapter N of chapter 1
is amended by inserting after section 877 the following new section:

``SEC. 877A. TAX RESPONSIBILITIES OF EXPATRIATION.

``(a) General Rules.--For purposes of this subtitle--
``(1) Mark to market.--Except as provided in subsections
(d) and (f), all property of a covered expatriate to whom this
section applies shall be treated as sold on the day before the
expatriation date for its fair market value.
``(2) Recognition of gain or loss.--In the case of any sale
under paragraph (1)--
``(A) notwithstanding any other provision of this
title, any gain arising from such sale shall be taken
into account for the taxable year of the sale, and
``(B) any loss arising from such sale shall be
taken into account for the taxable year of the sale to
the extent otherwise provided by this title, except
that section 1091 shall not apply to any such loss.
Proper adjustment shall be made in the amount of any gain or
loss subsequently realized for gain or loss taken into account
under the preceding sentence.
``(3) Exclusion for certain gain.--
``(A) In general.--The amount which, but for this
paragraph, would be includible in the gross income of
any individual by reason of this section shall be
reduced (but not below zero) by $600,000. For purposes
of this paragraph, allocable expatriation gain taken
into account under subsection (f)(2) shall be treated
in the same manner as an amount required to be
includible in gross income.
``(B) Cost-of-living adjustment.--
``(i) In general.--In the case of an
expatriation date occurring in any calendar
year after 2003, the $600,000 amount under
subparagraph (A) shall be increased by an
amount equal to--
``(I) such dollar amount,
multiplied by
``(II) the cost-of-living
adjustment determined under section
1(f)(3) for such calendar year,
determined by substituting `calendar
year 2002' for `calendar year 1992' in
subparagraph (B) thereof.
``(ii) Rounding rules.--If any amount after
adjustment under clause (i) is not a multiple
of $1,000, such amount shall be rounded to the
next lower multiple of $1,000.
``(4) Election to continue to be taxed as united states
citizen.--
``(A) In general.--If a covered expatriate elects
the application of this paragraph--
``(i) this section (other than this
paragraph and subsection (i)) shall not apply
to the expatriate, but
``(ii) in the case of property to which
this section would apply but for such election,
the expatriate shall be subject to tax under
this title in the same manner as if the
individual were a United States citizen.
``(B) Requirements.--Subparagraph (A) shall not
apply to an individual unless the individual--
``(i) provides security for payment of tax
in such form and manner, and in such amount, as
the Secretary may require,
``(ii) consents to the waiver of any right
of the individual under any treaty of the
United States which would preclude assessment
or collection of any tax which may be imposed
by reason of this paragraph, and
``(iii) complies with such other
requirements as the Secretary may prescribe.
``(C) Election.--An election under subparagraph (A)
shall apply to all property to which this section would
apply but for the election and, once made, shall be
irrevocable. Such election shall also apply to property
the basis of which is determined in whole or in part by
reference to the property with respect to which the
election was made.
``(b) Election To Defer Tax.--
``(1) In general.--If the taxpayer elects the application
of this subsection with respect to any property treated as sold
by reason of subsection (a), the payment of the additional tax
attributable to such property shall be postponed until the due
date of the return for the taxable year in which such property
is disposed of (or, in the case of property disposed of in a
transaction in which gain is not recognized in whole or in
part, until such other date as the Secretary may prescribe).
``(2) Determination of tax with respect to property.--For
purposes of paragraph (1), the additional tax attributable to
any property is an amount which bears the same ratio to the
additional tax imposed by this chapter for the taxable year
solely by reason of subsection (a) as the gain taken into
account under subsection (a) with respect to such property
bears to the total gain taken into account under subsection (a)
with respect to all property to which subsection (a) applies.
``(3) Termination of postponement.--No tax may be postponed
under this subsection later than the due date for the return of
tax imposed by this chapter for the taxable year which includes
the date of death of the expatriate (or, if earlier, the time
that the security provided with respect to the property fails
to meet the requirements of paragraph (4), unless the taxpayer
corrects such failure within the time specified by the
Secretary).
``(4) Security.--
``(A) In general.--No election may be made under
paragraph (1) with respect to any property unless
adequate security is provided to the Secretary with
respect to such property.
``(B) Adequate security.--For purposes of
subparagraph (A), security with respect to any property
shall be treated as adequate security if--
``(i) it is a bond in an amount equal to
the deferred tax amount under paragraph (2) for
the property, or
``(ii) the taxpayer otherwise establishes
to the satisfaction of the Secretary that the
security is adequate.
``(5) Waiver of certain rights.--No election may be made
under paragraph (1) unless the taxpayer consents to the waiver
of any right under any treaty of the United States which would
preclude assessment or collection of any tax imposed by reason
of this section.
``(6) Elections.--An election under paragraph (1) shall
only apply to property described in the election and, once
made, is irrevocable. An election may be made under paragraph
(1) with respect to an interest in a trust with respect to
which gain is required to be recognized under subsection
(f)(1).
``(7) Interest.--For purposes of section 6601--
``(A) the last date for the payment of tax shall be
determined without regard to the election under this
subsection, and
``(B) section 6621(a)(2) shall be applied by
substituting `5 percentage points' for `3 percentage
points' in subparagraph (B) thereof.
``(c) Covered Expatriate.--For purposes of this section--
``(1) In general.--Except as provided in paragraph (2), the
term `covered expatriate' means an expatriate.
``(2) Exceptions.--An individual shall not be treated as a
covered expatriate if--
``(A) the individual--
``(i) became at birth a citizen of the
United States and a citizen of another country
and, as of the expatriation date, continues to
be a citizen of, and is taxed as a resident of,
such other country, and
``(ii) has not been a resident of the
United States (as defined in section
7701(b)(1)(A)(ii)) during the 5 taxable years
ending with the taxable year during which the
expatriation date occurs, or
``(B)(i) the individual's relinquishment of United
States citizenship occurs before such individual
attains age 18\1/2\, and
``(ii) the individual has been a resident of the
United States (as so defined) for not more than 5
taxable years before the date of relinquishment.
``(d) Exempt Property; Special Rules for Pension Plans.--
``(1) Exempt property.--This section shall not apply to the
following:
``(A) United states real property interests.--Any
United States real property interest (as defined in
section 897(c)(1)), other than stock of a United States
real property holding corporation which does not, on
the day before the expatriation date, meet the
requirements of section 897(c)(2).
``(B) Specified property.--Any property or interest
in property not described in subparagraph (A) which the
Secretary specifies in regulations.
``(2) Special rules for certain retirement plans.--
``(A) In general.--If a covered expatriate holds on
the day before the expatriation date any interest in a
retirement plan to which this paragraph applies--
``(i) such interest shall not be treated as
sold for purposes of subsection (a)(1), but
``(ii) an amount equal to the present value
of the expatriate's nonforfeitable accrued
benefit shall be treated as having been
received by such individual on such date as a
distribution under the plan.
``(B) Treatment of subsequent distributions.--In
the case of any distribution on or after the
expatriation date to or on behalf of the covered
expatriate from a plan from which the expatriate was
treated as receiving a distribution under subparagraph
(A), the amount otherwise includible in gross income by
reason of the subsequent distribution shall be reduced
by the excess of the amount includible in gross income
under subparagraph (A) over any portion of such amount
to which this subparagraph previously applied.
``(C) Treatment of subsequent distributions by
plan.--For purposes of this title, a retirement plan to
which this paragraph applies, and any person acting on
the plan's behalf, shall treat any subsequent
distribution described in subparagraph (B) in the same
manner as such distribution would be treated without
regard to this paragraph.
``(D) Applicable plans.--This paragraph shall apply
to--
``(i) any qualified retirement plan (as
defined in section 4974(c)),
``(ii) an eligible deferred compensation
plan (as defined in section 457(b)) of an
eligible employer described in section
457(e)(1)(A), and
``(iii) to the extent provided in
regulations, any foreign pension plan or
similar retirement arrangements or programs.
``(e) Definitions.--For purposes of this section--
``(1) Expatriate.--The term `expatriate' means--
``(A) any United States citizen who relinquishes
citizenship, and
``(B) any long-term resident of the United States
who--
``(i) ceases to be a lawful permanent
resident of the United States (within the
meaning of section 7701(b)(6)), or
``(ii) commences to be treated as a
resident of a foreign country under the
provisions of a tax treaty between the United
States and the foreign country and who does not
waive the benefits of such treaty applicable to
residents of the foreign country.
``(2) Expatriation date.--The term `expatriation date'
means--
``(A) the date an individual relinquishes United
States citizenship, or
``(B) in the case of a long-term resident of the
United States, the date of the event described in
clause (i) or (ii) of paragraph (1)(B).
``(3) Relinquishment of citizenship.--A citizen shall be
treated as relinquishing United States citizenship on the
earliest of--
``(A) the date the individual renounces such
individual's United States nationality before a
diplomatic or consular officer of the United States
pursuant to paragraph (5) of section 349(a) of the
Immigration and Nationality Act (8 U.S.C. 1481(a)(5)),
``(B) the date the individual furnishes to the
United States Department of State a signed statement of
voluntary relinquishment of United States nationality
confirming the performance of an act of expatriation
specified in paragraph (1), (2), (3), or (4) of section
349(a) of the Immigration and Nationality Act (8 U.S.C.
1481(a)(1)-(4)),
``(C) the date the United States Department of
State issues to the individual a certificate of loss of
nationality, or
``(D) the date a court of the United States cancels
a naturalized citizen's certificate of naturalization.
Subparagraph (A) or (B) shall not apply to any individual
unless the renunciation or voluntary relinquishment is
subsequently approved by the issuance to the individual of a
certificate of loss of nationality by the United States
Department of State.
``(4) Long-term resident.--The term `long-term resident'
has the meaning given to such term by section 877(e)(2).
``(f) Special Rules Applicable to Beneficiaries' Interests in
Trust.--
``(1) In general.--Except as provided in paragraph (2), if
an individual is determined under paragraph (3) to hold an
interest in a trust on the day before the expatriation date--
``(A) the individual shall not be treated as having
sold such interest,
``(B) such interest shall be treated as a separate
share in the trust, and
``(C)(i) such separate share shall be treated as a
separate trust consisting of the assets allocable to
such share,
``(ii) the separate trust shall be treated as
having sold its assets on the day before the
expatriation date for their fair market value and as
having distributed all of its assets to the individual
as of such time, and
``(iii) the individual shall be treated as having
recontributed the assets to the separate trust.
Subsection (a)(2) shall apply to any income, gain, or loss of
the individual arising from a distribution described in
subparagraph (C)(ii). In determining the amount of such
distribution, proper adjustments shall be made for liabilities
of the trust allocable to an individual's share in the trust.
``(2) Special rules for interests in qualified trusts.--
``(A) In general.--If the trust interest described
in paragraph (1) is an interest in a qualified trust--
``(i) paragraph (1) and subsection (a)
shall not apply, and
``(ii) in addition to any other tax imposed
by this title, there is hereby imposed on each
distribution with respect to such interest a
tax in the amount determined under subparagraph
(B).
``(B) Amount of tax.--The amount of tax under
subparagraph (A)(ii) shall be equal to the lesser of--
``(i) the highest rate of tax imposed by
section 1(e) for the taxable year which
includes the day before the expatriation date,
multiplied by the amount of the distribution,
or
``(ii) the balance in the deferred tax
account immediately before the distribution
determined without regard to any increases
under subparagraph (C)(ii) after the 30th day
preceding the distribution.
``(C) Deferred tax account.--For purposes of
subparagraph (B)(ii)--
``(i) Opening balance.--The opening balance
in a deferred tax account with respect to any
trust interest is an amount equal to the tax
which would have been imposed on the allocable
expatriation gain with respect to the trust
interest if such gain had been included in
gross income under subsection (a).
``(ii) Increase for interest.--The balance
in the deferred tax account shall be increased
by the amount of interest determined (on the
balance in the account at the time the interest
accrues), for periods after the 90th day after
the expatriation date, by using the rates and
method applicable under section 6621 for
underpayments of tax for such periods, except
that section 6621(a)(2) shall be applied by
substituting `5 percentage points' for `3
percentage points' in subparagraph (B) thereof.
``(iii) Decrease for taxes previously
paid.--The balance in the tax deferred account
shall be reduced--
``(I) by the amount of taxes
imposed by subparagraph (A) on any
distribution to the person holding the
trust interest, and
``(II) in the case of a person
holding a nonvested interest, to the
extent provided in regulations, by the
amount of taxes imposed by subparagraph
(A) on distributions from the trust
with respect to nonvested interests not
held by such person.
``(D) Allocable expatriation gain.--For purposes of
this paragraph, the allocable expatriation gain with
respect to any beneficiary's interest in a trust is the
amount of gain which would be allocable to such
beneficiary's vested and nonvested interests in the
trust if the beneficiary held directly all assets
allocable to such interests.
``(E) Tax deducted and withheld.--
``(i) In general.--The tax imposed by
subparagraph (A)(ii) shall be deducted and
withheld by the trustees from the distribution
to which it relates.
``(ii) Exception where failure to waive
treaty rights.--If an amount may not be
deducted and withheld under clause (i) by
reason of the distributee failing to waive any
treaty right with respect to such
distribution--
``(I) the tax imposed by
subparagraph (A)(ii) shall be imposed
on the trust and each trustee shall be
personally liable for the amount of
such tax, and
``(II) any other beneficiary of the
trust shall be entitled to recover from
the distributee the amount of such tax
imposed on the other beneficiary.
``(F) Disposition.--If a trust ceases to be a
qualified trust at any time, a covered expatriate
disposes of an interest in a qualified trust, or a
covered expatriate holding an interest in a qualified
trust dies, then, in lieu of the tax imposed by
subparagraph (A)(ii), there is hereby imposed a tax
equal to the lesser of--
``(i) the tax determined under paragraph
(1) as if the day before the expatriation date
were the date of such cessation, disposition,
or death, whichever is applicable, or
``(ii) the balance in the tax deferred
account immediately before such date.
Such tax shall be imposed on the trust and each trustee
shall be personally liable for the amount of such tax
and any other beneficiary of the trust shall be
entitled to recover from the covered expatriate or the
estate the amount of such tax imposed on the other
beneficiary.
``(G) Definitions and special rules.--For purposes
of this paragraph--
``(i) Qualified trust.--The term `qualified
trust' means a trust which is described in
section 7701(a)(30)(E).
``(ii) Vested interest.--The term `vested
interest' means any interest which, as of the
day before the expatriation date, is vested in
the beneficiary.
``(iii) Nonvested interest.--The term
`nonvested interest' means, with respect to any
beneficiary, any interest in a trust which is
not a vested interest. Such interest shall be
determined by assuming the maximum exercise of
discretion in favor of the beneficiary and the
occurrence of all contingencies in favor of the
beneficiary.
``(iv) Adjustments.--The Secretary may
provide for such adjustments to the bases of
assets in a trust or a deferred tax account,
and the timing of such adjustments, in order to
ensure that gain is taxed only once.
``(v) Coordination with retirement plan
rules.--This subsection shall not apply to an
interest in a trust which is part of a
retirement plan to which subsection (d)(2)
applies.
``(3) Determination of beneficiaries' interest in trust.--
``(A) Determinations under paragraph (1).--For
purposes of paragraph (1), a beneficiary's interest in
a trust shall be based upon all relevant facts and
circumstances, including the terms of the trust
instrument and any letter of wishes or similar
document, historical patterns of trust distributions,
and the existence of and functions performed by a trust
protector or any similar adviser.
``(B) Other determinations.--For purposes of this
section--
``(i) Constructive ownership.--If a
beneficiary of a trust is a corporation,
partnership, trust, or estate, the
shareholders, partners, or beneficiaries shall
be deemed to be the trust beneficiaries for
purposes of this section.
``(ii) Taxpayer return position.--A
taxpayer shall clearly indicate on its income
tax return--
``(I) the methodology used to
determine that taxpayer's trust
interest under this section, and
``(II) if the taxpayer knows (or
has reason to know) that any other
beneficiary of such trust is using a
different methodology to determine such
beneficiary's trust interest under this
section.
``(g) Termination of Deferrals, etc.--In the case of any covered
expatriate, notwithstanding any other provision of this title--
``(1) any period during which recognition of income or gain
is deferred shall terminate on the day before the expatriation
date, and
``(2) any extension of time for payment of tax shall cease
to apply on the day before the expatriation date and the unpaid
portion of such tax shall be due and payable at the time and in
the manner prescribed by the Secretary.
``(h) Imposition of Tentative Tax.--
``(1) In general.--If an individual is required to include
any amount in gross income under subsection (a) for any taxable
year, there is hereby imposed, immediately before the
expatriation date, a tax in an amount equal to the amount of
tax which would be imposed if the taxable year were a short
taxable year ending on the expatriation date.
``(2) Due date.--The due date for any tax imposed by
paragraph (1) shall be the 90th day after the expatriation
date.
``(3) Treatment of tax.--Any tax paid under paragraph (1)
shall be treated as a payment of the tax imposed by this
chapter for the taxable year to which subsection (a) applies.
``(4) Deferral of tax.--The provisions of subsection (b)
shall apply to the tax imposed by this subsection to the extent
attributable to gain includible in gross income by reason of
this section.
``(i) Special Liens for Deferred Tax Amounts.--
``(1) Imposition of lien.--
``(A) In general.--If a covered expatriate makes an
election under subsection (a)(4) or (b) which results
in the deferral of any tax imposed by reason of
subsection (a), the deferred amount (including any
interest, additional amount, addition to tax,
assessable penalty, and costs attributable to the
deferred amount) shall be a lien in favor of the United
States on all property of the expatriate located in the
United States (without regard to whether this section
applies to the property).
``(B) Deferred amount.--For purposes of this
subsection, the deferred amount is the amount of the
increase in the covered expatriate's income tax which,
but for the election under subsection (a)(4) or (b),
would have occurred by reason of this section for the
taxable year including the expatriation date.
``(2) Period of lien.--The lien imposed by this subsection
shall arise on the expatriation date and continue until--
``(A) the liability for tax by reason of this
section is satisfied or has become unenforceable by
reason of lapse of time, or
``(B) it is established to the satisfaction of the
Secretary that no further tax liability may arise by
reason of this section.
``(3) Certain rules apply.--The rules set forth in
paragraphs (1), (3), and (4) of section 6324A(d) shall apply
with respect to the lien imposed by this subsection as if it
were a lien imposed by section 6324A.
``(j) Regulations.--The Secretary shall prescribe such regulations
as may be necessary or appropriate to carry out the purposes of this
section.''.
(b) Inclusion in Income of Gifts and Bequests Received by United
States Citizens and Residents From Expatriates.--Section 102 (relating
to gifts, etc. not included in gross income) is amended by adding at
the end the following new subsection:
``(d) Gifts and Inheritances From Covered Expatriates.--
``(1) In general.--Subsection (a) shall not exclude from
gross income the value of any property acquired by gift,
bequest, devise, or inheritance from a covered expatriate after
the expatriation date. For purposes of this subsection, any
term used in this subsection which is also used in section 877A
shall have the same meaning as when used in section 877A.
``(2) Exceptions for transfers otherwise subject to estate
or gift tax.--Paragraph (1) shall not apply to any property if
either--
``(A) the gift, bequest, devise, or inheritance
is--
``(i) shown on a timely filed return of tax
imposed by chapter 12 as a taxable gift by the
covered expatriate, or
``(ii) included in the gross estate of the
covered expatriate for purposes of chapter 11
and shown on a timely filed return of tax
imposed by chapter 11 of the estate of the
covered expatriate, or
``(B) no such return was timely filed but no such
return would have been required to be filed even if the
covered expatriate were a citizen or long-term resident
of the United States.''.
(c) Definition of Termination of United States Citizenship.--
Section 7701(a) is amended by adding at the end the following new
paragraph:
``(48) Termination of united states citizenship.--
``(A) In general.--An individual shall not cease to
be treated as a United States citizen before the date
on which the individual's citizenship is treated as
relinquished under section 877A(e)(3).
``(B) Dual citizens.--Under regulations prescribed
by the Secretary, subparagraph (A) shall not apply to
an individual who became at birth a citizen of the
United States and a citizen of another country.''.
(d) Ineligibility for Visa or Admission to United States.--
(1) In general.--Section 212(a)(10)(E) of the Immigration
and Nationality Act (8 U.S.C. 1182(a)(10)(E)) is amended to
read as follows:
``(E) Former citizens not in compliance with
expatriation revenue provisions.--Any alien who is a
former citizen of the United States who relinquishes
United States citizenship (within the meaning of
section 877A(e)(3) of the Internal Revenue Code of
1986) and who is not in compliance with section 877A of
such Code (relating to expatriation).''.
(2) Availability of information.--
(A) In general.--Section 6103(l) (relating to
disclosure of returns and return information for
purposes other than tax administration) is amended by
adding at the end the following new paragraph:
``(19) Disclosure to deny visa or admission to certain
expatriates.--Upon written request of the Attorney General or
the Attorney General's delegate, the Secretary shall disclose
whether an individual is in compliance with section 877A (and
if not in compliance, any items of noncompliance) to officers
and employees of the Federal agency responsible for
administering section 212(a)(10)(E) of the Immigration and
Nationality Act solely for the purpose of, and to the extent
necessary in, administering such section 212(a)(10)(E).''.
(B) Safeguards.--
(i) Technical amendments.--Paragraph (4) of
section 6103(p) of the Internal Revenue Code of
1986, as amended by section 202(b)(2)(B) of the
Trade Act of 2002 (Public Law 107-210; 116
Stat. 961), is amended by striking ``or (17)''
after ``any other person described in
subsection (l)(16)'' each place it appears and
inserting ``or (18)''.
(ii) Conforming amendments.--Section
6103(p)(4) (relating to safeguards), as amended
by clause (i), is amended by striking ``or
(18)'' after ``any other person described in
subsection (l)(16)'' each place it appears and
inserting ``(18), or (19)''.
(3) Effective dates.--
(A) In general.--Except as provided in subparagraph
(B), the amendments made by this subsection shall apply
to individuals who relinquish United States citizenship
on or after the date of the enactment of this Act.
(B) Technical amendments.--The amendments made by
paragraph (2)(B)(i) shall take effect as if included in
the amendments made by section 202(b)(2)(B) of the
Trade Act of 2002 (Public Law 107-210; 116 Stat. 961).
(e) Conforming Amendments.--
(1) Section 877 is amended by adding at the end the
following new subsection:
``(g) Application.--This section shall not apply to an expatriate
(as defined in section 877A(e)) whose expatriation date (as so defined)
occurs on or after February 5, 2003.''.
(2) Section 2107 is amended by adding at the end the
following new subsection:
``(f) Application.--This section shall not apply to any expatriate
subject to section 877A.''.
(3) Section 2501(a)(3) is amended by adding at the end the
following new subparagraph:
``(F) Application.--This paragraph shall not apply
to any expatriate subject to section 877A.''.
(4)(A) Paragraph (1) of section 6039G(d) is amended by
inserting ``or 877A'' after ``section 877''.
(B) The second sentence of section 6039G(e) is amended by
inserting ``or who relinquishes United States citizenship
(within the meaning of section 877A(e)(3))'' after ``877(a))''.
(C) Section 6039G(f) is amended by inserting ``or
877A(e)(2)(B)'' after ``877(e)(1)''.
(f) Clerical Amendment.--The table of sections for subpart A of
part II of subchapter N of chapter 1 is amended by inserting after the
item relating to section 877 the following new item:

``Sec. 877A. Tax responsibilities of
expatriation.''.
(g) Effective Date.--
(1) In general.--Except as provided in this subsection, the
amendments made by this section shall apply to expatriates
(within the meaning of section 877A(e) of the Internal Revenue
Code of 1986, as added by this section) whose expatriation date
(as so defined) occurs on or after February 5, 2003.
(2) Gifts and bequests.--Section 102(d) of the Internal
Revenue Code of 1986 (as added by subsection (b)) shall apply
to gifts and bequests received on or after February 5, 2003,
from an individual or the estate of an individual whose
expatriation date (as so defined) occurs after such date.
(3) Due date for tentative tax.--The due date under section
877A(h)(2) of the Internal Revenue Code of 1986, as added by
this section, shall in no event occur before the 90th day after
the date of the enactment of this Act.

Attest:

Secretary.
108th CONGRESS

1st Session

H. R. 1307

_______________________________________________________________________

AMENDMENT