H.R. 2168House108th Congress (2003-2005)In Committee
National Guard and Reserves Reform Act for the 21st Century
Sponsored by 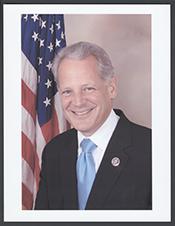 Rep. Steve Israel (D-NY)
Introduced May 20, 2003
Legislative Activity
Stay on top of the latest movement without scrolling through every action
HouseCommittee
Latest Action
Referred to the Subcommittee on Total Force.
July 18, 2003
View full timeline
HouseIntro Referral
Introduced in House
May 20, 2003
HouseIntro Referral
Referred to the Committee on Armed Services, and in addition to the Committee on Ways and Means, for a period to be subsequently determined by the Speaker, in each case for consideration of such provisions as fall within the jurisdiction of the committee concerned.
May 20, 2003
HouseCommittee
Referred to the Subcommittee on Total Force.
July 18, 2003
Bill Text
Latest available legislative text
Introduced in HouseIssued May 20, 2003
        [Congressional Bills 108th Congress]
[From the U.S. Government Publishing Office]
[H.R. 2168 Introduced in House (IH)]

108th CONGRESS
1st Session
H. R. 2168

To amend title 10, United States Code, to revise the age and service
requirements for eligibility to receive retired pay for non-regular
service; to provide TRICARE eligibility for members of the Selected
Reserve of the Ready Reserve and their families; to amend the Internal
Revenue Code of 1986 to allow employers a credit against income tax
with respect to employees who participate in the military reserve
components and to allow a comparable credit for participating reserve
component self-employed individuals, and for other purposes.

_______________________________________________________________________

IN THE HOUSE OF REPRESENTATIVES

May 20, 2003

Mr. Israel introduced the following bill; which was referred to the
Committee on Armed Services, and in addition to the Committee on Ways
and Means, for a period to be subsequently determined by the Speaker,
in each case for consideration of such provisions as fall within the
jurisdiction of the committee concerned

_______________________________________________________________________

A BILL

To amend title 10, United States Code, to revise the age and service
requirements for eligibility to receive retired pay for non-regular
service; to provide TRICARE eligibility for members of the Selected
Reserve of the Ready Reserve and their families; to amend the Internal
Revenue Code of 1986 to allow employers a credit against income tax
with respect to employees who participate in the military reserve
components and to allow a comparable credit for participating reserve
component self-employed individuals, and for other purposes.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE.

This Act may be cited as the ``National Guard and Reserves Reform
Act for the 21st Century''.

SEC. 2. ELIGIBILITY FOR RETIRED PAY FOR NON-REGULAR SERVICE.

(a) Age and Service Requirements.--Subsection (a) of section 12731
of title 10, United States Code, is amended to read as follows:
``(a)(1) Except as provided in subsection (c), a person is
entitled, upon application, to retired pay computed under section 12739
of this title, if the person--
``(A) satisfies one of the combinations of requirements for
minimum age and minimum number of years of service (computed
under section 12732 of this title) that are specified in the
table in paragraph (2);
``(B) performed the last six years of qualifying service
while a member of any category named in section 12732(a)(1) of
this title, but not while a member of a regular component, the
Fleet Reserve, or the Fleet Marine Corps Reserve, except that
in the case of a person who completed 20 years of service
computed under section 12732 of this title before October 5,
1994, the number of years of qualifying service under this
subparagraph shall be eight; and
``(C) is not entitled, under any other provision of law, to
retired pay from an armed force or retainer pay as a member of
the Fleet Reserve or the Fleet Marine Corps Reserve.
``(2) The combinations of minimum age and minimum years of service
required of a person under subparagraph (A) of paragraph (1) for
entitlement to retired pay as provided in such paragraph are as
follows:

``Age, in years, is                        The minimum years of service
at least:                                   required for that age is:
53......................................................        34
54......................................................        32
55......................................................        30
56......................................................        28
57......................................................        26
58......................................................        24
59......................................................        22
60......................................................     20.''.
(b) 20-Year Letter.--Subsection (d) of such section is amended by
striking ``the years of service required for eligibility for retired
pay under this chapter'' in the first sentence and inserting ``20 years
of service computed under section 12732 of this title.''.
(c) Effective Date.--This section and the amendments made by this
subsection (a) shall take effect on the first day of the first month
beginning on or after the date of the enactment of this Act and shall
apply with respect to retired pay payable for that month and subsequent
months.

SEC. 2. EXPANDED ELIGIBILITY OF READY RESERVISTS FOR TRICARE.

(a) Eligibility.--Chapter 55 of title 10, United States Code, is
amended by inserting after section 1097b the following new section:
``Sec. 1097c. TRICARE program: Reserves not on active duty
``(a) Eligibility.--A member of the Selected Reserve of the Ready
Reserve of the armed forces not otherwise eligible for enrollment in
the TRICARE program under this chapter for the same benefits as a
member of the armed forces eligible under section 1074(a) of this title
may enroll for self or for self and family for the same benefits under
this section.
``(b) Premiums.--(1) An enlisted member of the armed forces
enrolled in the TRICARE program under this section shall pay an annual
premium of $330 for self only coverage and $560 for self and family
coverage for which enrolled under this section.
``(2) An officer of the armed forces enrolled in the TRICARE
program under this section shall pay an annual premium of $380 for self
only coverage and $610 for self and family coverage for which enrolled
under this section.''.
(b) Clerical Amendment.--The table of sections at the beginning of
such chapter is amended by inserting after the item relating to section
1097b the following new item:

``1097c. Section 101 head.''.

SEC. 3. CREDIT FOR EMPLOYMENT OF RESERVE COMPONENT PERSONNEL.

(a) In General.--Subpart D of part IV of subchapter A of chapter 1
of the Internal Revenue Code of 1986 (relating to business-related
credits) is amended by adding at the end the following new section:

``SEC. 45G. RESERVE COMPONENT EMPLOYMENT CREDIT.

``(a) General Rule.--For purposes of section 38, the reserve
component employment credit determined under this section is an amount
equal to the sum of--
``(1) the employment credit with respect to all qualified
employees of the taxpayer, plus
``(2) the self-employment credit of a qualified self-
employed taxpayer.
``(b) Employment Credit.--For purposes of this section--
``(1) In general.--The employment credit with respect to a
qualified employee of the taxpayer for any taxable year is
equal to the excess, if any, of--
``(A) the qualified employee's average daily
qualified compensation for the taxable year, over
``(B) the average daily military pay and allowances
received by the qualified employee during the taxable
year,
while participating in qualified reserve component duty to the
exclusion of the qualified employee's normal employment duties
for the number of days the qualified employee participates in
qualified reserve component duty during the taxable year,
including time spent in a travel status. The employment credit,
with respect to all qualified employees, is equal to the sum of
the employment credits for each qualified employee under this
subsection.
``(2) Average daily qualified compensation and average
daily military pay and allowances.--As used with respect to a
qualified employee--
``(A) the term `average daily qualified
compensation' means the qualified compensation of the
qualified employee for the taxable year divided by the
difference between--
``(i) 365, and
``(ii) the number of days the qualified
employee participates in qualified reserve
component duty during the taxable year,
including time spent in a travel status, and
``(B) the term `average daily military pay and
allowances' means--
``(i) the amount paid to the qualified
employee during the taxable year as military
pay and allowances on account of the qualified
employee's participation in qualified reserve
component duty, divided by
``(ii) the total number of days the
qualified employee participates in qualified
reserve component duty, including time spent in
travel status.
``(3) Qualified compensation.--When used with respect to
the compensation paid or that would have been paid to a
qualified employee for any period during which the qualified
employee participates in qualified reserve component duty, the
term `qualified compensation' means--
``(A) compensation which is normally contingent on
the qualified employee's presence for work and which
would be deductible from the taxpayer's gross income
under section 162(a)(1) if the qualified employee were
present and receiving such compensation,
``(B) compensation which is not characterized by
the taxpayer as vacation or holiday pay, or as sick
leave or pay, or as any other form of pay for a
nonspecific leave of absence, and with respect to which
the number of days the qualified employee participates
in qualified reserve component duty does not result in
any reduction in the amount of vacation time, sick
leave, or other nonspecific leave previously credited
to or earned by the qualified employee, and
``(C) group health plan costs (if any) with respect
to the qualified employee.
``(4) Qualified employee.--The term `qualified employee'
means a person who--
``(A) has been an employee of the taxpayer for the
21-day period immediately preceding the period during
which the employee participates in qualified reserve
component duty, and
``(B) is a member of the Ready Reserve of a reserve
component of an Armed Force of the United States as
defined in sections 10142 and 10101 of title 10, United
States Code.
``(c) Self-Employment Credit.--
``(1) In general.--The self-employment credit of a
qualified self-employed taxpayer for any taxable year is equal
to the excess, if any, of--
``(A) the self-employed taxpayer's average daily
self-employment income for the taxable year over
``(B) the average daily military pay and allowances
received by the taxpayer during the taxable year, while
participating in qualified reserve component duty to
the exclusion of the taxpayer's normal self-employment
duties for the number of days the taxpayer participates
in qualified reserve component duty during the taxable
year, including time spent in a travel status.
``(2) Average daily self-employment income and average
daily military pay and allowances.--As used with respect to a
self-employed taxpayer--
``(A) the term `average daily self-employment
income' means the self-employment income (as defined in
section 1402) of the taxpayer for the taxable year plus
the amount paid for insurance which constitutes medical
care for the taxpayer for such year (within the meaning
of section 162(l)) divided by the difference between--
``(i) 365, and
``(ii) the number of days the taxpayer
participates in qualified reserve component
duty during the taxable year, including time
spent in a travel status, and
``(B) the term `average daily military pay and
allowances' means--
``(i) the amount paid to the taxpayer
during the taxable year as military pay and
allowances on account of the taxpayer's
participation in qualified reserve component
duty, divided by
``(ii) the total number of days the
taxpayer participates in qualified reserve
component duty, including time spent in travel
status.
``(3) Qualified self-employed taxpayer.--The term
`qualified self-employed taxpayer' means a taxpayer who--
``(A) has net earnings from self-employment (as
defined in section 1402) for the taxable year, and
``(B) is a member of the Ready Reserve of a reserve
component of an Armed Force of the United States.
``(d) Credit in Addition to Deduction.--The employment credit
provided in this section is in addition to any deduction otherwise
allowable with respect to compensation actually paid to a qualified
employee during any period the qualified employee participates in
qualified reserve component duty to the exclusion of normal employment
duties.
``(e) Limitations.--
``(1) Maximum credit.--
``(A) In general.--The credit allowed by subsection
(a) for the taxable year shall not exceed $25,000 with
respect to each qualified employee.
``(B) Controlled groups.--For purposes of applying
the limitation in subparagraph (A)--
``(i) all members of a controlled group
shall be treated as one taxpayer, and
``(ii) such limitations shall be allocated
among the members of such group in such manner
as the Secretary may prescribe.
For purposes of this subparagraph, all persons treated
as a single employer under subsection (a) or (b) of
section 52 or subsection (m) or (o) of section 414
shall be treated as members of a controlled group.
``(2) Disallowance for failure to comply with employment or
reemployment rights of members of the reserve components of the
armed forces of the united states.--No credit shall be allowed
under subsection (a) to a taxpayer for--
``(A) any taxable year in which the taxpayer is
under a final order, judgment, or other process issued
or required by a district court of the United States
under section 4323 of title 38 of the United States
Code with respect to a violation of chapter 43 of such
title, and
``(B) the 2 succeeding taxable years.
``(3) Disallowance with respect to persons ordered to
active duty for training.--No credit shall be allowed under
subsection (a) to a taxpayer with respect to any period for
which the person on whose behalf the credit would otherwise be
allowable is called or ordered to active duty for any of the
following types of duty:
``(A) active duty for training under any provision
of title 10, United States Code,
``(B) training at encampments, maneuvers, outdoor
target practice, or other exercises under chapter 5 of
title 32, United States Code, or
``(C) full-time National Guard duty, as defined in
section 101(d)(5) of title 10, United States Code.
``(f) General Definitions and Special Rules.--
``(1) Military pay and allowances.--The term `military pay'
means pay as that term is defined in section 101(21) of title
37, United States Code, and the term `allowances' means the
allowances payable to a member of the Armed Forces of the
United States under chapter 7 of that title.
``(2) Qualified reserve component duty.--The term
`qualified reserve component duty' includes only active duty
performed, as designated in the reservist's military orders, in
support of a contingency operation as defined in section
101(a)(13) of title 10, United States Code.
``(3) Normal employment and self-employment duties.--A
person shall be deemed to be participating in qualified reserve
component duty to the exclusion of normal employment or self-
employment duties if the person does not engage in or undertake
any substantial activity related to the person's normal
employment or self-employment duties while participating in
qualified reserve component duty unless in an authorized leave
status or other authorized absence from military duties. If a
person engages in or undertakes any substantial activity
related to the person's normal employment or self-employment
duties at any time while participating in a period of qualified
reserve component duty, unless during a period of authorized
leave or other authorized absence from military duties, the
person shall be deemed to have engaged in or undertaken such
activity for the entire period of qualified reserve component
duty.
``(4) Certain rules to apply.--Rules similar to the rules
of subsections (c), (d), and (e) of section 52 shall apply for
purposes of this section.''.
(b) Conforming Amendment.--Section 38(b) of such Code (relating to
general business credit) is amended--
(1) by striking ``plus'' at the end of paragraph (14),
(2) by striking the period at the end of paragraph (15) and
inserting ``, plus'', and
(3) by adding at the end the following new paragraph:
``(16) the reserve component employment credit determined
under section 45G(a).''.
(c) Clerical Amendment.--The table of sections for subpart D of
part IV of subchapter A of chapter 1 of such Code is amended by
inserting after the item relating to section 45F the following new
item:

``Sec. 45G. Reserve component employment
credit.''.
(d) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2002.
<all>