Health Savings and Affordability Act of 2003
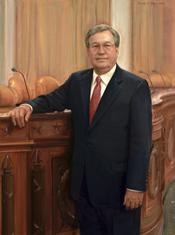 Rep. William M. Thomas (R-CA)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Pursuant to the provisions of H. Res. 299, H.R. 2596 is laid on the table.
June 27, 2003 • 2:41 AM
View full timeline
Introduced in House
June 25, 2003
Referred to the House Committee on Ways and Means.
June 25, 2003
Rules Committee Resolution H. Res. 299 Reported to House. Rule provides for consideration of H.R. 1 and H.R. 2596 with 3 hours of general debate. Previous question shall be considered as ordered without intervening motions except motion to recommit with or without instructions. Measure will be considered read. A specified amendment is in order. Amendment in the nature of a substitute by, and if offered by, Mr. Rangel is debatable for one hour. H.R. 2596 shall be considered in the House and after final adoption, shall be appended to the text of H.R. 1. H.R. 2596 will then be laid on the table. Concurrent resolutions providing for adjournment of the House and Senate in July shall be in order for consideration. Finally, the Committee on Appropriations shall have until midnight on Thursday, July 3, 2003 to file a report making appropriations for
June 26, 2003 • 6:20 AM
Rule H. Res. 299 passed House.
June 26, 2003 • 2:42 PM
Considered under the provisions of rule H. Res. 299. (consideration: CR H5952-6006)
June 26, 2003 • 5:13 PM
Rule provides for consideration of H.R. 1 and H.R. 2596 with 3 hours of general debate. Previous question shall be considered as ordered without intervening motions except motion to recommit with or without instructions. Measure will be considered read. A specified amendment is in order. Amendment in the nature of a substitute by, and if offered by, Mr. Rangel is debatable for one hour. H.R. 2596 shall be considered in the House and after final adoption, shall be appended to the text of H.R. 1. H.R. 2596 will then be laid on the table. Concurrent resolutions providing for adjournment of the House and Senate in July shall be in order for consideration. Finally, the Committee on Appropriations shall have until midnight on Thursday, July 3, 2003 to file a report making appropriations for
June 26, 2003 • 5:13 PM
DEBATE - The House proceeded with one hour of debate on H.R. 2596.
June 26, 2003 • 5:13 PM
The previous question was ordered pursuant to the rule.
June 26, 2003 • 6:23 PM
Passed/agreed to in House: On passage Passed by the Yeas and Nays: 237 - 191 (Roll no. 328).(text: CR H5992-5997)
June 26, 2003 • 6:53 PM
On passage Passed by the Yeas and Nays: 237 - 191 (Roll no. 328). (text: CR H5992-5997)
June 26, 2003 • 6:53 PM
Motion to reconsider laid on the table Agreed to without objection.
June 26, 2003 • 6:53 PM
Pursuant to the provisions of H. Res. 299, the text of H.R. 2596 was appended to the text of H.R. 1 as new matter.
June 27, 2003 • 2:32 AM
Pursuant to the provisions of H. Res. 299, H.R. 2596 is laid on the table.
June 27, 2003 • 2:41 AM
Voting History
1 vote recorded • Roll call available
Floor Debate
24 membersWhat members said about H.R. 2596 on the floor

 +19
Floor Debate
24 membersWhat members said about H.R. 2596 on the floor
Mr. Speaker, I thank the gentlewoman from Ohio for yielding me the customary 30 minutes, and I yield myself such time as I may consume. (Ms. SLAUGHTER asked and was given permission to revise and…
Mr. Speaker, due to family reasons, I was unable to vote on rollcall No. 227: H. Res. 159. Had I been present, I would have voted ``yes.'' Mr. Speaker, due to family reasons, I was unable vote on…
Mr. Speaker, by direction of the Committee on Rules, I call up House Resolution 299 and ask for its immediate consideration. Mr. Speaker, for purposes of debate only, I yield the customary 30 minutes…
Mr. Speaker, I reserve the balance of my time. Mr. Speaker, I yield myself such time as I may consume. Mr. Speaker, I just heard the ranking member say this is not a health bill, that this is a tax…
Mr. Speaker, I yield myself 3 minutes. (Mr. STARK asked and was given permission to revise and extend his remarks.) Mr. Speaker, I will start with an apology to all my Republican colleagues. For, oh,…
Show 8 more
Mr. Speaker, I want to commend all those that have worked so hard on probably the most important issue that most of us will vote on in our career. There is very few times that you are going to have a…

Mr. Speaker, the first revision I would like to make to my very good friend and the role that I play was leading us through this morning as we did, in fact, as has been pointed out, beginning late at…
Mr. Speaker, I rise today against this rule. Members should have an opportunity to vote on an enhanced version of the bipartisan Senate bill. That is the Blue Dog prescription drug benefit bill.…
Mr. Speaker, the hour is late. We have had a lot of rhetoric. We have had a lot of flailing of arms and pointing fingers across the aisle. It is time for us to come to a reasoned decision. It is time…
Mr. Speaker, I rise in opposition to this bill which fails to provide women with the affordable and reliable Medicare prescription drug coverage that they desperately need and deserve. Mr. Speaker, I…
Mr. Speaker, I offer a motion to instruct. Mr. Speaker, I yield myself such time as I may consume. I rise today to offer a motion to instruct conferees on H.R. 1, the Medicare Prescription Drug and…

Mr. Speaker, I thank the gentleman for yielding me the time. Let us take a look at the fiscal format of this country as we begin the debate on this measure this afternoon. We have seen revenue…
Mr. Speaker, pursuant to House Resolution 299, I call up the bill (H.R. 2596) to amend the Internal Revenue Code of 1986 to allow a deduction to individuals for amounts contributed to health savings…
Show 11 more

Mr. Speaker, the distinguished majority leader who just spoke said something that I agree with. He said that this issue that we are voting on tonight is probably one of the most important issues we…

Mr. Speaker, once again Republicans insist on a fiscally irresponsible bill that will benefit the wealthiest and in this case the healthiest at the cost of at least $174 billion added to our already…
Mr. Speaker, I thank the gentleman for yielding me this time. Mr. Speaker, in the next few hours, the Republicans in the Congress will engage in the greatest raid and diminishment on middle-class…

Mr. Speaker, I yield myself such time as I may consume. The chairman of the Committee on Ways and Means connected this bill with senior citizens' inability to plan for their future. Well, I am glad…
Mr. Speaker, this bill is a sham. It does not provide adequate prescription drug benefit. Este projecto de ley no ayudara a los ancionos. No ayudara ni a nuestras madres ni a nuestras abuelitas.…
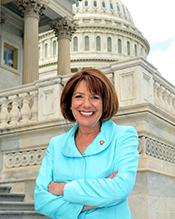
Mr. Speaker, I oppose this unacceptable bill that is particularly harmful to senior women. Mr. Speaker, I rise to talk about older women and their need for a real prescription drug benefit. The…
Mr. Speaker, let me thank the gentlewoman from Ohio (Ms. Pryce) for her leadership in chairing our majority conference as well as her leadership on this issue and this rule. Mr. Speaker, I find it…

Mr. Speaker, I oppose this Republican Medicare bill, and I urge every woman, man, every American to read the fine print. There are gaping holes. There are problems. I will put this into the Record…
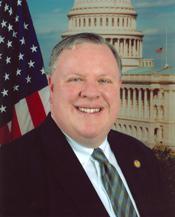
Mr. Speaker, I really wish more of the American public were watching this debate because they would be able to fully appreciate how marginal the left has become to any serious debate about the…
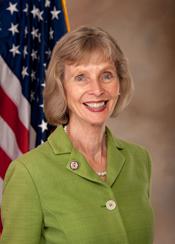
Mr. Speaker, I oppose this Republican prescription bill because it provides elderly women with nothing more than a false sense of security. Mr. Speaker, I thank my colleague for yielding me the time.…
Mr. Speaker, I thank my colleague for yielding me the time. Mr. Speaker, we have an opportunity today. We have an opportunity to make prescription drugs both available and affordable to our Nation's…
Bill Text
Latest available legislative text
        [Congressional Bills 108th Congress]
[From the U.S. Government Publishing Office]
[H.R. 2596 Introduced in House (IH)]

108th CONGRESS
1st Session
H. R. 2596

To amend the Internal Revenue Code of 1986 to allow a deduction to
individuals for amounts contributed to health savings security accounts
and health savings accounts, to provide for the disposition of unused
health benefits in cafeteria plans and flexible spending arrangements,
and for other purposes.

_______________________________________________________________________

IN THE HOUSE OF REPRESENTATIVES

June 25, 2003

Mr. Thomas introduced the following bill; which was referred to the
Committee on Ways and Means

_______________________________________________________________________

A BILL

To amend the Internal Revenue Code of 1986 to allow a deduction to
individuals for amounts contributed to health savings security accounts
and health savings accounts, to provide for the disposition of unused
health benefits in cafeteria plans and flexible spending arrangements,
and for other purposes.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE.

This Act may be cited as the ``Health Savings and Affordability Act
of 2003''.

SEC. 2. HEALTH SAVINGS SECURITY ACCOUNTS AND HEALTH SAVINGS ACCOUNTS.

(a) In General.--Part VII of subchapter B of chapter 1 of the
Internal Revenue Code of 1986 (relating to additional itemized
deductions for individuals) is amended by redesignating section 223 as
section 225 and by inserting after section 222 the following new
sections:

``SEC. 223. HEALTH SAVINGS SECURITY ACCOUNTS.

``(a) Deduction Allowed.--In the case of an individual who is an
eligible individual for any month during the taxable year, there shall
be allowed as a deduction for the taxable year an amount equal to the
aggregate amount paid in cash during such taxable year by such
individual to a health savings security account of such individual.
``(b) Limitations.--
``(1) In general.--The amount allowable as a deduction
under subsection (a) to an individual for the taxable year
shall not exceed the sum of the monthly limitations for months
during such taxable year that the individual is an eligible
individual.
``(2) Monthly limitation.--The monthly limitation for any
month is \1/12\ of--
``(A) $2,000, in the case of an eligible individual
who--
``(i) has self-only coverage under a
minimum deductible plan as of the first day of
such month, or
``(ii) is uninsured as of the first day of
such month and is not described in subparagraph
(B)(ii) with respect to the taxable year which
includes such month,
``(B) $4,000, in the case of an eligible individual
who--
``(i) has family coverage under a minimum
deductible plan as of the first day of such
month, or
``(ii) is uninsured as of the first day of
such month and, with respect to the taxable
year which includes such month--
``(I) is entitled to a deduction
for a dependent under section 151(c)
(or would be so entitled but for
paragraph (2) or (4) of section
152(e)), or
``(II) files a joint return, and
``(C) zero in any other case.
``(3) Additional contributions for individuals 55 or
older.--
``(A) In general.--In the case of an individual who
has attained the age of 55 before the close of the
taxable year, paragraph (2) shall be applied by
increasing the $2,000 amount in paragraph (2)(A) and
the $4,000 amount in paragraph (2)(B) by the additional
contribution amount.
``(B) Additional contribution amount.--For purposes
of this section, the additional contribution amount is
the amount determined in accordance with the following
table:

``For taxable years                                      The additional
beginning in:                                   contribution amount is:
2004..........................................                $500
2005..........................................                $600
2006..........................................                $700
2007..........................................                $800
2008..........................................                $900
2009 and thereafter...........................              $1,000.

``(4) Limitation based on adjusted gross income.--
``(A) Self-only coverage.--The dollar amount in
paragraph (2)(A) (as increased under paragraph (3))
shall be reduced (but not below zero) by an amount
which bears the same ratio to such dollar amount as--
``(i) the amount (if any) by which the
taxpayer's adjusted gross income for such
taxable year exceeds $75,000 ($150,000 in the
case of a joint return), bears to
``(ii) $10,000 ($20,000 in the case of a
joint return).
``(B) Family coverage.--The dollar amount in
paragraph (2)(B) (as increased under paragraph (3))
shall be reduced (but not below zero) by an amount
which bears the same ratio to such dollar amount as--
``(i) the amount (if any) by which the
taxpayer's adjusted gross income for such
taxable year exceeds $150,000, bears to
``(ii) $20,000.
``(C) No reduction below $200 until complete phase-
out.--No dollar amount shall be reduced below $200
under subparagraph (A) or (B) unless (without regard to
this subparagraph) such limitation is reduced to zero.
``(D) Rounding.--Any amount determined under this
paragraph which is not a multiple of $10 shall be
rounded to the next lowest $10.
``(E) Adjusted gross income.--For purposes of this
paragraph, adjusted gross income shall be determined--
``(i) without regard to this section or
section 911, and
``(ii) after application of sections 86,
135, 137, 219, 221, 222, and 469.
``(5) Coordination with other contributions.--The
limitation which would (but for this paragraph) apply under
this subsection to the taxpayer for any taxable year shall be
reduced (but not below zero) by the sum of--
``(A) the aggregate amount paid during such taxable
year to Archer MSAs of such individual,
``(B) the aggregate amount paid during such taxable
year to health savings accounts of such individual, and
``(C) the aggregate amount paid during such taxable
year to health savings security accounts of such
individual by persons other than such individual.
``(6) Special rules for married individuals, dependents,
and medicare eligible individuals.--Rules similar to the rules
of paragraphs (3), (6), and (7) of section 220(b) shall apply
for purposes of this section.
``(c) Definitions.--For purposes of this section--
``(1) Eligible individual.--
``(A) In general.--The term `eligible individual'
means, with respect to any month, any individual unless
such individual is covered, as of the first day of such
month, under any health plan which is not a minimum
deductible plan.
``(B) Certain coverage disregarded.--Subparagraph
(A) shall be applied without regard to--
``(i) coverage for any benefit provided by
permitted insurance, and
``(ii) coverage (whether through insurance
or otherwise) for accidents, disability, dental
care, vision care, or long-term care.
``(2) Minimum deductible plan.--
``(A) In general.--The term `minimum deductible
plan' means a health plan--
``(i) in the case of self-only coverage,
which has an annual deductible which is not
less than $500, and
``(ii) in the case of family coverage,
which has an annual deductible which is not
less than twice the dollar amount in clause (i)
(as increased under subparagraph (B)).
``(B) Cost-of-living adjustment for annual
deductibles.--
``(i) In general.--In the case of any
taxable year beginning in a calendar year after
2004, the $500 amount in subparagraph (A)(i)
shall be increased by an amount equal to--
``(I) such dollar amount,
multiplied by
``(II) the cost-of-living
adjustment determined under section
1(f)(3) for the calendar year in which
such taxable year begins by
substituting `calendar year 2003' for
`calendar year 1992' in subparagraph
(B) thereof.
``(ii) Rounding.--If any increase under
clause (i) is not a multiple of $50, such
increase shall be rounded to the nearest
multiple of $50.
``(C) Special rules.--
``(i) Exclusion of certain plans.--Such
term does not include a health plan if
substantially all of its coverage is coverage
described in paragraph (1)(B).
``(ii) Safe harbor for absence of
preventive care deductible.--A plan shall not
fail to be treated as a minimum deductible plan
by reason of failing to have a deductible for
preventive care.
``(3) Uninsured.--An individual shall be treated as
uninsured if such individual is not covered by insurance which
constitutes medical care. The preceding sentence shall be
applied without regard to the coverage described in paragraph
(1)(B).
``(4) Permitted insurance.--The term `permitted insurance'
has the meaning given such term in section 220(c)(3).
``(5) Family coverage.--The term `family coverage' has the
meaning given such term in section 220(c)(5).
``(6) Archer msa.--The term `Archer MSA' has the meaning
given such term in section 220(d).
``(7) Health Savings Account.--The term `health savings
account' has the meaning given such term in section 224(d).
``(d) Health Savings Security Account.--For purposes of this
section--
``(1) In general.--The term `health savings security
account' means a trust created or organized in the United
States as a health savings security account exclusively for the
purpose of paying the qualified medical expenses of the account
beneficiary, but only if the written governing instrument
creating the trust meets the following requirements:
``(A) Except in the case of a rollover contribution
from an Archer MSA, or a health savings security
account, which is not includible in gross income, no
contribution will be accepted--
``(i) unless it is in cash and is
contributed by--
``(I) the account beneficiary,
``(II) a member of the family of
the account beneficiary, or
``(III) an employer of the account
beneficiary, and
``(ii) to the extent such contribution,
when added to previous contributions to the
trust for the calendar year, exceeds the
highest annual limitation which could apply to
an individual under subsection (b) for a
taxable year beginning in such calendar year.
``(B) The trustee is a bank (as defined in section
408(n)), an insurance company (as defined in section
816), or another person who demonstrates to the
satisfaction of the Secretary that the manner in which
such person will administer the trust will be
consistent with the requirements of this section.
``(C) No part of the trust assets will be invested
in life insurance contracts.
``(D) The assets of the trust will not be
commingled with other property except in a common trust
fund or common investment fund.
``(E) The interest of an individual in the balance
in his account is nonforfeitable.
``(2) Member of the family.--The term `member of the
family' has the meaning given such term in section 2032A(e)(2).
``(3) Qualified medical expenses.--The term `qualified
medical expenses' has the meaning given such term in section
220(d)(2), except that--
``(A) subparagraph (B)(i) thereof shall not apply
to--
``(i) insurance which constitutes a minimum
deductible plan if no portion of the cost of
such insurance is paid by an employer or former
employer of the account beneficiary or the
spouse of such beneficiary, and
``(ii) any health insurance (other than
health insurance substantially all of its
coverage is coverage described in subsection
(c)(1)(B)) if the account beneficiary has
attained age 65, and
``(B) subparagraph (C) thereof shall not apply for
purposes of this section.
``(4) Account beneficiary.--The term `account beneficiary'
means the individual on whose behalf the health savings
security account was established.
``(5) Certain rules to apply.--Rules similar to the
following rules shall apply for purposes of this section:
``(A) Section 219(d)(2) (relating to no deduction
for rollovers).
``(B) Section 219(f)(3) (relating to time when
contributions deemed made).
``(C) Except as provided in section 106(d), section
219(f)(5) (relating to employer payments).
``(D) Section 408(g) (relating to community
property laws).
``(E) Section 408(h) (relating to custodial
accounts).
``(6) Contributions from flexible spending accounts treated
as made by the employer.--Any contribution from a flexible
spending account to a health savings security account which is
not includible in the gross income of the employee by reason of
section 125(h) shall be treated as a contribution made by the
employer for purposes of this section.
``(e) Tax Treatment of Accounts.--
``(1) In general.--A health savings security account is
exempt from taxation under this subtitle unless such account
has ceased to be a health savings security account.
Notwithstanding the preceding sentence, any such account is
subject to the taxes imposed by section 511 (relating to
imposition of tax on unrelated business income of charitable,
etc. organizations).
``(2) Account terminations.--Rules similar to the rules of
paragraphs (2) and (4) of section 408(e) shall apply to health
savings security accounts, and any amount treated as
distributed under such similar rules shall be treated as not
used to pay qualified medical expenses.
``(f) Tax Treatment of Distributions.--
``(1) Amounts used for qualified medical expenses.--Any
amount paid or distributed out of a health savings security
account which is used exclusively to pay qualified medical
expenses of any account beneficiary shall not be includible in
gross income.
``(2) Inclusion of amounts not used for qualified medical
expenses.--
``(A) In general.--Any amount paid or distributed
out of a health savings security account which is not
used exclusively to pay the qualified medical expenses
of the account beneficiary shall be included in the
gross income of such beneficiary in the manner provided
under section 72.
``(B) Special rules for applying section 72.--For
purposes of applying section 72 to any amount described
in subparagraph (A)--
``(i) all health savings security accounts
shall be treated as 1 contract,
``(ii) all distributions during any taxable
year shall be treated as 1 distribution,
``(iii) the value of the contract, income
on the contract, and investment in the contract
shall be computed as of the close of the
calendar year in which the taxable year begins,
and
``(iv) such distributions shall be treated
as made from contributions from members of the
family of the account beneficiary to the extent
that such distribution, when added to all
previous distributions from the health savings
security account taken into account under this
clause, do not exceed the aggregate
contributions from members of such family.
``(3) Excess contributions returned before due date of
return.--
``(A) In general.--If any excess contribution is
contributed for a taxable year to any health savings
security account of an individual, paragraph (2) shall
not apply to distributions from the health savings
security accounts of such individual (to the extent
such distributions do not exceed the aggregate excess
contributions to all such accounts of such individual
for such year) if--
``(i) such distribution is made on or
before the last day prescribed by law
(including extensions of time) for filing the
account beneficiary's return for such taxable
year,
``(ii) no deduction is allowed under this
section with respect to such contribution,
``(iii) such distribution is accompanied by
the amount of net income attributable to such
excess contribution, and
``(iv) such distribution satisfies the
requirements of subparagraph (B).
``(B) Rules related to ordering.--
``(i) Distributions limited to
contributions.--Subparagraph (A) shall apply to
distributions to a person only to the extent of
the contributions of such person to such
accounts during such taxable year.
``(ii) Classes of contributors.--
Subparagraph (A) shall apply only to
distributions of such contributions which are
made in the following order:
``(I) first, to members of the
family of the account beneficiary,
``(II) second, to the account
beneficiary,
``(III) third, to employers of the
account beneficiary with respect to
contributions under section 125(h), and
``(IV) fourth, to employers of the
account beneficiary with respect to
contributions under section 106(d).
``(iii) Last-in first-out.--If
distributions could be made to more than one
person under any subclause of clause (ii),
subparagraph (A) shall not apply to any such
distribution unless such distribution is of the
most recent excess contribution which has not
been distributed to the contributor.
``(C) Treatment of net income.--Any net income
described in subparagraph (A)(iii) shall be included in
the gross income of the person receiving the
distribution for the taxable year in which received.
``(D) Excess contribution.--For purposes of
subparagraph (A), the term `excess contribution' means
any contribution (other than a rollover contribution
from another health savings security account, or from
an Archer MSA, which is not includible in gross income)
to the extent such contribution results in the
aggregate contributions to health savings security
accounts of the account beneficiary for the taxable
year to be in excess of the limitation under subsection
(b) (determined without regard to paragraph (5)(C)
thereof) which applies to such beneficiary for such
year.
``(4) Additional tax on distributions not used for
qualified medical expenses.--
``(A) In general.--The tax imposed by this chapter
on the account beneficiary for any taxable year in
which there is a payment or distribution from a health
savings security account of such beneficiary which is
includible in gross income under paragraph (2) shall be
increased by 15 percent of the amount which is so
includible.
``(B) Exception for disability or death.--
Subparagraph (A) shall not apply if the payment or
distribution is made after the account beneficiary
becomes disabled within the meaning of section 72(m)(7)
or dies.
``(C) Exception for distributions after medicare
eligibility.--Subparagraph (A) shall not apply to any
payment or distribution after the date on which the
account beneficiary attains the age specified in
section 1811 of the Social Security Act.
``(5) Rollover contribution.--
``(A) In general.--Paragraph (2) shall not apply to
any amount paid or distributed from a health savings
security account to the account beneficiary to the
extent the amount received is paid into a health
savings security account, or a health savings account,
for the benefit of such beneficiary not later than the
60th day after the day on which the beneficiary
receives the payment or distribution.
``(B) Limitation.--This paragraph shall not apply
to any amount described in subparagraph (A) received by
an individual from a health savings security account
if, at any time during the 1-year period ending on the
day of such receipt, such individual received any other
amount described in subparagraph (A) from a health
savings security account which was not includible in
the individual's gross income because of the
application of this paragraph.
``(6) Special rules.--Rules similar to the rules of
paragraphs (6), (7), and (8) of section 220(f) shall apply for
purposes of this section.
``(g) Reports.--The Secretary may require the trustee of a health
savings security account to make such reports regarding such account to
the Secretary and to the account beneficiary with respect to
contributions, distributions, and such other matters as the Secretary
determines appropriate. The reports required by this subsection shall
be filed at such time and in such manner and furnished to such
individuals at such time and in such manner as may be required by the
Secretary.
``(h) Regulations.--The Secretary may issue regulations to carry
out the purposes of this section, including regulations regarding the
proper treatment of distributions described in subsection (f)(3) and
nondeductible contributions by members of the family of the account
beneficiary.

``SEC. 224. HEALTH SAVINGS ACCOUNTS.

``(a) Deduction Allowed.--In the case of an individual who is an
eligible individual for any month during the taxable year, there shall
be allowed as a deduction for the taxable year an amount equal to the
aggregate amount paid in cash during such taxable year by such
individual to a health savings account of such individual.
``(b) Limitations.--
``(1) In general.--The amount allowable as a deduction
under subsection (a) to an individual for the taxable year
shall not exceed the sum of the monthly limitations for months
during such taxable year that the individual is an eligible
individual.
``(2) Monthly limitation.--The monthly limitation for any
month is the amount equal to \1/12\ of the annual deductible
(as of the first day of such month) of the individual's
coverage under the high deductible health plan.
``(3) Coordination with other contributions.--The
limitation which would (but for this paragraph) apply under
this subsection to the taxpayer for any taxable year shall be
reduced (but not below zero) by the sum of--
``(A) the aggregate amount paid during such taxable
year to Archer MSAs of such individual,
``(B) the aggregate amount paid during such taxable
year to health savings security accounts of such
individual, and
``(C) the aggregate amount paid during such taxable
year to health savings accounts of such individual by
persons other than such individual.
``(4) Special rules for married individuals, dependents,
and medicare eligible individuals.--Rules similar to the rules
of paragraphs (3), (6), and (7) of section 220(b) shall apply
for purposes of this section.
``(c) Definitions.--For purposes of this section--
``(1) Eligible individual.--
``(A) In general.--The term `eligible individual'
means, with respect to any month, any individual if--
``(i) such individual is covered under a
high deductible health plan as of the 1st day
of such month, and
``(ii) such individual is not, while
covered under a high deductible health plan,
covered under any health plan--
``(I) which is not a high
deductible health plan, and
``(II) which provides coverage for
any benefit which is covered under the
high deductible health plan.
``(B) Certain coverage disregarded.--Subparagraph
(A)(ii) shall be applied without regard to--
``(i) coverage for any benefit provided by
permitted insurance, and
``(ii) coverage (whether through insurance
or otherwise) for accidents, disability, dental
care, vision care, or long-term care.
``(2) High deductible health plan.--
``(A) In general.--The term `high deductible health
plan' means a health plan--
``(i) in the case of self-only coverage,
which has an annual deductible which is not
less than $1,000 and not more than $2,250,
``(ii) in the case of family coverage,
which has an annual deductible which is not
less than $2,000 and not more than $4,500, and
``(iii) the annual out-of-pocket expenses
required to be paid under the plan (other than
for premiums) for covered benefits does not
exceed--
``(I) $3,000 for self-only
coverage, and
``(II) $5,500 for family coverage.
``(B) Cost-of-living adjustment.--
``(i) In general.--In the case of any
taxable year beginning in a calendar year after
1998, each dollar amount in subparagraph (A)
shall be increased by an amount equal to--
``(I) such dollar amount,
multiplied by
``(II) the cost-of-living
adjustment determined under section
1(f)(3) for the calendar year in which
such taxable year begins by
substituting `calendar year 1997' for
`calendar year 1992' in subparagraph
(B) thereof.
``(ii) Special rules.--In the case of the
$1,000 amount in subparagraph (A)(i) and the
$2,000 amount in subparagraph (A)(ii),
subclause (i)(II) shall be applied by
substituting `calendar year 2002' for `calendar
year 1997'.
``(iii) Rounding.--If any increase under
clause (i) or (ii) is not a multiple of $50,
such increase shall be rounded to the nearest
multiple of $50.
``(C) Special rules.--
``(i) Exclusion of certain plans.--Such
term does not include a health plan if
substantially all of its coverage is coverage
described in paragraph (1)(B).
``(ii) Safe harbor for absence of
preventive care deductible.-- A plan shall not
fail to be treated as a high deductible health
plan by reason of failing to have a deductible
for preventive care.
``(D) Treatment of network services.--
``(i) In general.--In the case of a health
plan which is a preferred provider organization
plan and which would (without regard to
services provided outside such organization's
network of providers described in clause
(iii)(I)) be a high deductible health plan,
such plan shall not fail to be a high
deductible health plan because--
``(I) the annual deductible for
services provided outside such network
exceeds the applicable maximum dollar
amount in clause (i) or (ii) of
subparagraph (A), or
``(II) the annual out-of-pocket
expenses required to be paid for
services provided outside such network
exceeds the applicable dollar amount in
subparagraph (A)(iii).
``(ii) Annual deductible.--The annual
deductible taken into account under subsection
(b)(2) with respect to a plan which is a high
deductible health plan by reason of clause (i)
shall be the annual deductible for services
provided within such network.
``(iii) Preferred provider organization
plan defined.--In this subparagraph, the term
`preferred provider organization plan' means a
health plan that--
``(I) has a network of providers
that have agreed to a contractually
specified reimbursement for covered
benefits with the organization offering
the plan,
``(II) provides for reimbursement
for all covered benefits regardless of
whether such benefits are provided
within such network of providers, and
``(III) is offered by an
organization that is not licensed or
organized under State law as a health
maintenance organization.
``(3) Permitted insurance.--The term `permitted insurance'
has the meaning given such term in section 220(c)(3).
``(4) Family coverage.--The term `family coverage' has the
meaning given such term in section 220(c)(5).
``(5) Archer msa.--The term `Archer MSA' has the meaning
given such term in section 220(d).
``(6) Health savings security account.--The term `health
savings security account' has the meaning given such term in
section 223(d).
``(d) Health Savings Account.--For purposes of this section--
``(1) In general.--The term `health savings account' means
a trust created or organized in the United States as a health
savings account exclusively for the purpose of paying the
qualified medical expenses of the account beneficiary, but only
if the written governing instrument creating the trust meets
the following requirements:
``(A) Except in the case of a rollover contribution
from an Archer MSA, a health savings security account,
or a health savings account, which is not includible in
gross income, no contribution will be accepted--
``(i) unless it is in cash and is
contributed by--
``(I) the account beneficiary, or
``(II) an employer of the account
beneficiary, and
``(ii) to the extent such contribution,
when added to previous contributions to the
trust for the calendar year, exceeds the
highest annual limitation which could apply to
an individual under subsection (b) for a
taxable year beginning in such calendar year.
``(B) The trustee is a bank (as defined in section
408(n)), an insurance company (as defined in section
816), or another person who demonstrates to the
satisfaction of the Secretary that the manner in which
such person will administer the trust will be
consistent with the requirements of this section.
``(C) No part of the trust assets will be invested
in life insurance contracts.
``(D) The assets of the trust will not be
commingled with other property except in a common trust
fund or common investment fund.
``(E) The interest of an individual in the balance
in his account is nonforfeitable.
``(2) Qualified medical expenses.--The term `qualified
medical expenses' has the meaning given such term in section
220(d)(2).
``(3) Account beneficiary.--The term `account beneficiary'
means the individual on whose behalf the health savings account
was established.
``(4) Certain rules to apply.--Rules similar to the
following rules shall apply for purposes of this section:
``(A) Section 219(d)(2) (relating to no deduction
for rollovers).
``(B) Section 219(f)(3) (relating to time when
contributions deemed made).
``(C) Except as provided in section 106(d), section
219(f)(5) (relating to employer payments).
``(D) Section 408(g) (relating to community
property laws).
``(E) Section 408(h) (relating to custodial
accounts).
``(6) Contributions from flexible spending accounts treated
as made by the employer.--Any contribution from a flexible
spending account to a health savings account which is not
includible in the gross income of the employee by reason of
section 125(h) shall be treated as a contribution made by the
employer for purposes of this section.
``(e) Tax Treatment of Accounts.--
``(1) In general.--A health savings account is exempt from
taxation under this subtitle unless such account has ceased to
be a health savings account. Notwithstanding the preceding
sentence, any such account is subject to the taxes imposed by
section 511 (relating to imposition of tax on unrelated
business income of charitable, etc. organizations).
``(2) Account terminations.--Rules similar to the rules of
paragraphs (2) and (4) of section 408(e) shall apply to health
savings accounts, and any amount treated as distributed under
such rules shall be treated as not used to pay qualified
medical expenses.
``(f) Tax Treatment of Distributions.--
``(1) Amounts used for qualified medical expenses.--Any
amount paid or distributed out of a health savings account
which is used exclusively to pay qualified medical expenses of
any account beneficiary shall not be includible in gross
income.
``(2) Inclusion of amounts not used for qualified medical
expenses.--Any amount paid or distributed out of a health
savings account which is not used exclusively to pay the
qualified medical expenses of the account beneficiary shall be
included in the gross income of such beneficiary.
``(3) Excess contributions returned before due date of
return.--
``(A) In general.--If any excess contribution is
contributed for a taxable year to any health savings
account of an individual, paragraph (2) shall not apply
to distributions from the health savings accounts of
such individual (to the extent such distributions do
not exceed the aggregate excess contributions to all
such accounts of such individual for such year) if--
``(i) such distribution is made on or
before the last day prescribed by law
(including extensions of time) for filing the
account beneficiary's return for such taxable
year,
``(ii) no deduction is allowed under this
section with respect to such contribution,
``(iii) such distribution is accompanied by
the amount of net income attributable to such
excess contribution, and
``(iv) such distribution satisfies the
requirements of subparagraph (B).
``(B) Rules related to ordering.--
``(i) Distributions limited to
contributions.--Subparagraph (A) shall apply to
distributions to a person only to the extent of
the contributions of such person to such
accounts during such taxable year.
``(ii) Classes of contributors.--
Subparagraph (A) shall apply only to
distributions of such contributions which are
made in the following order:
``(I) first, to the account
beneficiary,
``(II) second, to employers of the
account beneficiary with respect to
contributions under section 125(h), and
``(III) third, to employers of the
account beneficiary with respect to
contributions under section 106(d).
``(iii) Last-in first-out.--If
distributions could be made to more than one
person under any subclause of clause (ii),
subparagraph (A) shall not apply to any such
distribution unless such distribution is of the
most recent excess contribution which has not
been distributed to the contributor.
``(C) Treatment of net income.--Any net income
described in subparagraph (A)(iii) shall be included in
the gross income of the person receiving the
distribution for the taxable year in which received.
``(D) Excess contribution.--For purposes of
subparagraph (A), the term `excess contribution' means
any contribution (other than a rollover contribution
from another health savings account, from a health
savings security account, or from an Archer MSA, which
is not includible in gross income) to the extent such
contribution results in the aggregate contributions to
health savings accounts of the account beneficiary for
the taxable year to be in excess of the limitation
under subsection (b) (determined without regard to
paragraph (3)(C) thereof) which applies to such
beneficiary for such year.
``(4) Additional tax on distributions not used for
qualified medical expenses.--
``(A) In general.--The tax imposed by this chapter
on the account beneficiary for any taxable year in
which there is a payment or distribution from a health
savings account of such beneficiary which is includible
in gross income under paragraph (2) shall be increased
by 15 percent of the amount which is so includible.
``(B) Exception for disability or death.--
Subparagraph (A) shall not apply if the payment or
distribution is made after the account beneficiary
becomes disabled within the meaning of section 72(m)(7)
or dies.
``(C) Exception for distributions after medicare
eligibility.--Subparagraph (A) shall not apply to any
payment or distribution after the date on which the
account beneficiary attains the age specified in
section 1811 of the Social Security Act.
``(5) Rollover contribution.--
``(A) In general.--Paragraph (2) shall not apply to
any amount paid or distributed from a health savings
account to the account beneficiary to the extent the
amount received is paid into a health savings account
for the benefit of such beneficiary not later than the
60th day after the day on which the beneficiary
receives the payment or distribution.
``(B) Limitation.--This paragraph shall not apply
to any amount described in subparagraph (A) received by
an individual from a health savings account if, at any
time during the 1-year period ending on the day of such
receipt, such individual received any other amount
described in subparagraph (A) from a health savings
account which was not includible in the individual's
gross income because of the application of this
paragraph.
``(6) Special rules.--Rules similar to the rules of
paragraphs (6), (7), and (8) of section 220(f) shall apply for
purposes of this section.
``(g) Reports.--The Secretary may require the trustee of a health
savings account to make such reports regarding such account to the
Secretary and to the account beneficiary with respect to contributions,
distributions, and such other matters as the Secretary determines
appropriate. The reports required by this subsection shall be filed at
such time and in such manner and furnished to such individuals at such
time and in such manner as may be required by the Secretary.''.
(b) Deduction Allowed Whether or Not Individual Itemizes Other
Deductions.--Subsection (a) of section 62 of such Code is amended by
inserting after paragraph (18) the following new paragraphs:
``(19) Health savings security accounts.--The deduction
allowed by section 223.
``(20) Health savings accounts.--The deduction allowed by
section 224.''.
(c) Coordination With Archer MSAs.--
(1) Rollovers from archer msas permitted.--Subparagraph (A)
of section 220(f)(5) of such Code (relating to rollover
contribution) is amended by inserting ``, a health savings
security account (as defined in section 223(d)), or a health
savings account (as defined in section 224(d)),'' after ``paid
into an Archer MSA''.
(2) Reduction in archer msa limitation for contributions to
health savings security accounts and health savings accounts.--
Subsection (b) of section 220 of such Code (relating to
limitations) is amended by adding at the end the following new
paragraph:
``(8) Coordination with health savings security accounts
and health savings accounts.--The limitation which would (but
for this paragraph) apply under this subsection to the taxpayer
for any taxable year shall be reduced (but not below zero) by
the sum of--
``(A) the aggregate amount paid during such taxable
year to health savings security accounts of such
individual, and
``(B) the aggregate amount paid during such taxable
year to health savings accounts of such individual.''.
(d) Exclusions for Employer Contributions to Health Savings
Security Accounts and Health Savings Accounts.--
(1) Exclusion from income tax.--Section 106 of such Code
(relating to contributions by employer to accident and health
plans) is amended by adding at the end the following new
subsections:
``(d) Contributions to Health Savings Security Accounts.--
``(1) In general.--In the case of an employee who is an
eligible individual, amounts contributed by such employee's
employer to any health savings security account of such
employee shall be treated as employer-provided coverage for
medical expenses under an accident or health plan to the extent
such amounts do not exceed the limitation under section 223(b)
(determined without regard to this subsection) which is
applicable to such employee for such taxable year.
``(2) Special rules.--Rules similar to the rules of
paragraphs (2), (3), (4), and (5) of subsection (b) shall apply
for purposes of this subsection.
``(3) Definitions.--For purposes of this subsection, the
terms `eligible individual' and `health savings security
account' have the respective meanings given to such terms by
section 223.
``(4) Cross reference.--

``For penalty on failure by employer to
make comparable contributions to the health savings security accounts
of comparable employees, see section 4980G.
``(e) Contributions to Health Savings Accounts.--
``(1) In general.--In the case of an employee who is an
eligible individual, amounts contributed by such employee's
employer to any health savings account of such employee shall
be treated as employer-provided coverage for medical expenses
under an accident or health plan to the extent such amounts do
not exceed the limitation under section 224(b) (determined
without regard to this subsection) which is applicable to such
employee for such taxable year.
``(2) Special rules.--Rules similar to the rules of
paragraphs (2), (3), (4), and (5) of subsection (b) shall apply
for purposes of this subsection.
``(3) Definitions.--For purposes of this subsection, the
terms `eligible individual' and `health savings account' have
the respective meanings given to such terms by section 224.
``(4) Cross reference.--

``For penalty on failure by employer to
make comparable contributions to the health savings accounts of
comparable employees, see section 4980G.''.
(2) Exclusion from employment taxes.--
(A) Railroad retirement tax.--Subsection (e) of
section 3231 of such Code is amended by adding at the
end the following new paragraph:
``(11) Health savings security account and health savings
account contributions.--The term `compensation' shall not
include any payment made to or for the benefit of an employee
if at the time of such payment it is reasonable to believe that
the employee will be able to exclude such payment from income
under subsection (d) or (e) of section 106.''.
(B) Unemployment tax.--Subsection (b) of section
3306 of such Code is amended by striking ``or'' at the
end of paragraph (16), by striking the period at the
end of paragraph (17) and inserting ``; or'', and by
inserting after paragraph (17) the following new
paragraph:
``(18) any payment made to or for the benefit of an
employee if at the time of such payment it is reasonable to
believe that the employee will be able to exclude such payment
from income under subsection (d) or (e) of section 106.''.
(C) Withholding tax.--Subsection (a) of section
3401 of such Code is amended by striking ``or'' at the
end of paragraph (20), by striking the period at the
end of paragraph (21) and inserting ``; or'', and by
inserting after paragraph (21) the following new
paragraph:
``(22) any payment made to or for the benefit of an
employee if at the time of such payment it is reasonable to
believe that the employee will be able to exclude such payment
from income under subsection (d) or (e) of section 106.''
(3) Employer contributions required to be shown on w-2.--
Subsection (a) of section 6051 of such Code is amended by
striking ``and'' at the end of paragraph (10), by striking the
period at the end of paragraph (11) and inserting a comma, and
by inserting after paragraph (11) the following new paragraphs:
``(12) the amount contributed to any health savings
security account (as defined in section 223(d)) of such
employee or such employee's spouse, and
``(13) the amount contributed to any health savings account
(as defined in section 224(d)) of such employee or such
employee's spouse.''.
(4) Penalty for failure of employer to make comparable
health savings account contributions.--
(A) In general.--Chapter 43 of such Code is amended
by adding after section 4980F the following new
section:

``SEC. 4980G. FAILURE OF EMPLOYER TO MAKE COMPARABLE HEALTH SAVINGS
ACCOUNT CONTRIBUTIONS.

``(a) General Rule.--In the case of an employer who makes a
contribution to the health savings security account or the health
savings account of any employee during a calendar year, there is hereby
imposed a tax on the failure of such employer to meet the requirements
of subsection (b) for such calendar year.
``(b) Rules and Requirements.--Rules and requirements similar to
the rules and requirements of section 4980E shall apply for purposes of
this section.
``(c) Regulations.--The Secretary shall issue regulations to carry
out the purposes of this section, including regulations providing
special rules for employers who make contributions to more than one of
the following types of accounts during the calendar year:
``(1) An Archer MSA.
``(2) A health savings security account.
``(3) A health savings account.''.
(B) Clerical amendment.--The table of sections for
chapter 43 of such Code is amended by adding after the
item relating to section 4980F the following new item:

``Sec. 4980G. Failure of employer to make comparable health savings
account contributions.''.
(e) Tax on Excess Contributions.--Section 4973 of such Code
(relating to tax on excess contributions to certain tax-favored
accounts and annuities) is amended--
(1) by striking ``or'' at the end of paragraph (3) of
subsection (a),
(2) by inserting after paragraph (4) of subsection (a) the
following new paragraphs:
``(5) a health savings security account (within the meaning
of section 223(d)), or
``(6) a health savings account (within the meaning of
section 224(d))'', and
(4) by adding at the end the following new subsections:
``(g) Excess Contributions to Health Savings Security Accounts.--
For purposes of this section, in the case of health savings security
accounts (within the meaning of section 223(d)), the term `excess
contributions' means the sum of--
``(1) the aggregate amount contributed for the taxable year
to the accounts (other than a rollover contribution from
another health savings security account, or from an Archer MSA,
which is not includible in gross income) which is in excess of
the limitation under section 223(b) (determined without regard
to paragraph (5)(C) thereof), and
``(2) the amount determined under this subsection for the
preceding taxable year, reduced by the sum of--
``(A) the distributions out of the accounts which
were included in gross income under section 223(f)(2),
and
``(B) the excess (if any) of--
``(i) the sum of limitations described in
paragraph (1), over
``(ii) the amount contributed to the
accounts for the taxable year.
For purposes of this subsection, any contribution which is distributed
out of the health savings security account in a distribution to which
section 223(f)(3) applies shall be treated as an amount not
contributed.
``(h) Excess Contributions to Health Savings Accounts.--For
purposes of this section, in the case of health savings accounts
(within the meaning of section 224(d)), the term `excess contributions'
means the sum of--
``(1) the aggregate amount contributed for the taxable year
to the accounts (other than a rollover contribution from
another health savings account, a health savings security
account, or from an Archer MSA, which is not includible in
gross income) which is in excess of the limitation under
section 224(b) (determined without regard to paragraph (3)(C)
thereof), and
``(2) the amount determined under this subsection for the
preceding taxable year, reduced by the sum of--
``(A) the distributions out of the accounts which
were included in gross income under section 224(f)(2),
and
``(B) the excess (if any) of--
``(i) the sum of limitations described in
paragraph (1), over
``(ii) the amount contributed to the
accounts for the taxable year.
For purposes of this subsection, any contribution which is distributed
out of the health savings account in a distribution to which section
224(f)(3) applies shall be treated as an amount not contributed.''.
(f) Tax on Prohibited Transactions.--
(1) Section 4975 of such Code (relating to tax on
prohibited transactions) is amended by adding at the end of
subsection (c) the following new paragraphs:
``(6) Special rule for health savings security accounts.--
An individual for whose benefit a health savings security
account (within the meaning of section 223(d)) is established
shall be exempt from the tax imposed by this section with
respect to any transaction concerning such account (which would
otherwise be taxable under this section) if, with respect to
such transaction, the account ceases to be a health savings
security account by reason of the application of section
223(e)(2) to such account.
``(7) Special rule for health savings accounts.--An
individual for whose benefit a health savings account (within
the meaning of section 224(d)) is established shall be exempt
from the tax imposed by this section with respect to any
transaction concerning such account (which would otherwise be
taxable under this section) if, with respect to such
transaction, the account ceases to be a health savings account
by reason of the application of section 224(e)(2) to such
account.''.
(2) Paragraph (1) of section 4975(e) of such Code is
amended by redesignating subparagraphs (E) and (F) as
subparagraphs (G) and (H), respectively, and by inserting after
subparagraph (D) the following new subparagraphs:
``(E) a health savings security account described
in section 223(d),
``(F) a health savings account described in section
224(d),''.
(g) Failure To Provide Reports on Health Savings Accounts.--
Paragraph (2) of section 6693(a) of such Code (relating to reports) is
amended by redesignating subparagraphs (C) and (D) as subparagraphs (E)
and (F), respectively, and by inserting after subparagraph (B) the
following new subparagraphs:
``(C) section 223(g) (relating to health savings
security accounts),
``(D) section 224(g) (relating to health savings
accounts),''.
(h) Exception From Capitalization of Policy Acquisition Expenses.--
Subparagraph (B) of section 848(e)(1) of such Code (defining specified
insurance contract) is amended by striking ``and'' at the end of clause
(iii), by striking the period at the end of clause (iv) and inserting a
comma, and by adding at the end the following new clauses:
``(v) any contract which is a health
savings security account (as defined in section
223(d)), and''.
``(vi) any contract which is a health
savings account (as defined in section
224(d)).''.
(i) Health Savings Security Accounts and Health Savings Accounts
May Be Offered Under Cafeteria Plans.--Paragraph (2) of section 125(d)
(relating to cafeteria plan defined) is amended by adding at the end
the following new subparagraph:
``(D) Exception for health savings accounts.--
Subparagraph (A) shall not apply to a plan to the
extent of amounts which a covered employee may elect to
have the employer pay as contributions to a health
savings security account, or a health savings account,
established on behalf of the employee.''.
(j) Information Reporting by Providers of Health Insurance.--
Subpart B of part III of subchapter A of chapter 61 of such Code is
amended by adding at the end the following new section:

``SEC. 6050U. RETURNS RELATING TO PROVIDERS OF HEALTH INSURANCE.

``(a) Requirement of Reporting.--Under regulations prescribed by
the Secretary, every person who provides any individual with coverage
under a plan which constitutes medical care shall, at such time as the
Secretary may prescribe, make the return described in subsection (b)
with respect to such individual.
``(b) Form and Manner of Returns.--A return is described in this
subsection if such return--
``(1) is in such form as the Secretary may prescribe, and
``(2) contains such information as the Secretary
prescribes.
``(c) Statements To Be Furnished to Individuals With Respect to
Whom Information Is Required.--Every person required to make a return
under subsection (a) shall furnish to each individual whose name is
required to be set forth in such return a written statement showing--
``(1) the name and address of the person required to make
such return and the phone number of the information contact for
such person, and
``(2) the information required to be shown on the return
with respect to such individual.
The written statement required under the preceding sentence shall be
furnished on or before January 31 of the year following the calendar
year for which the return under subsection (a) is required to be
made.''.
(k) Conforming Amendments.--
(1) The table of sections for part VII of subchapter B of
chapter 1 of such Code is amended by striking the last item and
inserting the following:

``Sec. 223. Health savings security accounts.
``Sec. 224. Health savings accounts.
``Sec. 225. Cross reference.''.

(2)(A) Sections 86(b)(2)(A), 135(c)(4)(A), 137(b)(3)(A),
219(g)(3)(A)(ii), and 221(b)(2)(C)(i) are each amended by
inserting ``223,'' after ``222,''.
(B) Section 222(b)(2)(C)(i) is amended by inserting
``223,'' before ``911''.
(C) Section 469(i)(3)(F)(iii) is amended by striking ``and
222'' and inserting ``222, and 223''.
(l) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2003.

SEC. 3. DISPOSITION OF UNUSED HEALTH BENEFITS IN CAFETERIA PLANS AND
FLEXIBLE SPENDING ARRANGEMENTS.

(a) In General.--Section 125 of the Internal Revenue Code of 1986
(relating to cafeteria plans) is amended by redesignating subsections
(h) and (i) as subsections (i) and (j), respectively, and by inserting
after subsection (g) the following:
``(h) Contributions of Certain Unused Health Benefits.--
``(1) In general.--For purposes of this title, a plan or
other arrangement shall not fail to be treated as a cafeteria
plan solely because qualified benefits under such plan include
a health flexible spending arrangement under which not more
than $500 of unused health benefits may be--
``(A) carried forward to the succeeding plan year
of such health flexible spending arrangement,
``(B) to the extent permitted by sections 223 and
224, contributed on behalf of the employee to a health
savings security account (as defined in section
223(d)), or a health savings account (as defined in
section 224(d)), maintained for the benefit of such
employee, or
``(C) contributed to a qualified retirement plan
(as defined in section 4974(c)), or an eligible
deferred compensation plan (as defined in section
457(b)) of an eligible employer described in section
457(e)(1)(A), but only to the extent such amount would
not be allowed as a deduction under--
``(i) section 223 if made directly by the
employee to a health savings security account
of the employee (determined without regard to
any other contributions made by the employee),
and
``(ii) section 224 if made directly by the
employee to a health savings account of the
employee (determined without regard to any
other contributions made by the employee).
``(2) Special rules for treatment of contributions to
retirement plans.--For purposes of this title, contributions
under paragraph (1)(C)--
``(A) shall be treated as elective deferrals (as
defined in section 402(g)(3)) in the case of
contributions to a qualified cash or deferred
arrangement (as defined in section 401(k)) or to an
annuity contract described in section 403(b),
``(B) shall be treated as employer contributions to
which the employee has a nonforfeitable right in the
case of a plan (other than a plan described in
subparagraph (A)) which is described in section 401(a)
which includes a trust exempt from tax under section
501(a),
``(C) shall be treated as deferred compensation in
the case of contributions to an eligible deferred
compensation plan (as defined in section 457(b)), and
``(D) shall be treated in the manner designated for
purposes of section 408 or 408A in the case of
contributions to an individual retirement plan.
``(3) Health flexible spending arrangement.--For purposes
of this subsection, the term `health flexible spending
arrangement' means a flexible spending arrangement (as defined
in section 106(c)) that is a qualified benefit and only permits
reimbursement for expenses for medical care (as defined in
section 213(d)(1) (without regard to subparagraphs (C) and (D)
thereof).
``(4) Unused health benefits.--For purposes of this
subsection, with respect to an employee, the term `unused
health benefits' means the excess of--
``(A) the maximum amount of reimbursement allowable
to the employee during a plan year under a health
flexible spending arrangement, taking into account any
election by the employee, over
``(B) the actual amount of reimbursement during
such year under such arrangement.''.
(b) Effective Date.--The amendment made by subsection (a) shall
apply to taxable years beginning after December 31, 2003.

SEC. 4. EXCEPTION TO INFORMATION REPORTING REQUIREMENTS RELATED TO
CERTAIN HEALTH ARRANGEMENTS.

(a) In General.--Section 6041 (relating to information at source)
is amended by adding at the end the following new subsection:
``(f) Section Does Not Apply to Certain Health Arrangements.--This
section shall not apply to any payment for medical care (as defined in
section 213(d)) made under--
``(1) a flexible spending arrangement (as defined in
section 106(c)(2)), or
``(2) a health reimbursement arrangement which is treated
as employer-provided coverage under an accident or health plan
for purposes of section 106.''.
(b) Effective Date.--The amendment made by this section shall apply
to payments made after December 31, 2002.
<all>