H.R. 46House108th Congress (2003-2005)In Committee
To require the Secretary of the Treasury to submit a study of tax depreciation recovery periods.
Sponsored by 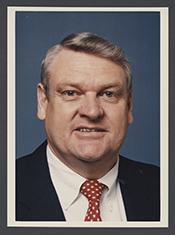 Rep. Mac Collins (R-GA)
Introduced January 7, 2003
Legislative Activity
Stay on top of the latest movement without scrolling through every action
HouseIntro Referral
Latest Action
Referred to the House Committee on Ways and Means.
January 7, 2003
View full timeline
HouseIntro Referral
Introduced in House
January 7, 2003
HouseIntro Referral
Sponsor introductory remarks on measure. (CR E31)
January 7, 2003
HouseIntro Referral
Referred to the House Committee on Ways and Means.
January 7, 2003
Floor Debate
1 memberWhat members said about H.R. 46 on the floor
Floor Debate
1 memberWhat members said about H.R. 46 on the floor
1 Democrat
Rep. Jim McDermottD-WA-7 · Feb 27, 2003
Mr. Speaker, I was unable to vote on yesterday's suspension bills. Had I been capable of voting, I would have voted in support of: H.R. 46--Honoring the life of Al Hirschfeld. H.R. 40--Permitting the…
Bill Text
Latest available legislative text
Introduced in HouseIssued January 7, 2003
        [Congressional Bills 108th Congress]
[From the U.S. Government Publishing Office]
[H.R. 46 Introduced in House (IH)]

108th CONGRESS
1st Session
H. R. 46

To require the Secretary of the Treasury to submit a study of tax
depreciation recovery periods.

_______________________________________________________________________

IN THE HOUSE OF REPRESENTATIVES

January 7, 2003

Mr. Collins introduced the following bill; which was referred to the
Committee on Ways and Means

_______________________________________________________________________

A BILL

To require the Secretary of the Treasury to submit a study of tax
depreciation recovery periods.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. STUDY OF DEPRECIATION RECOVERY PERIODS.

The Secretary of the Treasury or the Secretary's delegate shall
conduct a study of the differences between the depreciation recovery
periods used for computing taxable income or loss under the Internal
Revenue Code of 1986 and for computing net income or loss for financial
statement purposes. Such study shall include such recommendations as
the Secretary may have for adjusting the recovery periods used for tax
purposes to make them closer to the periods used for financial
statement purposes. The report of such study shall be submitted to
Congress not later than 1 year after the date of the enactment of this
Act.
<all>