Mr. President, today I am joined by the Chairman of the Senate Commerce Committee's Consumer Affairs and Product Safety Subcommittee, Senator Fitzgerald, in introducing the Consumer Product Safety…
Mr. President, today I am joined by the Chairman of the Senate Commerce Committee's Consumer Affairs and Product Safety Subcommittee, Senator Fitzgerald, in introducing the Consumer Product Safety Commission Reauthorization Act of 2003. This legislation is designed to reauthorize the Consumer Product Safety Commission, CPSC or Commission, in furtherance of its mission to protect consumers by reducing the risk of injuries and deaths associated with consumer products. This vital consumer protection agency has not been reauthorized since 1990.
This bill would authorize funding for the Commission for fiscal years 2004 through 2007. The bill also would clarify CPSC employee position titles that have evolved informally over time.
The CPSC is essential to ensuring the safety of the approximately 15,000 consumer and household products marketed and sold to American consumers. However, because the agency has not been reauthorized for more than a decade, the Commission has fallen behind in its ability to upgrade its technology, meet its overhead expenses, and retain needed staff. Funding for the Commission has not kept pace with the cost of regulating the ever-increasing number of products covered by its jurisdiction.
I look forward to working on this important consumer protection legislation and I hope that my colleagues will join us in expeditiously moving this reauthorization through the legislative process. Reauthorizing the CPSC is crucial to the Commission's successful efforts to protect American consumers.
I ask unanimous consent that the text of the bill be printed in the Record.
Mr. President, today I am introducing legislation to reauthorize the Maritime Administration, MARAD, for fiscal years 2004, 2005, and 2006. The bill was developed in consultation with Administration officials and would provide for needed reforms in a number of maritime programs.
The bill would authorize appropriations for MARAD operations and training, administrative costs associated with the shipbuilding loan guarantee program authorized by Title XI of the Merchant Marine Act of 1936, and the disposal of vessels in the National Defense Reserve Fleet that have been identified by the Secretary of Transportation as obsolete.
The bill is designed to reform how MARAD manages the Title XI maritime loan guarantee program. Both the Department of Transportation Inspector General and the General Accounting Office have found that MARAD has failed to provide effective oversight in receiving and approving loan guarantees; has failed to closely monitor the financial condition of borrowers during the term of the loan; and has failed to adequately monitor the condition of projects subject to guarantees. They also found that MARAD was flagrant in its use of authority in granting waivers to its own regulations governing the program without taking steps to better secure the taxpayer against defaults. The bill includes reform provisions to address these findings.
Furthermore, the bill would amend the Merchant Marine Act to give the Secretary of Transportation the authority to convey obsolete National Defense Reserve Fleet vessels to nonprofit organizations, a State, Commonwealth, or possession of the United States or any municipal corporation or political subdivision thereof or the District of Columbia for their use and to U.S. territories and foreign governments for use as artificial reefs. The bill also would amend the Merchant Marine Act to allow, under certain circumstances, otherwise unqualified U.S.-flag vessels to carry reference cargo reserved for qualified U.S. vessels.
Finally, the bill would amend requirements for enforcement of the commitment agreements for students at the United States Merchant Marine Academy, USMMA, and students at the state maritime academies who receive student incentive payments, SIP; allow MARAD to use funds received from a settlement for legally authorized purposes, including completion of repairs to the Merchant Marine Academy, Fitch Building; provide the Secretary with the authority to also exclude vessels from the carriage of Government
impelled cargoes that have been detained for violations of security standards contained within international agreements to which the United States is a party; allow MARAD to retain funds received as a result of final judgments and settlements in the Vessel Operations Revolving Fund; and clarify the decades-old authority of the Saint Lawrence Seaway Development Corporation, SLSDC, to carry out the provisions of the Ports and Waterways Safety Act, PWSA, in the case of the Saint Lawrence Seaway.
I look forward to working on this important legislation and hope my colleagues will join me in expeditiously moving this authorization through the legislative process.
I ask unanimous consent that the text of the bill be printed in the Record.
Mr. President, today I am introducing the Federal Communications Commission Reauthorization Act of 2003. This legislation is designed to reauthorize the Federal Communications Commission, FCC or Commission, so that it may continue to carry forth its charge to ensure interference-free communication on interstate and international radio, television, wire, satellite, and cable communications. This independent agency has not been reauthorized since 1991.
The FCC is responsible for a wide range of duties, including establishing regulatory policies that promote competition, innovation, and investment in broadband services; ensuring that a comprehensive and sound national competitive framework for communications services exists; encouraging the best use of spectrum domestically and internationally; and providing leadership for the rapid restoration of the Nation's communications infrastructure in the event of disruption.
This bill would reauthorize the Commission through fiscal year 2007. It would require that all application and regulatory fees paid to the Commission be deposited with the Commission subject to Appropriations.
The legislation also would authorize the Commission to allocate sufficient funds to be used for an audit of the e-rate program to determine the specific fraud or abuse that has occurred during the operation of the program. Serious allegations of fraud in the operation of the e-rate fund have been raised in recent months, and we should provide the Commission adequate resources to ensure that e-rate funds are being used for the purposes intended. The Commission would be required to transmit a report of its findings and conclusions to the Senate Committee on Commerce, Science, and Transportation and the House of Representatives Committee on Energy and Commerce on the anniversary of the Act's enactment for each year between 2004 and 2007.
Further, this bill would clarify the Commission's review of its media ownership rules. Specifically, the bill sets forth the timing and the standard the FCC will use for reviewing its broadcast ownership rules. Currently, the FCC is required to review its broadcast ownership rules every 2 years. The bill lengthens the duration between reviews from 2 years to 5 years. At a recent hearing, all five FCC Commissioners recommended this change.
The legislation also would clarify the actions the FCC may take during its media ownership reviews. Courts have found the current review standard to carry ``with it a presumption in favor of repealing or modifying ownership rules'' as part of ``a process of deregulation.'' This bill modifies the review standard to specifically allow the FCC to repeal, strengthen, limit, or retain media ownership rules if it determines such changes are in the public interest. At a recent hearing, several of the FCC Commissioners endorsed this change.
The bill would increase the Commission's ability to enforce the Communications Act of 1934, the 1934 Act, by raising the statutory cap on Commission fines and forfeitures by a factor of ten. The Commission has sought this increased enforcement ability to ensure communications providers do not accept Commission fines as a ``cost of doing business.'' The bill also increases the statute of limitations for violations of FCC rules or regulations from one year to two years. The legislation also allows the Commission to assess fines against direct broadcast satellite (DBS) operators for violations of the Communications Act in the same manner that the Commission may assess fines against broadcasters and cable operators.
The bill would further clarify that a party injured by a common carrier's violation of FCC rules or orders may recover damages for such injury in an action before the FCC or before a United States District Court. The need for this clarification is underscored by the recent decision by the United States Court of Appeals or the Second Circuit in Conboy v. AT&T Corp. Moreover, the new section would allow for the recovery of attorneys' fees in complaints filed either in district court or at the FCC.
The bill also would allow the Commission to seize broadcasting equipment where one engages in malicious interference to radio communications. This type of behavior is particularly egregious when parties attempt to maliciously interfere with public safety frequencies.
Furthermore, the bill would ensure that valuable spectrum does not lie fallow unnecessarily. It precludes a successful bidder in a spectrum auction from using bankruptcy to avoid its obligation to pay for its spectrum license. The bill also establishes an office within the Commission for the recording and perfecting of security interests related to licenses.
It also would ban any payment or reimbursement to the FCC of travel costs for FCC officials or staff from a nongovernmental sponsor of a convention, conference, or meeting. Recent reports indicate that during the last eight years, FCC officials and staff have taken more than 2,500 trips paid for by the industries they regulate. Although this is perfectly legal and it is often appropriate for FCC officials and staff to attend such conventions, conferences, or meetings, it should be without the appearance of impropriety. Therefore, the bill authorizes the Commission sufficient funds to pay for their own travel costs in the future.
The bill would impose a one year lobbying ban on high-level FCC staffers who leave the FCC's employment.
Finally, the bill contains language in response to a recent court case before the D.C. Circuit Court of Appeals, which held that the Commission lacked jurisdiction to promulgate regulations necessary to require video descriptions of television programming to assist those who are visually impaired. This section would provide the FCC such authority.
Reauthorizing the FCC is important so the agency may continue to successfully carry out its many responsibilities. I look forward to working on this important legislation and I hope that my colleagues will agree to join me in expeditiously moving this reauthorization through the legislative process.
I ask unanimous consent that the text of the bill be printed in the Record.
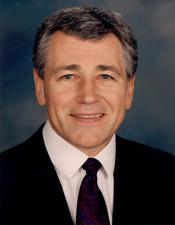 Sen. Chuck Hagel (R-NE)