Retirement Account Portability Act of 2003
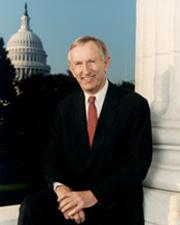 Sen. James M. Jeffords (I-VT)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Read twice and referred to the Committee on Finance. (text of measure as introduced: CR S15408-15411)
November 21, 2003
View full timeline
Introduced in Senate
November 21, 2003
Sponsor introductory remarks on measure. (CR S15408)
November 21, 2003
Read twice and referred to the Committee on Finance. (text of measure as introduced: CR S15408-15411)
November 21, 2003
Floor Debate
22 membersWhat members said about S. 1912 on the floor



 +17
Floor Debate
22 membersWhat members said about S. 1912 on the floor
Mr. President, along with Senator Russ Feingold, I am proud today to introduce the Presidential Funding Act of 2003. This legislation will improve and reform the presidential public financing system.…
Mr. President, today, together with Senators Hatch and Snowe, I am introducing, the Retirement Account Portability and Improvement Act of 2003. This legislation improves the portability of retirement…
Mr. President, it is pleasure to join my friend and colleague Senator McCain in introducing a bill to repair and strengthen the presidential public financing system. The Presidential Funding Act of…
Mr. President, I yield myself 10 minutes. Mr. President, I have sought recognition to comment about an amendment which I have offered on behalf of U.S. Airways. It is an amendment which provides that…
Mr. President, I am please to introduce today, along with my colleague from California, Senator Feinstein, legislation that will further one of the most important public policy goals we have as a…
Show 8 more
Mr. President, today, I am pleased to see that the Senate is taking action on the Pension Equity Act of 2003. As many of my colleagues are aware, the pension discount rate relief initiative, enacted…
Mr. President, in July of 2001, and continuing through January of the following year, the Committee on Banking, Housing, and Urban Affairs held a series of hearings to shine a bright light on the…
Mr. President, I yield myself 5 minutes of the manager's time on this bill. I thank the Chair. Mr. President, Minnesota is home to Northwest Airlines as well as Ispat Inland Steel Mining Company. I…

Yes. For funding purposes, most multiemployer plans recognize investment losses gradually over a period of years. So, part of a plan's investment losses incurred in 2000, for example, would first be…
Mr. President, today, together with Senators Hatch and Snowe, I am introducing, the Retirement Account Portability and Improvement Act of 2003. This legislation improves the portability of retirement…

Mr. President, I rise in support of the Grassley-Baucus- Gregg-Kennedy amendment. I commend the Finance and HELP Committees for working together in a bipartisan effort to secure the pensions of…
Mr. President, I rise today to introduce The American Manufacturing Jobs Bill of 2003--which will provide a tax rate cut for all manufacturers who employ American workers. I am pleased to be joined…
Mr. President, I am proud to offer the Clean Air and Water Investment and Infrastructure Act. Texas, like many States, faces increasingly difficult challenges in improving air and water quality. The…
Show 11 more

Mr. President, I am pleased to join with the distinguished Senator from Pennsylvania, Senator Santorum, to introduce legislation that will promote the American dream of homeownership. Our legislation…

Mr. President, I rise today to introduce legislation that would prevent the closure of the Saginaw Veterans Administration Medical Center in Saginaw, MI. As of August 2003, there were almost one…
Mr. President, ever since the events of September 11, 2001 awakened this Nation to the very real dangers of the world we live in, we have been struggling to defend ourselves against terrorism. Our…
Mr. President, I rise today to introduce a very important piece of legislation, the RU-486 Suspension and Review Act of 2003. The abortion drug RU-486 increases in infamy as its lethal nature…

Mr. President, I am very pleased that the Senate has just passed the Pension Stability Act by an overwhelming margin. I spoke yesterday on behalf of the legislation, because I understand how…

Mr. President, today the Senate passed critical pension funding reform legislation that will protect millions of American workers from losing their defined benefit pension plans. Although only a…

Mr. President, I call attention today to a part of American heritage that is literally disintegrating faster than can be saved. Motion pictures are an important part of our American experience and…

Mr. President, we need to ensure that the retirement benefits Americans have been promised are secure. The bipartisan Pension Funding Equity Act of 2003 is a first step toward improving retirement…

Mr. President, as in executive session, I ask unanimous consent that following the vote on passage of the pension rate bill today, the Senate proceed to executive session to consider the following…

Reserving the right to object, we have objections from the majority and minority now on the Finance Committee and also from the majority on the HELP Committee. So based upon that, I object. Is the…
Madam President, before we proceed to the next vote, I do want to make a couple quick comments regarding the schedule. First, I am very pleased with the bipartisan vote on the passage of the pension…
Bill Text
Latest available legislative text
        [Congressional Bills 108th Congress]
[From the U.S. Government Publishing Office]
[S. 1912 Introduced in Senate (IS)]

108th CONGRESS
1st Session
S. 1912

A bill to amend the Internal Revenue Code of 1986 to expand pension
coverage and savings opportunities and to provide other pension
reforms.

_______________________________________________________________________

IN THE SENATE OF THE UNITED STATES

November 21, 2003

Mr. Jeffords (for himself, Ms. Snowe, and Mr. Hatch) introduced the
following bill; which was read twice and referred to the Committee on
Finance

_______________________________________________________________________

A BILL

A bill to amend the Internal Revenue Code of 1986 to expand pension
coverage and savings opportunities and to provide other pension
reforms.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE; AMENDMENT OF 1986 CODE; TABLE OF CONTENTS.

(a) Short Title.--This Act may be cited as the ``Retirement Account
Portability Act of 2003''.
(b) Amendment of 1986 Code.--Except as otherwise expressly
provided, whenever in this Act an amendment or repeal is expressed in
terms of an amendment to, or repeal of, a section or other provision,
the reference shall be considered to be made to a section or other
provision of the Internal Revenue Code of 1986.
(c) Table of Contents.--The table of contents of this Act is as
follows:

Sec. 1. Short title; amendment of 1986 Code; table of contents.
TITLE I--BUILDING AND PRESERVING RETIREMENT ASSETS AND ENHANCING
PORTABILITY

Sec. 101. Allow rollovers by nonspouse beneficiaries of certain
retirement plan distributions.
Sec. 102. Facilitation under fiduciary rules of certain rollovers and
annuity distributions.
Sec. 103. Faster vesting of employer nonelective contributions.
Sec. 104. Allow rollover of after-tax amounts in annuity contracts.
TITLE II--EXPANDING RETIREMENT PLAN COVERAGE TO EMPLOYEES OF SMALL
BUSINESSES

Sec. 201. Elimination of higher penalty on certain Simple
distributions.
Sec. 202. Simple plan portability.
TITLE III--EXPANDING RETIREMENT SAVINGS FOR TAX-EXEMPT ORGANIZATION AND
GOVERNMENT EMPLOYEES

Sec. 301. Clarifications regarding purchase of permissive service
credit.
Sec. 302. Eligibility for participation in retirement plans.
TITLE IV--SIMPLIFICATION AND EQUITY

Sec. 401. Allow direct rollovers from retirement plans to Roth IRAs.
Sec. 402. Transfers to the PBGC.

TITLE I--BUILDING AND PRESERVING RETIREMENT ASSETS AND ENHANCING
PORTABILITY

SEC. 101. ALLOW ROLLOVERS BY NONSPOUSE BENEFICIARIES OF CERTAIN
RETIREMENT PLAN DISTRIBUTIONS.

(a) In General.--
(1) Qualified plans.--Section 402(c) (relating to rollovers
from exempt trusts) is amended by adding at the end the
following new paragraph:
``(11) Distributions to inherited individual retirement
plan of nonspouse beneficiary.--
``(A) In general.--If, with respect to any portion
of a distribution from an eligible retirement plan of a
deceased employee, a direct trustee-to-trustee transfer
is made to an individual retirement plan described in
clause (i) or (ii) of paragraph (8)(B) established for
the purposes of receiving the distribution on behalf of
an individual who is a designated beneficiary (as
defined by section 401(a)(9)(E)) of the employee and
who is not the surviving spouse of the employee--
``(i) the transfer shall be treated as an
eligible rollover distribution for purposes of
this subsection,
``(ii) the individual retirement plan shall
be treated as an inherited individual
retirement account or individual retirement
annuity (within the meaning of section
408(d)(3)(C)) for purposes of this title, and
``(iii) section 401(a)(9)(B) (other than
clause (iv) thereof) shall apply to such plan.
``(B) Certain trusts treated as beneficiaries.--For
purposes of this paragraph, to the extent provided in
rules prescribed by the Secretary, a trust maintained
for the benefit of one or more designated beneficiaries
shall be treated in the same manner as a trust
designated beneficiary.''.
(2) Section 403(a) plans.--Subparagraph (B) of section
403(a)(4) (relating to rollover amounts) is amended by
inserting ``and (11)'' after ``(7)''.
(3) Section 403(b) plans.--Subparagraph (B) of section
403(b)(8) (relating to rollover amounts) is amended by striking
``and (9)'' and inserting ``, (9), and (11)''.
(4) Section 457 plans.--Subparagraph (B) of section
457(e)(16) (relating to rollover amounts) is amended by
striking ``and (9)'' and inserting ``, (9), and (11)''.
(b) Effective Date.--The amendments made by this section shall
apply to distributions after December 31, 2003.

SEC. 102. FACILITATION UNDER FIDUCIARY RULES OF CERTAIN ROLLOVERS AND
ANNUITY DISTRIBUTIONS.

(a) In General.--Section 404(c) of the Employee Retirement Income
Security Act of 1974 (29 U.S.C. 1104(c)) is amended by adding at the
end the following new paragraph:
``(4)(A) In the case of a pension plan which makes a transfer under
section 401(a)(31)(A) of the Internal Revenue Code of 1986 to an
individual retirement plan (as defined in section 7701(a)(37) of such
Code) in connection with a participant or beneficiary or makes a
distribution to a participant or beneficiary of an annuity contract
described in subparagraph (B), the participant or beneficiary shall,
for purposes of paragraph (1), be treated as exercising control over
the transfer or distribution if--
``(i) the participant or beneficiary elected such transfer
or distribution, and
``(ii) in connection with such election, the participant or
beneficiary was given an opportunity to elect any other
individual retirement plan (in the case of a transfer) or any
other annuity contract described in subparagraph (B) (in the
case of a distribution).
``(B) An annuity contract is described in this subparagraph if it
provides, either on an immediate or deferred basis, a series of
substantially equal periodic payments (not less frequently than
annually) for the life of the participant or beneficiary or the joint
lives of the participant or beneficiary and such individual's
designated beneficiary. Annuity payments shall not fail to be treated
as part of a series of substantially equal periodic payments because
the amount of the periodic payments may vary in accordance with
investment experience, reallocations among investment options,
actuarial gains or losses, cost of living indices, or similar
fluctuating criteria. The availability of a commutation benefit, a
minimum period of payments certain, or a minimum amount to be paid in
any event shall not affect the treatment of an annuity contract as an
annuity contract described in this subparagraph.
``(C) Under regulations prescribed by the Secretary, this paragraph
shall apply without regard to whether the particular individual
retirement plan receiving the transfer or the particular annuity
contract being distributed is specifically identified by the pension
plan as available to the participant or beneficiary.
``(D) Notwithstanding the preceding provisions of this paragraph,
paragraph (1)(B) shall not apply with respect to liability under
section 406 in connection with the specific identification of any
individual retirement plan or annuity contract as being available to
the participant or beneficiary.''.
(b) Effective Date and Related Rules.--
(1) Effective date.--The amendment made by this section
shall take effect on the date of the enactment of this Act.
(2) Issuance of final regulations.--Final regulations under
section 404(c)(4) of the Employee Retirement Income Security
Act of 1974 (added by this section) shall be issued no later
than 1 year after the date of the enactment of this Act.

SEC. 103. FASTER VESTING OF EMPLOYER NONELECTIVE CONTRIBUTIONS.

(a) Amendments to the Internal Revenue Code of 1986.--
(1) In general.--Paragraph (2) of section 411(a) (relating
to employer contributions) is amended to read as follows:
``(2) Employer contributions.--
``(A) Defined benefit plans.--
``(i) In general.--In the case of a defined
benefit plan, a plan satisfies the requirements
of this paragraph if it satisfies the
requirements of clause (ii) or (iii).
``(ii) 5-year vesting.--A plan satisfies
the requirements of this clause if an employee
who has completed at least 5 years of service
has a nonforfeitable right to 100 percent of
the employee's accrued benefit derived from
employer contributions.
``(iii) 3 to 7 year vesting.--A plan
satisfies the requirements of this clause if an
employee has a nonforfeitable right to a
percentage of the employee's accrued benefit
derived from employer contributions determined
under the following table:

The nonforfeitable
``Years of service:
percentage is:
3......................................         20
4......................................         40
5......................................         60
6......................................         80
7 or more..............................        100.
``(B) Defined contribution plans.--
``(i) In general.--In the case of a defined
contribution plan, a plan satisfies the
requirements of this paragraph if it satisfies
the requirements of clause (ii) or (iii).
``(ii) 3-year vesting.--A plan satisfies
the requirements of this clause if an employee
who has completed at least 3 years of service
has a nonforfeitable right to 100 percent of
the employee's accrued benefit derived from
employer contributions.
``(iii) 2 to 6 year vesting.--A plan
satisfies the requirements of this clause if an
employee has a nonforfeitable right to a
percentage of the employee's accrued benefit
derived from employer contributions determined
under the following table:

The nonforfeitable
``Years of service:
percentage is:
2......................................         20
3......................................         40
4......................................         60
5......................................         80
6......................................     100.''.
(2) Conforming amendment.--Section 411(a) (relating to
general rule for minimum vesting standards) is amended by
striking paragraph (12).
(b) Amendments to the Employee Retirement Income Security Act of
1974.--
(1) In general.--Paragraph (2) of section 203(a) of the
Employee Retirement Income Security Act of 1974 (29 U.S.C.
1053(a)(2)) is amended to read as follows:
``(2)(A)(i) In the case of a defined benefit plan, a plan
satisfies the requirements of this paragraph if it satisfies
the requirements of clause (ii) or (iii).
``(ii) A plan satisfies the requirements of this clause if
an employee who has completed at least 5 years of service has a
nonforfeitable right to 100 percent of the employee's accrued
benefit derived from employer contributions.
``(iii) A plan satisfies the requirements of this clause if
an employee has a nonforfeitable right to a percentage of the
employee's accrued benefit derived from employer contributions
determined under the following table:

The nonforfeitable
``Years of service:
percentage is:
3......................................         20
4......................................         40
5......................................         60
6......................................         80
7 or more..............................        100.
``(B)(i) In the case of an individual account plan, a plan
satisfies the requirements of this paragraph if it satisfies
the requirements of clause (ii) or (iii).
``(ii) A plan satisfies the requirements of this clause if
an employee who has completed at least 3 years of service has a
nonforfeitable right to 100 percent of the employee's accrued
benefit derived from employer contributions.
``(iii) A plan satisfies the requirements of this clause if
an employee has a nonforfeitable right to a percentage of the
employee's accrued benefit derived from employer contributions
determined under the following table:

The nonforfeitable
``Years of service:
percentage is:
2......................................         20
3......................................         40
4......................................         60
5......................................         80
6......................................     100.''.
(2) Conforming amendment.--Section 203(a) of such Act is
amended by striking paragraph (4).
(c) Effective Dates.--
(1) In general.--Except as provided in paragraph (2), the
amendments made by this section shall apply to contributions
for plan years beginning after December 31, 2003.
(2) Collective bargaining agreements.--In the case of a
plan maintained pursuant to one or more collective bargaining
agreements between employee representatives and one or more
employers ratified before the date of the enactment of this
Act, the amendments made by this section shall not apply to
contributions on behalf of employees covered by any such
agreement for plan years beginning before the earlier of--
(A) the later of--
(i) the date on which the last of such
collective bargaining agreements terminates
(determined without regard to any extension
thereof on or after such date of the
enactment); or
(ii) January 1, 2004; or
(B) January 1, 2006.
(3) Service required.--With respect to any plan, the
amendments made by this section shall not apply to any employee
before the date that such employee has 1 hour of service under
such plan in any plan year to which the amendments made by this
section apply.

SEC. 104. ALLOW ROLLOVER OF AFTER-TAX AMOUNTS IN ANNUITY CONTRACTS.

(a) In General.--Subparagraph (A) of section 402(c)(2) (maximum
amount which may be rolled over) is amended by striking ``and which''
and inserting ``or to an annuity contract described in section 403(b)
and such plan or contract''.
(b) Effective Date.--The amendment made by subsection (a) shall
apply to taxable years beginning after December 31, 2003.

TITLE II--EXPANDING RETIREMENT PLAN COVERAGE TO EMPLOYEES OF SMALL
BUSINESSES

SEC. 201. ELIMINATION OF HIGHER PENALTY ON CERTAIN SIMPLE
DISTRIBUTIONS.

(a) In General.--Subsection (t) of section 72 (relating to 10-
percent additional tax on early distributions from qualified retirement
plans) is amended by striking paragraph (6) and redesignating
paragraphs (7), (8), and (9) as paragraphs (6), (7), and (8),
respectively.
(b) Conforming Amendments.--
(1) Section 72(t)(2)(E) is amended by striking ``paragraph
(7)'' and inserting ``paragraph (6)''.
(2) Section 72(t)(2)(F) is amended by striking ``paragraph
(8)'' and inserting ``paragraph (7)''.
(3) Section 408(d)(3)(G) is amended by striking ``applies''
and inserting ``applied on the day before the date of the
enactment of the Retirement Account Portability Act of 2003)''.
(4) Section 457(a)(2) is amended by striking ``section
72(t)(9)'' and inserting ``section 72(t)(8)''.
(c) Effective Date.--The amendments made by this section shall
apply to years beginning after December 31, 2003.

SEC. 202. SIMPLE PLAN PORTABILITY.

(a) Repeal of Limitation.--Paragraph (3) of section 408(d)
(relating to rollover contributions), as amended by this Act, is
amended by striking subparagraph (G) and redesignating subparagraph (H)
as subparagraph (G).
(b) Section 402(c)(8)(B) is amended by adding at the end the
following new sentence: ``Individual retirement accounts and individual
retirement annuities described in clauses (i) and (ii) shall be treated
as eligible retirement plans without regard to whether they are part of
a simplified employee pension (within the meaning of section 408(k)) or
a simplified retirement account (within the meaning of section
408(p)).''.
(c) Effective Date.--The amendment made by this section shall apply
to years beginning after December 31, 2003.

TITLE III--EXPANDING RETIREMENT SAVINGS FOR TAX-EXEMPT ORGANIZATION AND
GOVERNMENT EMPLOYEES

SEC. 301. CLARIFICATIONS REGARDING PURCHASE OF PERMISSIVE SERVICE
CREDIT.

(a) In General.--Subparagraph (A) of section 457(e)(17) (relating
to trustee-to-trustee transfers to purchase permissive service credit),
and subparagraph (A) of section 403(b)(13) (relating to trustee-to-
trustee transfers to purchase permissive service credit), are both
amended by striking ``section 415(n)(3)(A)'' and inserting ``section
415(n)(3) (without regard to subparagraphs (B) and (C) thereof)''.
(b) Distribution Requirements.--Section 457(e)(17) and section
403(b)(13) are both amended by adding at the end the following
sentence: ``Amounts transferred under this paragraph shall be
distributed solely in accordance with section 401(a) as applicable to
such defined benefit plan.''.
(c) Service Credit.--Clause (ii) of section 415(n)(3)(A) is amended
to read as follows:
``(ii) which relates to benefits with
respect to which such -participant is not
otherwise entitled, and''.
(d) Effective Date.--The amendments made by this section shall take
effect as if included in the amendments made by section 647 of the
Economic Growth and Tax Relief Reconciliation Act of 2001.

SEC. 302. ELIGIBILITY FOR PARTICIPATION IN RETIREMENT PLANS.

An individual shall not be precluded from participating in an
eligible deferred compensation plan by reason of having received a
distribution under section 457(e)(9) of the Internal Revenue Code of
1986, as in effect prior to the enactment of the Small Business Job
Protection Act of 1996.

TITLE IV--SIMPLIFICATION AND EQUITY

SEC. 401. ALLOW DIRECT ROLLOVERS FROM RETIREMENT PLANS TO ROTH IRAS.

(a) In General.--Subsection (e) of section 408A (defining qualified
rollover contribution) is amended to read as follows:
``(e) Qualified Rollover Contribution.--For purposes of this
section, the term `qualified rollover contribution' means a rollover
contribution--
``(1) to a Roth IRA from another such account,
``(2) from an eligible retirement plan, but only if--
``(A) in the case of an individual retirement plan,
such rollover contribution meets the requirements of
section 408(d)(3), and
``(B) in the case of any eligible retirement plan
(as defined in section 402(c)(8)(B) other than clauses
(i) and (ii) thereof), such rollover contribution meets
the requirements of section 402(c), 403(b)(8), or
457(e)(16), as applicable.
For purposes of section 408(d)(3)(B), there shall be disregarded any
qualified rollover contribution from an individual retirement plan
(other than a Roth IRA) to a Roth IRA.''.
(b) Conforming Amendments.--
(1) Section 408A(c)(3)(B) is amended--
(A) in the text by striking ``individual retirement
plan'' and inserting ``an eligible retirement plan (as
defined by section 402(c)(8)(B))'', and
(B) in the heading by striking ``IRA'' and
inserting ``eligible retirement plan''.
(2) Section 408A(d)(3) is amended--
(A) in subparagraph (A) by striking ``section
408(d)(3)'' inserting ``sections 402(c), 403(b)(8),
408(d)(3), and 457(e)(16)'',
(B) in subparagraph (B) by striking ``individual
retirement plan'' and inserting ``eligible retirement
plan (as defined by section 402(c)(8)(B))'',
(C) in subparagraph (D) by striking ``or 6047''
after ``408(i)'',
(D) in subparagraph (D) by striking ``or both'' and
inserting ``persons subject to section 6047(d)(1), or
all of the foregoing persons'', and
(E) in the heading by striking ``IRA'' and
inserting ``eligible retirement plan''.
(c) Effective Date.--The amendments made by this section shall
apply to distributions after December 31, 2003.

SEC. 402. TRANSFERS TO THE PBGC.

(a) Mandatory Distributions to PBGC.--Clause (i) of section
401(a)(31)(B) (relating to general rule for certain mandatory
distributions) is amended by inserting ``to the Pension Benefit
Guaranty Corporation in accordance with section 4050(e) of the Employee
Retirement Income Security Act of 1974 or'' after ``such transfer''.
(b) Tax Treatment of Distributions.--Subparagraph (B) of section
401(a)(31) is amended by adding at the end the following new clause:
``(iii) Income tax treatment of transfers
to pbgc.--For purposes of determining the
income tax treatment relating to transfers to
the Pension Benefit Guaranty Corporation under
clause (i)--
``(I) the transfer of amounts to
the Pension Benefit Guaranty
Corporation pursuant to clause (i)
shall be treated as a transfer to an
individual retirement plan under such
clause, and
``(II) the distribution of such
amounts from the Pension Benefit
Guaranty Corporation shall be treated
as a distribution from an individual
retirement plan.''.
(c) Missing Participants and Beneficiaries.--
(1) In general.--Section 4050 of the Employee Retirement
Income Security Act of 1974 (29 U.S.C. 1350) is amended by
redesignating subsection (c) as subsection (f) and by inserting
after subsection (b) the following new subsections:
``(c) Multiemployer Plans.--The corporation shall prescribe rules
similar to the rules in subsection (a) for multiemployer plans covered
by this title that terminate under section 4041A.
``(d) Plans Not Otherwise Subject to Title.--
``(1) Transfer to corporation.--The plan administrator of a
plan described in paragraph (4) may elect to transfer the
benefits of a missing participant or beneficiary to the
corporation upon termination of the plan.
``(2) Information to the corporation.--To the extent
provided in regulations, the plan administrator of a plan
described in paragraph (4) shall, upon termination of the plan,
provide the corporation information with respect to benefits of
a missing participant or beneficiary if the plan transfers such
benefits--
``(A) to the corporation, or
``(B) to an entity other than the corporation or a
plan described in paragraph (4)(B)(ii).
``(3) Payment by the corporation.--If benefits of a missing
participant or beneficiary were transferred to the corporation
under paragraph (1), the corporation shall, upon location of
the participant or beneficiary, pay to the participant or
beneficiary the amount transferred (or the appropriate survivor
benefit) either--
``(A) in a single sum (plus interest), or
``(B) in such other form as is specified in
regulations of the corporation.
``(4) Plans described.--A plan is described in this
paragraph if--
``(A) the plan is a pension plan (within the
meaning of section 3(2))--
``(i) to which the provisions of this
section do not apply (without regard to this
subsection), and
``(ii) which is not a plan described in
paragraphs (2) through (11) of section 4021(b),
and
``(B) at the time the assets are to be distributed
upon termination, the plan--
``(i) has one or more missing participants
or beneficiaries, and
``(ii) has not provided for the transfer of
assets to pay the benefits of all missing
participants and beneficiaries to another
pension plan (within the meaning of section
3(2)).
``(5) Certain provisions not to apply.--Subsections (a)(1)
and (a)(3) shall not apply to a plan described in paragraph
(4).
``(e) Involuntary Cashouts.--
``(1) Payment by the corporation.--If benefits under a plan
described in paragraph (2) were transferred to the corporation
under section 401(a)(31)(B) of the Internal Revenue Code of
1986, the corporation shall, upon application filed by the
participant or beneficiary with the corporation in such form
and manner as may be prescribed in regulations of the
corporation, pay to the participant or beneficiary the amount
transferred (or the appropriate survivor benefit) either--
``(A) in a single sum (plus interest), or
``(B) in such other form as is specified in
regulations of the corporation.
``(2) Information to the corporation.--To the extent
provided in regulations, the plan administrator of a plan
described in paragraph (3) shall, upon transferred to the
corporation under section 401(a)(31)(B) of such Code, provide
the corporation information with respect to benefits of the
participant or beneficiary so transferred.
``(3) Plans described.--A plan is described in this
paragraph if the plan is a pension plan (within the meaning of
section 3(2))--
``(A) which provides for mandatory distributions
under section 401(a)(31)(B) of the Internal Revenue
Code of 1986, and
``(B) which is not a plan described in paragraphs
(2) through (11) of section 4021(b).
``(4) Certain provisions not to apply.--Subsections (a)(1)
and (a)(3) shall not apply to a plan described in paragraph
(2).''.
(2) Conforming amendments.--Section 206(f) of such Act (29
U.S.C. 1056(f)) is amended--
(A) by striking ``title IV'' and inserting
``section 4050''; and
(B) by striking ``the plan shall provide that,''.
(d) Effective Date.--
(1) Internal revenue code of 1986 provisions.--The
amendments made by subsections (a) and (b) shall take effect as
if included in the amendments made by section 657 of the
Economic Growth and Tax Relief Reconciliation Act of 2001.
(2) Employee retirement income security act of 1974
provisions.--The amendments made by subsection (c) shall apply
to distributions made after final regulations implementing
subsections (c), (d), and (e) of section 4050 of the Employee
Retirement Income Security Act of 1974 (as added by subsection
(c)), respectively, are prescribed.
(3) Regulations.--The Pension Benefit Guaranty Corporation
shall issue regulations necessary to carry out the amendments
made by subsection (c) not later than December 31, 2004.
<all>