Save Act
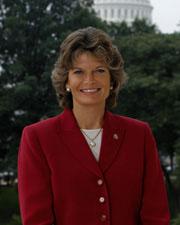 Sen. Lisa Murkowski (R-AK)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Read twice and referred to the Committee on Finance.
October 5, 2004
View full timeline
Introduced in Senate
October 5, 2004
Sponsor introductory remarks on measure. (CR S10442-10443)
October 5, 2004
Read twice and referred to the Committee on Finance.
October 5, 2004
Floor Debate
6 membersWhat members said about S. 2893 on the floor



 +1
Floor Debate
6 membersWhat members said about S. 2893 on the floor
Mr. President, I am pleased to rise today with Senators Snowe, Kennedy, Collins, Murray, Durbin, Lautenberg, Clinton and Johnson to introduce legislation which would supply greatly needed support to…
Mr. President, I am extremely pleased to join my colleague from Connecticut, Senator Dodd, to introduce the Child Care Access Means Parents in School Act of 2004. Senator Dodd and I have worked…
Mr. President, I believe all Americans should have access to affordable, high-quality health care. Rising health care costs impose a burden on families and small businesses and put coverage out of…
Mr. President, I believe all Americans should have access to affordable, high-quality health care. Rising health care costs impose a burden on families and small businesses and put coverage out of…
Mr. President, currently, more than 3,700 children and youth under the age of 13 are living with HIV or AIDS in the United States and of the more than 40,000 Americans newly infected with HIV each…
Show 2 more
Mr. President, it's an honor to introduce the ``Prevention of Childhood Obesity Act''. The goal of this legislation is to deal more effectively with the growing health epidemic of obesity now faced…

Mr. President, I rise today to introduce the Program Assessment and Results Act, or ``PAR Act.'' This bill is a companion bill to H.R. 3826 that Congressman Todd Platts, Chairman of the House…
Bill Text
Latest available legislative text
        [Congressional Bills 108th Congress]
[From the U.S. Government Publishing Office]
[S. 2893 Introduced in Senate (IS)]

108th CONGRESS
2d Session
S. 2893

To amend the Internal Revenue Code of 1986 to allow individuals a
refundable credit against income tax for the purchase of private health
insurance, and for other purposes.

_______________________________________________________________________

IN THE SENATE OF THE UNITED STATES

October 5, 2004

Ms. Murkowski introduced the following bill; which was read twice and
referred to the Committee on Finance

_______________________________________________________________________

A BILL

To amend the Internal Revenue Code of 1986 to allow individuals a
refundable credit against income tax for the purchase of private health
insurance, and for other purposes.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE.

This Act may be cited as the ``Save Act''.

TITLE I--REFUNDABLE HEALTH INSURANCE CREDIT

SEC. 101. REFUNDABLE CREDIT FOR HEALTH INSURANCE COVERAGE.

(a) In General.--Subpart C of part IV of subchapter A of chapter 1
of the Internal Revenue Code of 1986 (relating to refundable credits)
is amended by redesignating section 36 as section 37 and by inserting
after section 35 the following new section:

``SEC. 36. HEALTH INSURANCE COSTS.

``(a) In General.--In the case of an individual, there shall be
allowed as a credit against the tax imposed by this subtitle an amount
equal to the amount paid during the taxable year for qualified health
insurance for the taxpayer, his spouse, and dependents.
``(b) Limitations.--
``(1) In general.--The amount allowed as a credit under
subsection (a) to the taxpayer for the taxable year shall not
exceed the sum of the monthly limitations for coverage months
during such taxable year for each individual referred to in
subsection (a) for whom the taxpayer paid during the taxable
year any amount for coverage under qualified health insurance.
``(2) Phaseout of amount.--
``(A) Reduction based on adjusted gross income.--
The amount determined under paragraph (1) for any
taxable year shall be reduced (but not below zero) by
the amount determined under subparagraph (B).
``(B) Amount of reduction.--The amount determined
under this subparagraph with respect to any amount
determined under paragraph (1) shall be the amount
which bears the same ratio to such amount determined
under paragraph (1) as--
``(i) the excess of--
``(I) the taxpayer's adjusted gross
income for such taxable year, over
``(II) the applicable dollar
amount, bears to
``(ii) $10,000.
The rules of subparagraphs (B) and (C) of section
219(g)(2) shall apply to any reduction under this
subparagraph.
``(C) Definitions.--For purposes of this
paragraph--
``(i) adjusted gross income shall be
determined in the same manner as under section
408A(c)(3)(C)(i), and
``(ii) the applicable dollar amount is--
``(I) in the case of a taxpayer
filing a joint return, an amount equal
to 350 percent of the poverty line (as
defined in section 673(2) of the
Community Services Block Grant Act, for
a family of 4) for the taxable year,
``(II) in the case of any other
taxpayer (other than a married
individual filing a separate return),
350 percent of the poverty line (as so
defined for an individual) for the
taxable year, and
``(III) in the case of a married
individual filing a separate return,
zero.
``(3) Monthly limitation.--
``(A) In general.--The monthly limitation for an
individual for each coverage month of such individual
during the taxable year is the amount equal to \1/12\th
of--
``(i) the base amount, plus
``(ii) 50 percent of the amount paid in
excess of the base amount.
``(B) Base amount.--For purposes of this paragraph,
the base amount is--
``(i) $1,000 if such individual is the
taxpayer,
``(ii) $500 if--
``(I) such individual is the spouse
of the taxpayer,
``(II) the taxpayer and such spouse
are married as of the first day of such
month, and
``(III) the taxpayer files a joint
return for the taxable year, and
``(iii) $500 if such individual is an
individual for whom a deduction under section
151(c) is allowable to the taxpayer for such
taxable year.
``(C) Limitation on number of individuals other
than taxpayer.--Not more than 3 individuals may be
taken into account by the taxpayer under clauses (ii)
and (iii) of subparagraph (B).
``(D) Special rule for married individuals.--In the
case of an individual--
``(i) who is married (within the meaning of
section 7703) as of the close of the taxable
year but does not file a joint return for such
year, and
``(ii) who does not live apart from such
individual's spouse at all times during the
taxable year,
the limitation imposed by subparagraph (C) shall be
divided equally between the individual and the
individual's spouse unless they agree on a different division.
``(4) Coverage month.--For purposes of this subsection--
``(A) In general.--The term `coverage month' means,
with respect to an individual, any month if--
``(i) as of the first day of such month
such individual is covered by qualified health
insurance, and
``(ii) the premium for coverage under such
insurance for such month is paid by the
taxpayer.
``(B) Employer-subsidized coverage.--
``(i) In general.--Such term shall not
include any month for which such individual
participates in any subsidized health plan
(within the meaning of section 162(l)(2))
maintained by any employer of the taxpayer or
of the spouse of the taxpayer.
``(ii) Premiums to nonsubsidized plans.--If
an employer of the taxpayer or the spouse of
the taxpayer maintains a health plan which is
not a subsidized health plan (as so defined)
and which constitutes qualified health
insurance, employee contributions to the plan
shall be treated as amounts paid for qualified
health insurance.
``(C) Cafeteria plan and flexible spending account
beneficiaries.--Such term shall not include any month
during a taxable year if any amount is not includible
in the gross income of the taxpayer for such year under
section 106 with respect to--
``(i) a benefit chosen under a cafeteria
plan (as defined in section 125(d)), or
``(ii) a benefit provided under a flexible
spending or similar arrangement.
``(D) Medicare and medicaid.--Such term shall not
include any month with respect to an individual if, as
of the first day of such month, such individual--
``(i) is entitled to any benefits under
title XVIII of the Social Security Act, or
``(ii) is a participant in the program
under title XIX or XXI of such Act.
``(E) Certain other coverage.--Such term shall not
include any month during a taxable year with respect to
an individual if, at any time during such year, any
benefit is provided to such individual under--
``(i) chapter 89 of title 5, United States
Code,
``(ii) chapter 55 of title 10, United
States Code,
``(iii) chapter 17 of title 38, United
States Code, or
``(iv) any medical care program under the
Indian Health Care Improvement Act.
``(F) Prisoners.--Such term shall not include any
month with respect to an individual if, as of the first
day of such month, such individual is imprisoned under Federal, State,
or local authority.
``(G) Insufficient presence in united states.--Such
term shall not include any month during a taxable year
with respect to an individual if such individual is
present in the United States on fewer than 183 days
during such year (determined in accordance with section
7701(b)(7)).
``(5) Coordination with deduction for health insurance
costs of self-employed individuals.--In the case of a taxpayer
who is eligible to deduct any amount under section 162(l) for
the taxable year, this section shall apply only if the taxpayer
elects not to claim any amount as a deduction under such
section for such year.
``(c) Reduced Credit for Participants in Health Plans of
Employers.--In the case of any individual who participates in a
subsidized health plan (within the meaning of section 162(l)(2))
maintained by any employer of the taxpayer or of the spouse of the
taxpayer (not including a cafeteria plan (as defined in section
125(d)), there shall be allowed to the taxpayer one-half of the credit
that would be allowed to the taxpayer under subsection (a) (determined
without regard to the participation in the health plan) if the monthly
limitation were determined without the addition of the amount described
in subsection (b)(3)(A)(ii).
``(d) Qualified Health Insurance.--For purposes of this section--
``(1) In general.--The term `qualified health insurance'
means insurance which constitutes medical care as defined in
section 213(d) without regard to--
``(A) paragraph (1)(C) thereof, and
``(B) so much of paragraph (1)(D) thereof as
relates to qualified long-term care insurance
contracts.
``(2) Exclusion of certain other contracts.--Such term
shall not include insurance if a substantial portion of its
benefits are excepted benefits (as defined in section 9832(c)).
``(e) Medical Savings Account and Health Savings Account
Contributions.--
``(1) In general.--If a deduction would (but for paragraph
(2)) be allowed under section 220 or 223 to the taxpayer for a
payment for the taxable year to the medical savings account or
health savings account of an individual, subsection (a) shall
be applied by treating such payment as a payment for qualified
health insurance for such individual.
``(2) Denial of double benefit.--No deduction shall be
allowed under section 220 or 223 for that portion of the
payments otherwise allowable as a deduction under section 220
or 223 for the taxable year which is equal to the amount of
credit allowed for such taxable year by reason of this
subsection.
``(f) Special Rules.--
``(1) Coordination with medical expense and high deductible
health plan deductions.--The amount which would (but for this
paragraph) be taken into account by the taxpayer under section
213 or 224 for the taxable year shall be reduced by the credit
(if any) allowed by this section to the taxpayer for such year.
``(2) Denial of credit to dependents.--No credit shall be
allowed under this section to any individual with respect to
whom a deduction under section 151 is allowable to another
taxpayer for a taxable year beginning in the calendar year in
which such individual's taxable year begins.
``(3) Denial of double benefit.--No credit shall be allowed
under subsection (a) if the credit under section 35 is allowed
and no credit shall be allowed under 35 if a credit is allowed
under this section 35.
``(4) Election not to claim credit.--This section shall not
apply to a taxpayer for any taxable year if such taxpayer
elects to have this section not apply for such taxable year.
``(5) Inflation adjustment.--In the case of any taxable
year beginning in a calendar year after 2005, each dollar
amount contained in subsection (b)(3)(B) shall be increased by
an amount equal to--
``(A) such dollar amount, multiplied by
``(B) the cost-of-living adjustment determined
under section 1(f)(3) for the calendar year in which
the taxable year begins, determined by substituting
`calendar year 2004' for `calendar year 1992' in
subparagraph (B) thereof.
Any increase determined under the preceding sentence shall be
rounded to the nearest multiple of $50 ($25 in the case of the
dollar amount in subsection (b)(3)(B)(iii)).''.
(b) Information Reporting.--
(1) In general.--Subpart B of part III of subchapter A of
chapter 61 of such Code (relating to information concerning
transactions with other persons) is amended by inserting after section
6050T the following new section:

``SEC. 6050U. RETURNS RELATING TO PAYMENTS FOR QUALIFIED HEALTH
INSURANCE.

``(a) In General.--Any person who, in connection with a trade or
business conducted by such person, receives payments during any
calendar year from any individual for coverage of such individual or
any other individual under creditable health insurance, shall make the
return described in subsection (b) (at such time as the Secretary may
by regulations prescribe) with respect to each individual from whom
such payments were received.
``(b) Form and Manner of Returns.--A return is described in this
subsection if such return--
``(1) is in such form as the Secretary may prescribe, and
``(2) contains--
``(A) the name, address, and TIN of the individual
from whom payments described in subsection (a) were
received,
``(B) the name, address, and TIN of each individual
who was provided by such person with coverage under
creditable health insurance by reason of such payments
and the period of such coverage, and
``(C) such other information as the Secretary may
reasonably prescribe.
``(c) Creditable Health Insurance.--For purposes of this section,
the term `creditable health insurance' means qualified health insurance
(as defined in section 36(c)) other than--
``(1) insurance under a subsidized group health plan
maintained by an employer, or
``(2) to the extent provided in regulations prescribed by
the Secretary, any other insurance covering an individual if no
credit is allowable under section 36 with respect to such
coverage.
``(d) Statements To Be Furnished to Individuals With Respect to
Whom Information Is Required.--Every person required to make a return
under subsection (a) shall furnish to each individual whose name is
required under subsection (b)(2)(A) to be set forth in such return a
written statement showing--
``(1) the name and address of the person required to make
such return and the phone number of the information contact for
such person,
``(2) the aggregate amount of payments described in
subsection (a) received by the person required to make such
return from the individual to whom the statement is required to
be furnished, and
``(3) the information required under subsection (b)(2)(B)
with respect to such payments.
The written statement required under the preceding sentence shall be
furnished on or before January 31 of the year following the calendar
year for which the return under subsection (a) is required to be made.
``(e) Returns Which Would Be Required To Be Made by 2 or More
Persons.--Except to the extent provided in regulations prescribed by
the Secretary, in the case of any amount received by any person on
behalf of another person, only the person first receiving such amount
shall be required to make the return under subsection (a).''.
(2) Assessable penalties.--
(A) Subparagraph (B) of section 6724(d)(1) of such
Code (relating to definitions) is amended by
redesignating clauses (xii) through (xviii) as clauses
(xiii) through (xix), respectively, and by inserting
after clause (xi) the following new clause:
``(xii) section 6050U (relating to returns
relating to payments for qualified health
insurance),''.
(B) Paragraph (2) of section 6724(d) of such Code
is amended by striking ``or'' at the end of the next to
last subparagraph, by striking the period at the end of
the last subparagraph and inserting ``, or'', and by
adding at the end the following new subparagraph:
``(CC) section 6050U(d) (relating to returns
relating to payments for qualified health
insurance).''.
(3) Clerical amendment.--The table of sections for subpart
B of part III of subchapter A of chapter 61 of such Code is
amended by inserting after the item relating to section 6050T
the following new item:

``Sec. 6050U. Returns relating to
payments for qualified health
insurance.''.
(c) Conforming Amendments.--
(1) Paragraph (2) of section 1324(b) of title 31, United
States Code, is amended by inserting before the period ``, or
from section 36 of such Code''.
(2) The table of sections for subpart C of part IV of
subchapter A of chapter 1 of the Internal Revenue Code of 1986
is amended by striking the last item and inserting the
following new items:

``Sec. 36. Health insurance costs.
``Sec. 37. Overpayments of tax.''.
(d) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2004.

SEC. 102. ADVANCE PAYMENT OF CREDIT FOR PURCHASERS OF QUALIFIED HEALTH
INSURANCE.

(a) In General.--Chapter 77 of the Internal Revenue Code of 1986
(relating to miscellaneous provisions) is amended by adding at the end
the following new section:

``SEC. 7528. ADVANCE PAYMENT OF HEALTH INSURANCE CREDIT FOR PURCHASERS
OF QUALIFIED HEALTH INSURANCE.

``(a) General Rule.--In the case of an eligible individual, the
Secretary shall make payments to the provider of such individual's
qualified health insurance equal to such individual's qualified health
insurance credit advance amount with respect to such provider.
``(b) Eligible Individual.--For purposes of this section, the term
`eligible individual' means any individual--
``(1) who purchases qualified health insurance (as defined
in section 36(c)), and
``(2) for whom a qualified health insurance credit
eligibility certificate is in effect.
``(c) Qualified Health Insurance Credit Eligibility Certificate.--
For purposes of this section, a qualified health insurance credit
eligibility certificate is a statement furnished by an individual to
the Secretary which--
``(1) certifies that the individual will be eligible to
receive the credit provided by section 36 for the taxable year,
``(2) estimates the amount of such credit for such taxable
year, and
``(3) provides such other information as the Secretary may
require for purposes of this section.
``(d) Qualified Health Insurance Credit Advance Amount.--For
purposes of this section, the term `qualified health insurance credit
advance amount' means, with respect to any provider of qualified health
insurance, the Secretary's estimate of the amount of credit allowable
under section 36 to the individual for the taxable year which is
attributable to the insurance provided to the individual by such
provider.
``(e) Regulations.--The Secretary shall prescribe such regulations
as may be necessary to carry out the purposes of this section,
including regulations modifying recapture rules for any overpayment of
the qualified health insurance credit advance amount which equals at
least 2 percent of the taxpayer's adjusted gross income for the taxable
year by allowing periodic payments in lieu of a lump-sum payment for
any such taxpayer whose savings and income warrant such
modification.''.
(b) Clerical Amendment.--The table of sections for chapter 77 of
such Code is amended by adding at the end the following new item:

``Sec. 7528. Advance payment of health
insurance credit for purchasers
of qualified health
insurance.''.
(c) Effective Date.--The amendments made by this section shall
apply to taxable year beginning after the date of the enactment of this
Act.

TITLE II--HEALTH SAVINGS ACCOUNTS

SEC. 201. DEDUCTION OF PREMIUMS FOR HIGH DEDUCTIBLE HEALTH PLANS.

(a) In General.--Part VII of subchapter B of chapter 1 of the
Internal Revenue Code of 1986 (relating to additional itemized
deductions for individuals) is amended by redesignating section 224 as
section 225 and by inserting after section 223 the following new
section:

``SEC. 224. PREMIUMS FOR HIGH DEDUCTIBLE HEALTH PLANS.

``(a) Deduction Allowed.--In the case of an individual, there shall
be allowed as a deduction for the taxable year the aggregate amount
paid by such individual as premiums under a high deductible health plan
with respect to months during such year for which such individual is an
eligible individual with respect to such health plan.
``(b) Definitions.--For purposes of this section--
``(1) Eligible individual.--The term `eligible individual'
has the meaning given such term by section 223(c)(1).
``(2) High deductible health plan.--The term `high
deductible health plan' has the meaning given such term by
section 223(c)(2).
``(c) Special Rules.--
``(1) Deduction allowable for only 1 plan.--For purposes of
this section, in the case of an individual covered by more than
1 high deductible health plan for any month, the individual may
only take into account amounts paid for 1 of such plans for
such month.
``(2) Employer provided coverage.--
``(A) In general.--No deduction shall be allowed to
an individual under subsection (a) for any amount paid
for coverage under a high deductible health plan for a
month if that individual participates in any coverage
for such month that is excluded (in whole or in
part) from the gross income of the individual or the individual's
spouse under section 106.
``(B) Cafeteria plans, etc.--Employer contributions
to a cafeteria plan or a flexible spending or similar
arrangement which are excluded from gross income under
section 106 shall be treated for purposes of this
section as paid by the employer.
``(3) Contributions to health savings account required.--A
deduction shall not be allowed under subsection (a) for a
taxable year with respect to such individual if such individual
is not allowed a deduction under section 223 for such taxable
year.
``(4) Medical and health savings accounts.--Subsection (a)
shall not apply with respect to any amount which is paid or
distributed out of an Archer MSA or a health savings account
which is not included in gross income under section 220(f) or
223(f), as the case may be.
``(5) Coordination with deduction for health insurance of
self-employed individuals.--The amount taken into account by
the taxpayer in computing the deduction under section 162(l)
shall not be taken into account under this section.
``(6) Coordination with medical expense deduction.--The
amount taken into account by the taxpayer in computing the
deduction under this section shall not be taken into account
under section 213.''.
(b) Deduction Allowed Whether or not Individual Itemizes Other
Deductions.--Subsection (a) of section 62 of such Code is amended by
inserting after paragraph (19) the following new paragraph:
``(20) Premiums for high deductible health plans.--The
deduction allowed by section 224.''.
(c) Clerical Amendment.--The table of sections for part VII of
subchapter B of chapter 1 of such Code is amended by striking the last
item and inserting the following new items:

``Sec. 224. Premiums for high deductible health plans.
``Sec. 225. Cross reference.''.
(d) Effective Date.--The amendments made by this section shall
apply to taxable years beginning after December 31, 2004.

SEC. 202. CREDIT FOR CONTRIBUTIONS TO HEALTH SAVINGS ACCOUNTS OF SMALL
BUSINESS EMPLOYEES.

(a) In General.--Subpart D of part IV of subchapter A of chapter 1
of the Internal Revenue Code of 1986 (relating to business related
credits) is amended by adding at the end the following new section:

``SEC. 45G. SMALL EMPLOYER CONTRIBUTIONS TO HEALTH SAVINGS ACCOUNTS.

``(a) General Rule.--For purposes of section 38, in the case of an
eligible employer, the small employer HSA contribution credit
determined under this section for any taxable year with respect to each
employee who is an eligible individual (as defined in section
223(c)(1)) is an amount equal to the lesser of--
``(1) the amount contributed by such employer to any health
savings account (as defined in section 223(d) of such employee
during the taxable year, or
``(2) $200 ($500, if such employee has family coverage
under a high deductible health plan (as defined in section
223(c)(2)).
``(b) Eligible Employer.--For purposes of this section, the term
`eligible employer' means, with respect to any taxable year, an
employer which had no more than 100 employees who received at least
$5,000 of compensation from the employer for the preceding taxable
year.
``(c) Special Rules.--For purposes of this section--
``(1) Aggregation rules.--All persons treated as a single
employer under subsection (a) or (b) of section 52, or
subsection (n) or (o) of section 414, shall be treated as one
person.
``(2) Disallowance of deduction.--No deduction shall be
allowed for that portion of contributions to any health savings
accounts for the taxable year which is equal to the credit
determined under subsection (a).
``(3) Election not to claim credit.--This section shall not
apply to a taxpayer for any taxable year if such taxpayer
elects to have this section not apply for such taxable year.''.
(b) Credit Allowed as Part of General Business Credit.--Section
38(b) of such Code (defining current year business credit) is amended
by striking ``plus'' at the end of paragraph (14), by striking the
period at the end of paragraph (15) and inserting ``, plus'', and by
adding at the end the following new paragraph:
``(16) in the case of an eligible employer (as defined in
section 45G(b)), the small employer HSA contribution credit
determined under section 45G(a).''.
(c) Conforming Amendments.--
(1) Section 39(d) of such Code is amended by adding at the
end the following new paragraph:
``(11) No carryback of small employer hsa contribution
credit before january 1, 2005.--No portion of the unused
business credit for any taxable year which is attributable to
the small employer HSA contribution credit determined under
section 45G may be carried back to a taxable year beginning
before January 1, 2005.''.
(2) Subsection (c) of section 196 of such Code is amended
by striking ``and'' at the end of paragraph (9), by striking
the period at the end of paragraph (10) and inserting ``,
and'', and by adding at the end the following new paragraph:
``(11) the small employer HSA contribution credit
determined under section 45G(a).''.
(3) The table of sections for subpart D of part IV of
subchapter A of chapter 1 of such Code is amended by adding at
the end the following new item:

``Sec. 45G. Small employer contributions
to health savings accounts.''.
(d) Effective Date.--The amendments made by this section shall
apply to contributions made in taxable years beginning after December
31, 2004.

TITLE III--STATE HIGH RISK POOLS

SEC. 301. SHORT TITLE.

This title may be cited as the ``State High Risk Pool Funding
Extension Act of 2004''.

SEC. 302. EXTENSION OF FUNDING FOR OPERATION OF STATE HIGH RISK HEALTH
INSURANCE POOLS.

Section 2745 of the Public Health Service Act (42 U.S.C. 300gg-45)
is amended to read as follows:

``SEC. 2745. PROMOTION OF QUALIFIED HIGH RISK POOLS.

``(a) Extension of Seed Grants to States.--The Secretary shall
provide from the funds appropriated under subsection (d)(1)(A) a grant
of up to $1,000,000 to each State that has not created a qualified high
risk pool as of the date of the enactment of this section for the
State's costs of creation and initial operation of such a pool.
``(b) Grants for Operational Losses.--
``(1) In general.--In the case of a State that has
established a qualified high risk pool that--
``(A) restricts premiums charged under the pool to
no more than 150 percent of the premium for applicable
standard risk rates;
``(B) offers a choice of two or more coverage
options through the pool; and
``(C) has in effect a mechanism reasonably designed
to ensure continued funding of losses incurred by the
State after the end of fiscal year 2004 in connection
with operation of the pool;
the Secretary shall provide, from the funds appropriated under
subsection (d)(1)(B)(i) and allotted to the State under
paragraph (2), a grant for the losses incurred by the State in
connection with the operation of the pool.
``(2) Allotment.--The amounts appropriated under subsection
(d)(1)(B)(i) for a fiscal year shall be made available to the
States (or the entities that operate the high risk pool under
applicable State law) as follows:
``(A) An amount equal to 50 percent of the
appropriated amount for the fiscal year shall be
allocated in equal amounts among each eligible State
that applies for assistance under this subsection.
``(B) An amount equal to 25 percent of the
appropriated amount for the fiscal year shall be
allocated among the States so that the amount provided
to a State bears the same ratio to such available
amount as the number of uninsured individuals in the
State bears to the total number of uninsured
individuals in all States (as determined by the
Secretary).
``(C) An amount equal to 25 percent of the
appropriated amount for the fiscal year shall be
allocated among the States so that the amount provided
to a State bears the same ratio to such available
amount as the number of individuals enrolled in health
care coverage through the qualified high risk pool of
the State bears to the total number of individuals so
enrolled through qualified high risk pools in all
States (as determined by the Secretary).
``(c) Bonus Grants for Supplemental Consumer Benefits.--
``(1) In general.--In the case of a State that has
established a qualified high risk pool, the Secretary shall
provide, from the funds appropriated under subsection
(d)(1)(B)(ii), a grant to be used to provide supplemental
consumer benefits to enrollees or potential enrollees (or
defined subsets of such enrollees or potential enrollees) in
qualified high risk pools.
``(2) Benefits.--A State shall use amounts received under a
grant under this subsection to provide one or more of the
following benefits:
``(A) Low-income premium subsidies.
``(B) A reduction in premium trends, actual
premiums, or other cost-sharing requirements.
``(C) An expansion or broadening of the pool of
individuals eligible for coverage, including
eliminating waiting lists, increasing enrollment caps,
or providing flexibility in enrollment rules.
``(D) Less stringent rules, or additional waiver
authority, with respect to coverage of pre-existing
conditions.
``(E) Increased benefits.
``(F) The establishment of disease management
programs.
``(3) Limitation.--In allotting amounts under this
subsection, the Secretary shall ensure that no State receives
an amount that exceeds 10 percent of the amount appropriated
for the fiscal year involved under subsection (d)(1)(B)(ii).
``(4) Rule of construction.--Nothing in this subsection
shall be construed to prohibit States that, on the date of
enactment of the State High Risk Pool Funding Extension Act of
2004, are in the process of implementing programs to provide
benefits of the type described in paragraph (2), from being
eligible for a grant under this subsection.
``(d) Funding.--
``(1) In general.--Out of any money in the Treasury of the
United States not otherwise appropriated, there are authorized
and appropriated--
``(A) $15,000,000 for the period of fiscal years
2004 and 2005 to carry out subsection (a); and
``(B) $75,000,000 for each of fiscal years 2005
through 2009, of which--
``(i) two-thirds of the amount appropriated
for a fiscal year shall be made available for
allotments under subsection (b)(2); and
``(ii) one-third of the amount appropriated
for a fiscal year shall be made available for
allotments under subsection (c)(2).
``(2) Availability.--Funds appropriated under this
subsection for a fiscal year shall remain available for
obligation through the end of the following fiscal year.
``(3) Reallotment.--If, on June 30 of each fiscal year, the
Secretary determines that all amounts appropriated under
paragraph (1)(B)(ii) for the fiscal year will not be allotted,
such remaining amounts shall be allotted among States receiving
grants under subsection (b) for the fiscal year in amounts
determined pursuant to the formula under subsection (b)(2).
``(4) No entitlement.--Nothing in this section shall be
construed as providing a State with an entitlement to a grant
under this section.
``(e) Applications.--To be eligible for a grant under this section,
a State shall submit to the Secretary an application at such time, in
such manner, and containing such information as the Secretary may
require.
``(f) Definitions.--In this section:
``(1) Qualified high risk pool.--
``(A) In general.--The term `qualified high risk
pool' has the meaning given such term in section
2744(c)(2), except that with respect to subparagraph
(A) of such section a State may elect to provide for
the enrollment of eligible individuals through--
``(i) a combination of a qualified high
risk pool and an acceptable alternative
mechanism; or
``(ii) other health insurance coverage
described in subparagraph (B).
``(B) Health insurance coverage.--Health insurance
coverage described in this subparagraph is individual
health insurance coverage--
``(i) that meets the requirements of
section 2741;
``(ii) that is subject to limits on the
rates charged to individuals;
``(iii) that is available to all
individuals eligible for health insurance
coverage under this title who are not able to
participate in a qualified high risk pool; and
``(iv) the defined rate limit of which does
not exceed the limit allowed for a qualified
risk pool that is otherwise eligible to receive
assistance under a grant under this section.
``(C) Other coverage.--In addition to coverage
described in subparagraph (B), a State may provide for
the offering of health insurance coverage that provides
first dollar coverage, limits on cost-sharing, and comprehensive
medical, hospital and surgical coverage, if the limits on rates for
such coverage do not exceed the limit described in subparagraph (B)(iv)
by more than 25 percentage points.
``(2) Standard risk rate.--The term `standard risk rate'
means a rate--
``(A) determined under the State high risk pool by
considering the premium rates charged by other health
insurers offering health insurance coverage to
individuals in the insurance market served;
``(B) that is established using reasonable
actuarial techniques; and
``(C) that reflects anticipated claims experience
and expenses for the coverage involved.
``(3) State.--The term `State' means any of the 50 States
and the District of Columbia.''.

TITLE IV--VOLUNTARY CHOICE COOPERATIVES

SEC. 401. GRANTS FOR THE ESTABLISHMENT AND OPERATION OF COOPERATIVES.

Subpart 1 of part B of title XXVII of the Public Health Service Act
(42 U.S.C. 300gg-41 et seq.) is amended by adding at the end thereof
the following:

``SEC. 2746. GRANTS FOR THE ESTABLISHMENT AND OPERATION OF
COOPERATIVES.

``(a) In General.--The Secretary may award grants to States for the
establishment and operation of health insurance purchasing cooperatives
that meet the requirements of subsection (c).
``(b) Use of Funds.--Amounts provided under a grant under
subsection (a) shall be used--
``(1) for the establishment and operation of health
insurance purchasing cooperatives that meet the requirements of
this section;
``(2) for the support and training of the professional
staff of the cooperative;
``(3) in the case of a State that is not operating a health
insurance purchasing cooperative on the date on which an
application for a grant under this section is submitted by the
State, for the conduct of a feasibility study relating to the
proposed activities of the cooperative; and
``(4) for other activities determined appropriate by the
Secretary; and
``(c) Requirements of Cooperatives.--To be eligible to receive a
grant under subsection (a), a State shall demonstrate to the Secretary
that the purchasing cooperative to be established or operated under the
grant--
``(1) has a membership consisting solely of at least two
eligible employers;
``(2) is a nonprofit entity certified under State law;
``(3) is organized as an independent health insurance
purchasing entity with a commission that meets requirements
similar to the requirements imposed with respect to the
administration of State high risk pools that receive funds
under section 2745;
``(4) is wholly owned and administered by the members of
the cooperative;
``(5) accepts all eligible employers within the area served
by the cooperative as members if such employers request such
membership;
``(6) provides assistance to the members in pooling the
health insurance purchasing power of such members;
``(7) provides for the collection and distribution of data,
and the conduct of other activities, to improve the quality of
health care decisionmaking; and
``(8) meets such other requirements as the Secretary
determines appropriate.
``(d) Duties of Cooperatives.--Each health insurance purchasing
cooperative that receive funds under this section shall--
``(1) enter into agreements with insurers offering health
insurance coverage that meets the guidelines developed under
subsection (e);
``(2) enter into agreements with member eligible employers
to provide insurance through the cooperative to the employees
of such employers;
``(3) enroll only eligible employees and their families;
``(4) provide enrollee information to the State; and
``(5) carry out other functions provided for by the
Secretary.
``(e) Qualifying Health Insurance Coverage.--For purposes of this
section, qualifying health insurance coverage shall be coverage that
is--
``(1) fully insured;
``(2) approved by the department of insurance for the State
in which the coverage is offered; and
``(3) creditable coverage as described in section
2701(c)(1).
``(f) Eligible Employers.--In this section, the term `eligible
employer' means an employer--
``(1) that employs 100 or fewer employees (as determined in
accordance with section 2791(e)(6)); or
``(2) regardless of size, that self insures.
``(g) Authorization of Appropriations.--There is authorized to be
appropriated, such sums as may be necessary to carry out this
section.''.
<all>