Military Personnel Financial Services Protection Act
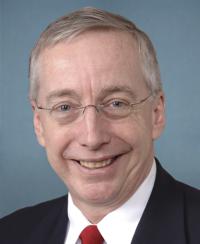 Rep. Geoff Davis (R-KY)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Received in the Senate and Read twice and referred to the Committee on Banking, Housing, and Urban Affairs.
June 28, 2005
View full timeline
Introduced in House
February 1, 2005
Referred to the House Committee on Financial Services.
February 1, 2005
Committee Consideration and Mark-up Session Held.
March 16, 2005
Reported by the Committee on Financial Services. H. Rept. 109-40.
April 13, 2005
Placed on the Union Calendar, Calendar No. 21.
April 13, 2005
Mr. Davis (KY) moved to suspend the rules and pass the bill, as amended.
June 27, 2005 • 2:45 PM
Considered under suspension of the rules. (consideration: CR H5186-5192)
June 27, 2005 • 2:45 PM
DEBATE - The House proceeded with forty minutes of debate on H.R. 458.
June 27, 2005 • 2:46 PM
At the conclusion of debate, the Yeas and Nays were demanded and ordered. Pursuant to the provisions of clause 8, rule XX, the Chair announced that further proceedings on the motion would be postponed.
June 27, 2005 • 2:46 PM
Considered as unfinished business. (consideration: CR H5273-5274)
June 28, 2005 • 11:54 AM
Passed/agreed to in House: On motion to suspend the rules and pass the bill, as amended Agreed to by the Yeas and Nays: (2/3 required): 405 - 2 (Roll no. 324).(text: CR 6/27/2005 H5186-5192)
June 28, 2005 • 12:17 PM
On motion to suspend the rules and pass the bill, as amended Agreed to by the Yeas and Nays: (2/3 required): 405 - 2 (Roll no. 324). (text: CR 6/27/2005 H5186-5192)
June 28, 2005 • 12:17 PM
Motion to reconsider laid on the table Agreed to without objection.
June 28, 2005 • 12:17 PM
The title of the measure was amended. Agreed to without objection.
June 28, 2005 • 12:17 PM
Received in the Senate and Read twice and referred to the Committee on Banking, Housing, and Urban Affairs.
June 28, 2005
Voting History
1 vote recorded • Roll call available
Floor Debate
20 membersWhat members said about H.R. 458 on the floor


 +15
Floor Debate
20 membersWhat members said about H.R. 458 on the floor
Mr. Speaker, I move to suspend the rules and pass the Senate bill (S. 418) to protect members of the Armed Forces from unscrupulous practices regarding sales of insurance, financial, and investment…
Mr. Speaker, I yield myself such time as I may consume. First, let me extend my deep appreciation and thanks to our distinguished chairman, Chairman Oxley of Ohio. As many of us know, Chairman Oxley…
Mr. Speaker, I move to suspend the rules and pass the bill (H.R. 458) to prevent the sale of abusive insurance and investment products to military personnel, as amended. Mr. Speaker, I ask unanimous…
Mr. Speaker, I strongly support the Military Personnel Financial Services Protection Act, H.R. 458. We passed this bill last year, and it is designed to prevent predatory companies from using the…
Mr. Speaker, I rise in support of S. 418, the Military Personnel Financial Services Protection Act, which protects the men and women serving in our Nation's military from deceptive financial…
Show 8 more
Mr. Speaker, I rise today to strongly support H.R. 458, the Military Personnel Financial Services Protection Act, and specifically to highlight Title II of this very important legislation. Title II…
Mr. Speaker, I rise in support of H.R. 458, the Military Personnel Financial Services Protection Act. This bill, introduced by my good friend Mr. Geoff Davis from the Commonwealth of Kentucky, will…

Mr. Speaker, I thank my friend for yielding. In a prior life I used to be a State insurance commissioner, and I want to tell you how completely disgusted I am that there are still companies and…

Mr. Speaker, I yield myself such time as I may consume. The gentleman from Kentucky has quite correctly described both the need for this bill and what it does, and I am very pleased that this is one…
Mr. Speaker, I rise today to speak in support of H.R. 458, the Military Personnel Financial Services Protection Act of 2005. I congratulate Chairman Oxley and all the members of the Financial…
Mr. Speaker, today, I rise in support of Title II in my legislation, H.R. 458. Title II regulates so-called ``military lenders,'' and provides significant safeguards to protect our armed services…
Mr. Speaker, I rise in strong support of H.R. 458, the Military Personnel Financial Services Protection Act. H.R. 458 is identical to legislation passed by the House of Representatives by a vote of…
Mr. Speaker, Title Two of H.R. 458 is most important to those of us who represent districts with a heavy military presence. It regulates so-called ``military lenders,'' and protects servicemembers…
Show 11 more
Mr. Speaker, today we are considering S. 418, the Military Personnel Financial Services Protection Act. At a time when so many of our brave men and women are deployed across the world defending our…
Mr. Speaker, I wish to express my strong support for H.R. 458, the Military Personnel Financial Services Protection Act. This legislation protects the men and women of our armed forces from predatory…
Mr. Speaker, today, I rise in support of Title II of, H.R. 458 Military Personnel Financial Services Protection Act. Title II of this measure regulates lenders who target the military and safeguards…
Mr. Speaker, I rise today in strong support of Title II of H.R. 458. This provision protects our service men and women from the predatory practices of high cost military lenders. Companies such as…
Mr. Speaker, I rise in support of this bill, to defend those who defend us. Our young men and women in uniform should not be prey to unscrupulous types who take advantage of their inexperience, in…
Mr. Speaker, earlier this week, the House passed H.R. 458, the Military Personnel Financial Services Protection Act. This important piece of legislation prevents the sale of abusive insurance and…
Mr. Speaker, I rise today in support of Title II of H.R. 458, the Military Personnel Financial Services Protection Act. This bill helps protect our troops and other military personnel from predatory…
Mr. Speaker, I rise today to strongly support Title II of H.R. 458, the Military Personnel Financial Services Protection Act. Title II's provisions are especially important as they will help prevent…
Mr. Speaker, due to a family medical emergency, I missed rollcall votes 308 through 325, which took place on Friday, Monday, and Tuesday--June 24, 27, and 28, 2005, respectively. Had I been present,…
Mr. Speaker, I rise today in favor of H.R. 458, the Military Personnel Financial Services Protection Act. This legislation, sponsored by the gentleman from Kentucky, would establish procedures to…
Mr. Speaker, I was absent from 12:00 p.m. until 7:00 p.m. on June 28, 2005. The reason for my absence was that I was required to testify before the Regional BRAC Commission hearing in Charlotte,…
Bill Text
4 versions available
        [Congressional Bills 109th Congress]
[From the U.S. Government Publishing Office]
[H.R. 458 Referred in Senate (RFS)]

1st Session
H. R. 458

_______________________________________________________________________

IN THE SENATE OF THE UNITED STATES

June 28, 2005

Received; read twice and referred to the Committee on Banking, Housing,
and Urban Affairs

_______________________________________________________________________

AN ACT

To prevent the sale of abusive insurance and investment products to
military personnel, and for other purposes.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE; TABLE OF CONTENTS.

(a) Short Title.--This Act may be cited as the ``Military Personnel
Financial Services Protection Act''.
(b) Table of Contents.--The table of contents for this Act is as
follows:

Sec. 1. Short title; table of contents.
TITLE I--INSURANCE AND INVESTMENT PRODUCTS

Sec. 101. Congressional findings.
Sec. 102. Prohibition on future sales of periodic payment plans.
Sec. 103. Method of maintaining broker/dealer registration,
disciplinary, and other data.
Sec. 104. Filing depositories for investment advisers.
Sec. 105. State insurance and securities jurisdiction on military
installations.
Sec. 106. Required development of military personnel protection
standards regarding insurance sales.
Sec. 107. Required disclosures regarding life insurance.
Sec. 108. Improving life insurance product standards.
Sec. 109. Required reporting of disciplined insurance producers.
Sec. 110. Reporting barred persons engaging in financial services
activities.
Sec. 111. Sense of Congress.
Sec. 112. Definitions.
TITLE II--LENDING TO ARMED FORCES PERSONNEL

Sec. 201. Requirements applicable to certain loans to military
servicemembers.

TITLE I--INSURANCE AND INVESTMENT PRODUCTS

SEC. 101. CONGRESSIONAL FINDINGS.

The Congress finds the following:
(1) Our military personnel perform great sacrifices in
protecting our Nation in the War on Terror and promoting
democracy abroad.
(2) Our brave men and women in uniform deserve to be
offered first-rate financial products in order to provide for
their families and to save and invest for retirement.
(3) Our military personnel are being offered high-cost
securities and life insurance products by some financial
services companies engaging in abusive and misleading sales
practices.
(4) One securities product being offered to our service
members, the contractual plan, has largely disappeared from the
civilian market since the 1980s due to its excessive sales
charges and the emergence of low-cost products. A 50-percent
sales commission is typically assessed against the first year
of contributions made under a contractual plan, even though the
average commission on other securities products such as mutual
funds is less than 6 percent on each sale.
(5) The excessive sales charge of the contractual plan
makes it susceptible to abusive and misleading sales practices.
(6) Certain life insurance products being offered to our
service members are being improperly marketed as investment
products. These products provide very low death benefits for
very high premiums that are front-loaded in the first few
years, making them completely inappropriate for most military
personnel.
(7) Regulation of these securities and life insurance
products and their sale on military bases has been clearly
inadequate and requires Congressional legislation to address.

SEC. 102. PROHIBITION ON FUTURE SALES OF PERIODIC PAYMENT PLANS.

(a) Amendment.--Section 27 of the Investment Company Act of 1940
(15 U.S.C. 80a-27) is amended by adding at the end the following new
subsection:
``(j) Termination of Sales.--
``(1) Termination.--Effective 30 days after the date of
enactment of the Military Personnel Financial Services
Protection Act, it shall be unlawful, subject to subsection
(i)--
``(A) for any registered investment company to
issue any periodic payment plan certificate; or
``(B) for such company, or any depositor of or
underwriter for any such company, or any other person,
to sell such a certificate.
``(2) No invalidation of existing certificates.--Paragraph
(1) shall not be construed to alter, invalidate, or otherwise
affect any rights or obligations, including rights of
redemption, under any periodic payment plan certificate issued
and sold before 30 days after such date of enactment.''.
(b) Technical Amendment.--Section 27(i)(2)(B) of such Act is
amended by striking ``section 26(e)'' each place it appears and
inserting ``section 26(f)''.
(c) Report on Refunds, Sales Practices, and Revenues From Periodic
Payment Plans.--Within 6 months after the date of enactment of this
Act, the Securities and Exchange Commission shall submit to the
Committee on Financial Services of the House of Representatives and the
Committee on Banking, Housing, and Urban Affairs of the Senate, a
report describing--
(1) any measures taken by a broker or dealer registered
with the Securities and Exchange Commission pursuant to section
15(b) of the Securities Exchange Act of 1934 (15 U.S.C. 78o(b))
to voluntarily refund payments made by military service members
on any periodic payment plan certificate, and the amounts of
such refunds;
(2) after such consultation with the Secretary of Defense
as the Commission considers appropriate, the sales practices of
such brokers or dealers on military installations over the past
5 years and any legislative or regulatory recommendations to
improve such practices; and
(3) the revenues generated by such brokers or dealers in
the sales of periodic payment plan certificates over the past 5
years and what products such brokers or dealers market to
replace the revenue generated from the sales of periodic
payment plan certificates prohibited under subsection (a) of
this section.

SEC. 103. METHOD OF MAINTAINING BROKER/DEALER REGISTRATION,
DISCIPLINARY, AND OTHER DATA.

Subsection (i) of section 15A of the Securities Exchange Act of
1934 (15 U.S.C. 78o-3(i)) is amended to read as follows:
``(i) Obligation to Maintain Registration, Disciplinary, and Other
Data.--
``(1) Maintenance of system to respond to inquiries.--A
registered securities association shall--
``(A) establish and maintain a system for
collecting and retaining registration information;
``(B) establish and maintain a toll-free telephone
listing, and a readily accessible electronic or other
process, to receive and promptly respond to inquiries
regarding--
``(i) registration information on its
members and their associated persons; and
``(ii) registration information on the
members and their associated persons of any
registered national securities exchange that
uses the system described in subparagraph (A)
for the registration of its members and their
associated persons; and
``(C) adopt rules governing the process for making
inquiries and the type, scope, and presentation of
information to be provided in response to such
inquiries in consultation with any registered national
securities exchange providing information pursuant to
subparagraph (B)(ii).
``(2) Recovery of costs.--Such an association may charge
persons making inquiries, other than individual investors,
reasonable fees for responses to such inquiries.
``(3) Process for disputed information.--Such an
association shall adopt rules establishing an administrative
process for disputing the accuracy of information provided in
response to inquiries under this subsection in consultation
with any registered national securities exchange providing
information pursuant to paragraph (1)(B)(ii).
``(4) Limitation of liability.--Such an association, or an
exchange reporting information to such an association, shall
not have any liability to any person for any actions taken or
omitted in good faith under this subsection.
``(5) Definition.--For purposes of this subsection, the
term `registration information' means the information reported
in connection with the registration or licensing of brokers and
dealers and their associated persons, including disciplinary
actions, regulatory, judicial, and arbitration proceedings, and
other information required by law, or exchange or association
rule, and the source and status of such information.''.

SEC. 104. FILING DEPOSITORIES FOR INVESTMENT ADVISERS.

(a) Amendment.--Section 204 of the Investment Advisers Act of 1940
(15 U.S.C. 80b-4) is amended--
(1) by striking ``Every investment'' and inserting the
following:
``(a) In General.--Every investment''; and
(2) by adding at the end the following:
``(b) Filing Depositories.--The Commission may, by rule, require an
investment adviser--
``(1) to file with the Commission any fee, application,
report, or notice required to be filed by this title or the
rules issued under this title through any entity designated by
the Commission for that purpose; and
``(2) to pay the reasonable costs associated with such
filing and the establishment and maintenance of the systems
required by subsection (c).
``(c) Access to Disciplinary and Other Information.--
``(1) Maintenance of system to respond to inquiries.--The
Commission shall require the entity designated by the
Commission under subsection (b)(1) to establish and maintain a
toll-free telephone listing, or a readily accessible electronic
or other process, to receive and promptly respond to inquiries
regarding information (including disciplinary actions,
regulatory, judicial, and arbitration proceedings, and other
information required by law or rule to be reported) involving
investment advisers and persons associated with investment
advisers. Such information shall include information on an
investment adviser (and the persons associated with that
adviser) whether the investment adviser is registered with the
Commission under section 203 or regulated solely by a State as
described in section 203A.
``(2) Recovery of costs.--An entity designated by the
Commission under subsection (b)(1) may charge persons making
inquiries, other than individual investors, reasonable fees for
responses to inquiries made under paragraph (1).
``(3) Limitation on liability.--An entity designated by the
Commission under subsection (b)(1) shall not have any liability
to any person for any actions taken or omitted in good faith
under this subsection.''.
(b) Conforming Amendments.--
(1) Section 203A of the Investment Advisers Act of 1940 (15
U.S.C. 80b-3a) is amended--
(A) by striking subsection (d); and
(B) by redesignating subsection (e) as subsection
(d).
(2) Section 306 of the National Securities Markets
Improvement Act of 1996 (15 U.S.C. 80b-10, note; Public Law
104-290; 110 Stat. 3439) is repealed.

SEC. 105. STATE INSURANCE AND SECURITIES JURISDICTION ON MILITARY
INSTALLATIONS.

(a) Clarification of Jurisdiction.--Any law, regulation, or order
of a State with respect to regulating the business of insurance or the
offer or sale (or both) of securities shall apply to such activities
conducted on Federal land or facilities in the United States and
abroad, including military installations, except to the extent that
such law, regulation, or order--
(1) directly conflicts with any applicable Federal law,
regulation, or authorized directive; or
(2) would not apply if such activity were conducted on
State land.
(b) Primary State Jurisdiction.--To the extent that multiple State
laws would otherwise apply pursuant to subsection (a) to an insurance
or securities activity of an individual or entity on Federal land or
facilities, the State having the primary duty to regulate such activity
and whose laws shall apply to such activity in the case of a conflict
shall be--
(1) the State within which the Federal land or facility is
located; or
(2) if the Federal land or facility is located outside of
the United States, the State in which--
(A) in the case of an individual engaged in the
business of insurance, such individual has been issued
a resident license;
(B) in the case of an individual engaged in the
offer or sale (or both) of securities, such individual
is registered or required to be registered to do
business or the person solicited by such individual
resides;
(C) in the case of an entity engaged in the
business of insurance, such entity is domiciled; or
(D) in the case of an entity engaged in the offer
or sale (or both) of securities, such entity is
registered or is required to be registered to do
business or the person solicited by such entity
resides.

SEC. 106. REQUIRED DEVELOPMENT OF MILITARY PERSONNEL PROTECTION
STANDARDS REGARDING INSURANCE SALES.

(a) State Standards.--The Congress intends that--
(1) the States collectively work with the Secretary of
Defense to ensure implementation of appropriate standards to
protect members of the Armed Forces from dishonest and
predatory insurance sales practices while on a military
installation of the United States (including installations
located outside of the United States); and
(2) each State identify its role in promoting the standards
described in paragraph (1) in a uniform manner within 12 months
after the date of the enactment of this Act.
(b) State Report.--It is the sense of the Congress that the NAIC
should, after consultation with the Secretary of Defense and within 12
months after the date of the enactment of this Act, conduct a study to
determine the extent to which the States have met the requirement of
subsection (a) and report such study to the Committee on Financial
Services of the House of Representatives and the Committee on Banking,
Housing, and Urban Affairs of the Senate.

SEC. 107. REQUIRED DISCLOSURES REGARDING LIFE INSURANCE.

(a) Requirement.--Except as provided in subsection (d), no insurer
or producer may sell or solicit, in person, any life insurance product
to any member of the Armed Forces on a military installation of the
United States unless a disclosure in accordance with this section is
provided to such member before the sale of such insurance.
(b) Disclosure.--A disclosure in accordance with this section is a
written disclosure that--
(1) states that subsidized life insurance may be available
to the member of the Armed Forces from the Federal Government;
(2) states that the United States Government has in no way
sanctioned, recommended, or encouraged the sale of the product
being offered;
(3) is made in plain and readily understandable language
and in a type font at least as large as the font used for the
majority of the policy; and
(4) with respect to a sale or solicitation on Federal land
or facilities located outside of the United States by an
individual or entity engaged in the business of insurance,
except to the extent otherwise specifically provided by the
laws of such State in reference to this Act, lists the address
and phone number where consumer complaints are received by the
State insurance commissioner for the State in which the
individual has been issued a resident license or the entity is
domiciled, as applicable.
(c) Enforcement.--If it is determined by a State or Federal agency,
or in a final court proceeding, that any individual or entity has
intentionally failed to provide a disclosure required by this section,
such individual or entity shall be prohibited from further engaging in
the business of insurance with respect to employees of the Federal
Government on Federal land, except--
(1) with respect to existing policies; and
(2) to the extent required by the Federal Government
pursuant to previous commitments.
(d) Exceptions.--
(1) Federal and state insurance activity.--This section
shall not apply to insurance activities--
(A) specifically contracted by or through the
Federal Government or any State government; or
(B) specifically exempted from the applicability of
this Act by a Federal or State law, regulation, or
order that specifically refers to this paragraph.
(2) Uniform state standards.--If a majority of the States
have adopted, in materially identical form, a standard setting
forth the disclosures required under this section that apply to
insurance solicitations and sales to military personnel on
military installations of the United States, after the
expiration of the 2-year period beginning on such majority
adoption, such standard shall apply in lieu of the requirements
of this section to all insurance solicitations and sales to
military personnel on military installations, with respect to
such States, to the extent that such standards do not directly
conflict with any applicable authorized Federal regulation or
directive.
(3) Materially identical form.--For purposes of this
subsection, standards adopted by more than one State shall be
considered to have materially identical form to the extent that
such standards require or prohibit identical conduct with
respect to the same activity, notwithstanding that the
standards may differ with respect to conduct required or
prohibited with respect to other activities.

SEC. 108. IMPROVING LIFE INSURANCE PRODUCT STANDARDS.

(a) In General.--It is the sense of the Congress that the NAIC
should, after consultation with the Secretary of Defense and within 12
months after the date of the enactment of this Act, conduct a study and
submit a report to the Committee on Financial Services of the House of
Representatives and the Committee on Banking, Housing, and Urban
Affairs of the Senate on ways of improving the quality of and sale of
life insurance products sold by insurers and producers on military
installations of the United States, which may include limiting sales
authority to companies and producers that are certified as meeting
appropriate best practices procedures or creating standards for
products specifically designed for members of the Armed Forces
regardless of the sales location.
(b) Conditional GAO Report.--If the NAIC does not submit the report
to the committees as described in subsection (a), the Comptroller
General of the United States shall study any proposals that have been
made to improve the quality and sale of life insurance products sold by
insurers and producers on military installations of the United States
and report to the Committee on Financial Services of the House of
Representatives and the Committee on Banking, Housing, and Urban
Affairs of the Senate on such proposals within 6 months after the
expiration of the period referred to in subsection (a).

SEC. 109. REQUIRED REPORTING OF DISCIPLINED INSURANCE PRODUCERS.

(a) Reporting by Insurers.--After the expiration of the 2-year
period beginning on the date of the enactment of this Act, no insurer
may enter into or renew a contractual relationship with a producer that
solicits or sells life insurance on military installations of the
United States unless the insurer has implemented a system to report, to
the State insurance commissioner of the State of the domicile of the
insurer and the State of residence of the insurance producer,
disciplinary actions taken against the producer with respect to the
producer's sales or solicitation of insurance on a military
installation of the United States, as follows:
(1) Any disciplinary action taken by any government entity
that the insurer knows has been taken.
(2) Any significant disciplinary action taken by the
insurer.
(b) Reporting by States.--It is the sense of the Congress that
within 2 years after the date of the enactment of this Act, the States
should collectively implement a system to--
(1) receive reports of disciplinary actions taken against
insurance producers by insurers or government entities with
respect to the producers' sale or solicitation of insurance on
a military installation; and
(2) disseminate such information to all other States and to
the Secretary of Defense.

SEC. 110. REPORTING BARRED PERSONS ENGAGING IN FINANCIAL SERVICES
ACTIVITIES.

(a) Establishment.--The Secretary of Defense shall maintain a list
of the name, address, and other appropriate information of persons
engaged in financial services activities that have been barred, banned,
or otherwise limited in any manner that is not generally applicable to
all such type of persons, from any or all military installations of the
United States or from patronage by military members.
(b) Notice and Access.--The Secretary shall ensure that--
(1) the appropriate Federal and State agencies responsible
for any financial services regulation are promptly notified
upon the inclusion or removal of a person under such agencies'
jurisdiction; and
(2) the list is kept current and easily accessible--
(A) for use by such agencies; and
(B) for purposes of enforcing or considering any
such bar, ban, or limitation by the appropriate Federal
personnel, including commanders of military
installations.
(c) Regulations.--
(1) In general.--The Secretary shall issue regulations in
accordance with this subsection to provide for the
establishment and maintenance of the list under this section,
including appropriate due process considerations.
(2) Timing.--
(A) Proposed regulations.--Not later than the
expiration of the 60-day period beginning on the date
of the enactment of this Act, the Secretary shall
prepare and submit to the appropriate Committees a copy
of the regulations under this subsection that are
proposed to be published for comment. The Secretary may
not publish such regulations for comment in the Federal
Register until the expiration of the 15-day period
beginning upon such submission to the appropriate
Committees.
(B) Final regulations.--Not later than 90 days
after the date of the enactment of this Act, the
Secretary shall submit to the appropriate Committees a
copy of the regulations under this section to be
published as final.
(C) Effective date.--Such regulations shall become
effective upon the expiration of the 30-day period
beginning upon such submission to the appropriate
Committees.
(3) Definition.--For the purposes of this section, the term
``appropriate Committees'' means--
(A) the Committee on Financial Services and the
Committee on Armed Services of the House of
Representatives; and
(B) the Committee on Banking, Housing, and Urban
Affairs and the Committee on Armed Services of the
Senate.

SEC. 111. SENSE OF CONGRESS.

It is the sense of the Congress that the Federal and State agencies
responsible for insurance and securities regulation should provide
advice to the appropriate Federal entities to consider--
(1) significantly increasing the life insurance coverage
made available through the Federal Government to members of the
Armed Forces;
(2) implementing appropriate procedures to encourage
members of the Armed Forces to improve their financial literacy
and obtain objective financial counseling before purchasing
additional life insurance coverage or investments beyond those
provided by the Federal Government; and
(3) improving the benefits and matching contributions
provided under the Thrift Savings Plan to members of the Armed
Forces.

SEC. 112. DEFINITIONS.

For purposes of this Act, the following definitions shall apply:
(1) Entity.--The term ``entity'' includes insurers.
(2) Individual.--The term ``individual'' includes insurance
agents and producers.
(3) NAIC.--The term ``NAIC'' means the National Association
of Insurance Commissioners.
(4) State insurance commissioner.--The term ``State
insurance commissioner'' means, with respect to a State, the
officer, agency, or other entity of the State that has primary
regulatory authority over the business of insurance and over
any person engaged in the business of insurance, to the extent
of such business activities, in such State.

TITLE II--LENDING TO ARMED FORCES PERSONNEL

SEC. 201. REQUIREMENTS APPLICABLE TO CERTAIN LOANS TO MILITARY
SERVICEMEMBERS.

(a) Definitions.--For purposes of this section, the following
definitions shall apply:
(1) Military lender.--
(A) In general.--The term ``military lender''
means--
(i) a person engaged in the business of
extending consumer credit that--
(I) targets customers who are
active duty members of the Armed
Forces; or
(II) knows or has reason to know
that more than 10 percent of the
person's customers for consumer credit
products are active duty members of the
Armed Forces; and
(ii) any assignee of such person with
respect to any credit extended to any such
customer.
(B) Exception.--The term ``military lender'' does
not include any insured depository institution, except
as provided in paragraph (3)(B).
(C) Treatment of each office as lender.--In the
case of any person engaged in the business of extending
consumer credit from more than 1 office or at more than
1 location, each office or location at which credit is
offered or extended or a credit transaction is
consummated shall be treated as a separate person for
purposes of this section.
(2) Covered loan.--The term ``covered loan''--
(A) means any extension of credit to an active duty
member of the Armed Forces by a military lender that
has an annual percentage rate that exceeds by more than
5 percentage points the average annual percentage rate
for 24-month personal loans, as published by the Board
of Governors of the Federal Reserve System for the most
recent calendar quarter preceding the quarter in which
such extension of credit is made; and
(B) does not include any extension of credit on
margin on securities by a broker or dealer registered
with the Securities and Exchange Commission under the
Securities Exchange Act of 1934 to the extent such
extension of credit complies with the rules and
regulations of the Board of Governors of the Federal
Reserve System, the Securities and Exchange Commission,
and any applicable self-regulatory organization
relating to credit on margin on securities.
(3) Insured depository institution.--
(A) In general.--The term ``insured depository
institution''--
(i) has the meaning given such term in
section 3 of the Federal Deposit Insurance Act;
and
(ii) includes any insured credit union (as
defined in section 101(7) of the Federal Credit
Union Act).
(B) Exclusion.--For purposes of this section, the
term ``insured depository institution'' does not
include an insured depository institution in any
circumstance in which--
(i) such depository institution is
extending credit pursuant to a contractual
relationship with a third-party agent; and
(ii) such agent would be a military lender,
under this section, if the agent made the same
loan as a principal.
(4) Active duty member of the armed forces.--The term
``active duty member of the Armed Forces'' means any member of
the Armed Forces who is on active duty (as defined in section
101(d)(1) of title 10, United States Code) under a call or
order that does not specify a period of 30 days or less.
(5) Targets customers.--For purposes of paragraph
(1)(A)(i)(I), the term ``targets customers'' means to, directly
or indirectly, solicit, or engage in other promotional
activities explicitly directed at, members of the Armed Forces
for the purpose of securing business from the recipients of
such solicitations or promotions.
(6) Annual percentage rate.--The term ``annual percentage
rate'' has the same meaning as in section 107 of the Truth in
Lending Act, as implemented by regulations of the Board of
Governors of the Federal Reserve System.
(b) Protection of Military Servicemembers.--Any military lender who
makes a loan to an active duty member of the Armed Forces (other than a
loan described in paragraph (2)(B)) may not, with respect to such
loan--
(1) garnish any military salary or wages, or accept any
assignment of or institute any allotment of any military salary
or wages, to secure payment of the loan, unless any such
allotment or assignment is voluntary and may be cancelled at
any time by the borrower;
(2) contact, or threaten to contact, the borrower's
commanding officer or any other person in the borrower's
military chain of command in an effort to collect on such loan;
(3) include any provision in the loan agreement, or in any
other instrument or agreement made in connection with such
loan, that purports to--
(A) waive any rights of the borrower under any
Federal or State law, including this section and the
Servicemembers Civil Relief Act (50 U.S.C. App. 501 et
seq.); or
(B) provide the consent of the borrower for any
action prohibited under paragraph (1);
(4) at any time, use oral or written representations, or
use any symbols, that suggest, give the appearance, or provide
reasonable cause to believe that any component of the Armed
Forces, the Department of Defense, or any federal entity
sponsors or endorses the military lender, any agent of the
lender, or any good, service, commodity, or credit that is
sold, provided, or extended by the military lender (unless
expressly authorized in writing by such entity); or
(5) if such loan is a covered loan, enter into the loan
without disclosing, prior to consummation of the transaction
and in conspicuous form, the following notice:
``Notice to military servicemembers:
``You are not required to complete this agreement
merely because you have received these disclosures or
even if you have signed an application for an extension
of credit. If you obtain this credit to repay other
loans, you may get into serious financial difficulties
if you use this credit to pay off old debts and then
replace them with other new debts. Before you complete
this agreement, you should consider applying for credit
through other organizations or entities. Interest-free
loans or grants may be available from the Army, Air
Force, or Navy-Marine Corps Relief Society, the United
Service Organizations, or another base or military
service organization for military personnel seeking
short-term credit in response to a family or other
emergency.
``This extension of credit is not sponsored or
endorsed by any component of the Armed Forces, the
Department of Defense, or any Federal entity.
``Your lender may not garnish your salary or wages,
or accept any assignment of or institute an allotment
of your salary or wages, to secure repayment of the
debt, unless any such allotment or assignment is
voluntary and may be cancelled by you at any time. Your
lender may not contact your commanding officer or
anyone in your chain of command in an effort to collect
on the loan.
``You and your dependents may have additional
rights and protections under Federal and State law with
respect to this loan, including the Servicemembers
Civil Relief Act, which you cannot waive and which the
lender may not ask or require you to waive.''.
(c) Rule of Construction.--No provision of this section shall be
construed as--
(1) authorizing any person that is not a military lender to
engage in any activity that is prohibited for military lenders
under this section;
(2) creating any inference that any activity described in
subsection (b) is a lawful activity for any person or would be
a lawful activity for a military lender but for this section;
or
(3) creating any inference that any right or protection
provided for consumers under any Federal or State law can be
waived by any consumer.
(d) Enforcement.--The provisions of this section shall be enforced
under section 917 of the Consumer Credit Protection Act, in the manner
provided in such section. For the purposes of any enforcement under
such section 917, any violation of a provision or requirement of this
section shall be treated as a violation of a provision or requirement
of title IX of such Act.
(e) Circumvention Prohibited.--The Federal Trade Commission shall,
with respect to entities and activities under its jurisdiction,
prescribe regulations to become effective not later than 90 days after
the date of the enactment of this Act to prevent a military lender from
taking any action in connection with any loan made to an active duty
member of the Armed Forces to structure a loan transaction, by
structuring any loan as an open-end credit plan (as defined in section
103 of the Truth in Lending Act), dividing any loan into separate
transactions, using a lower temporary or introductory rate of interest
to lower the overall annual percentage rate applicable for any loan, or
any similar action, for the purpose of avoiding designation as a
covered loan for purposes of
this section or otherwise circumventing or evading any requirement of
this title.

Passed the House of Representatives June 28, 2005.

Attest:

JEFF TRANDAHL,

Clerk.