H.R. 976House109th Congress (2005-2007)In Committee
Long-Term Care Act of 2005
Sponsored by 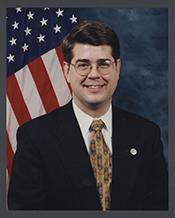 Rep. Lee Terry (R-NE)
Introduced February 17, 2005
Legislative Activity
Stay on top of the latest movement without scrolling through every action
HouseCommittee
Latest Action
Referred to the Subcommittee on Health.
March 3, 2005
View full timeline
HouseIntro Referral
Introduced in House
February 17, 2005
HouseIntro Referral
Referred to the House Committee on Ways and Means.
February 17, 2005
Bill Text
Latest available legislative text
Introduced in HouseIssued February 17, 2005
        [Congressional Bills 109th Congress]
[From the U.S. Government Publishing Office]
[H.R. 976 Introduced in House (IH)]

109th CONGRESS
1st Session
H. R. 976

To amend the Internal Revenue Code of 1986 to provide that
distributions from an individual retirement plan, a section 401(k)
plan, or a section 403(b) contract shall not be includible in gross
income to the extent used to pay long-term care insurance premiums.

_______________________________________________________________________

IN THE HOUSE OF REPRESENTATIVES

February 17, 2005

Mr. Terry (for himself, Mr. Jones of North Carolina, Mr. Sessions, Mr.
Boucher, Mr. Saxton, Mr. Kennedy of Minnesota, Mr. Paul, Ms. Ginny
Brown-Waite of Florida, Mr. Simpson, Mr. McCotter, Mrs. Musgrave, Mr.
Souder, Mr. Gordon, Mr. Hyde, and Mr. Peterson of Minnesota) introduced
the following bill; which was referred to the Committee on Ways and
Means

_______________________________________________________________________

A BILL

To amend the Internal Revenue Code of 1986 to provide that
distributions from an individual retirement plan, a section 401(k)
plan, or a section 403(b) contract shall not be includible in gross
income to the extent used to pay long-term care insurance premiums.

Be it enacted by the Senate and House of Representatives of the
United States of America in Congress assembled,

SECTION 1. SHORT TITLE.

This Act may be cited as the ``Long-Term Care Act of 2005''.

SEC. 2. EXCLUSION FROM GROSS INCOME FOR DISTRIBUTIONS FROM INDIVIDUAL
RETIREMENT PLANS, SECTION 401(K) PLANS, AND SECTION
403(B) CONTRACTS WHICH ARE USED TO PAY LONG-TERM CARE
INSURANCE PREMIUMS.

(a) In General.--Part III of subchapter B of chapter 1 of the
Internal Revenue Code of 1986 (relating to items specifically excluded
from gross income) is amended by inserting after section 139A the
following new item:

``SEC. 139B. DISTRIBUTIONS FROM INDIVIDUAL RETIREMENT PLANS, SECTION
401(K) PLANS, AND SECTION 403(B) CONTRACTS WHICH ARE USED
TO PAY LONG-TERM CARE INSURANCE PREMIUMS.

``(a) In General.--Gross income shall not include any distribution
to an individual from--
``(1) an individual retirement plan, or
``(2) from amounts attributable to employer contributions
made pursuant to elective deferrals described in subparagraph
(A) or (C) of section 402(g)(3),
to the extent that such distributions do not exceed the long-term care
insurance premiums paid during the taxable year for insurance covering
the individual or the individual's spouse.
``(b) Denial of Double Benefit.--The limitation in section
213(d)(10) shall be reduced by the amount which would (but for
subsection (a)) be includible in the taxpayer's gross income for the
taxable year.
``(c) No Effect on Qualification.--An arrangement shall not fail to
be treated as a qualified cash or deferred arrangement (as defined in
section 401(k)) or a contract described in section 403(b) by reason of
permitting distributions for the payment of long-term care insurance
premiums.''
(b) Clerical Amendment.--The table of sections for such part III is
amended by inserting after the item relating to section 139A the
following new item:

``Sec. 139B. Distributions from individual retirement plans, section
401(k) plans, and section 403(b) contracts
which are used to pay long-term care
insurance premiums.''
(c) Effective Date.--The amendments made by this section shall
apply to distributions after the date of the enactment of this Act.
<all>