Providing for the concurrence by the House with amendments in the amendments of the Senate to H.R. 1499.
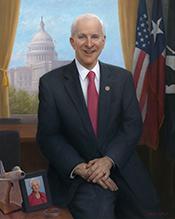
 Rep. Virginia Foxx (R-NC)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Motion to reconsider laid on the table Agreed to without objection.
May 9, 2006 • 7:01 PM
View full timeline
Introduced in House
May 9, 2006
Mr. Johnson, Sam moved to suspend the rules and agree to the resolution.
May 9, 2006 • 2:44 PM
Considered under suspension of the rules. (consideration: CR H2193-2194)
May 9, 2006 • 2:45 PM
DEBATE - The House proceeded with forty minutes of debate on H. Res. 803.
May 9, 2006 • 2:45 PM
At the conclusion of debate, the Yeas and Nays were demanded and ordered. Pursuant to the provisions of clause 8, rule XX, the Chair announced that further proceedings on the motion would be postponed.
May 9, 2006 • 2:57 PM
Considered as unfinished business. (consideration: CR H2299)
May 9, 2006 • 6:33 PM
Passed/agreed to in House: On motion to suspend the rules and agree to the resolution Agreed to by the Yeas and Nays: (2/3 required): 412 - 0 (Roll no. 128).(text: CR H2193)
May 9, 2006 • 7:01 PM
On motion to suspend the rules and agree to the resolution Agreed to by the Yeas and Nays: (2/3 required): 412 - 0 (Roll no. 128). (text: CR H2193)
May 9, 2006 • 7:01 PM
Motion to reconsider laid on the table Agreed to without objection.
May 9, 2006 • 7:01 PM
Voting History
1 vote recorded • Roll call available
Floor Debate
3 membersWhat members said about H.Res. 803 on the floor

Floor Debate
3 membersWhat members said about H.Res. 803 on the floor
Mr. Speaker, I am truly honored to be here today. I am honored because the mere consideration of this bill represents the greatness of our Republican democracy. At this time 2 years ago, I dreamed of…
Mr. Speaker, I yield myself such time as I may consume. Mr. Speaker, I stand today in support of H.R. 1499. This bill is actively supported by my Democratic colleagues. On May 23, 2005, this bill…
Mr. Speaker, I move to suspend the rules and agree to the resolution (H. Res. 803) providing for the concurrence by the House with amendment in the amendment of the Senate to H.R. 1499. Mr. Speaker,…
Bill Text
Latest available legislative text
        [Congressional Bills 109th Congress]
[From the U.S. Government Publishing Office]
[H. Res. 803 Engrossed in House (EH)]

H. Res. 803

In the House of Representatives, U.S.,

May 9, 2006.
Resolved, That upon the adoption of this resolution the bill (H.R. 1499)
entitled ``An Act to amend the Internal Revenue Code of 1986 to allow members of
the Armed Forces serving in a combat zone to make contributions to their
individual retirement plans even if the compensation on which such contribution
is based is excluded from gross income, and for other purposes'', with the
Senate amendment thereto, shall be considered to have been taken from the
Speaker's table to the end that the Senate amendment thereto be, and the same is
hereby, agreed to with an amendment as follows:

At the end of the Senate amendment add the following:

On page 3, after line 3 of the House engrossed bill, insert
the following:

(c) Contributions for Taxable Years Ending Before Enactment.--
(1) In general.--In the case of any taxpayer with respect
to whom compensation was excluded from gross income under
section 112 of the Internal Revenue Code of 1986 for any
taxable year beginning after December 31, 2003, and ending
before the date of the enactment of this Act, any contribution
to an individual retirement plan made on account of such
taxable year and not later than the last day of the 3-year
period beginning on the date of the enactment of this Act shall
be treated, for purposes of such Code, as having been made on
the last day of such taxable year.
(2) Waiver of limitations.--
(A) Credit or refund.--If the credit or refund of
any overpayment of tax resulting from a contribution to
which paragraph (1) applies is prevented at any time by
the operation of any law or rule of law (including res
judicata), such credit or refund may nevertheless be
allowed or made if the claim therefor is filed before
the close of the 1-year period beginning on the date
that such contribution is made (determined without
regard to paragraph (1)).
(B) Assessment of deficiency.--The period for
assessing a deficiency attributable to a contribution
to which paragraph (1) applies shall not expire before
the close of the 3-year period beginning on the date
that such contribution is made. Such deficiency may be
assessed before the expiration of such 3-year period
notwithstanding the provisions of any other law or rule
of law which would otherwise prevent such assessment.
(3) Individual retirement plan defined.--For purposes of
this subsection, the term ``individual retirement plan'' has
the meaning given such term by section 7701(a)(37) of such
Code.

Attest:

Clerk.