S.Amdt. 2667
What it does: Inserts new text wherever appropriate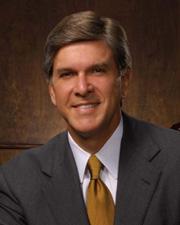 Sen. Gordon H. Smith (R-OR)
What it changes
1 change to S. 1637
Inserts new text wherever appropriate
InsertsInserted: SEC.__. INCOME AVERAGING FOR FARMERS AND FISHERMEN NOT TO INCREASE ALTERNATIVE MINIMUM TAX LIABILITY.
Inserted: (a) In General.--Section 55(c) (defining regular tax) is amended by redesignating paragraph (2) as paragraph (3) and by inserting after paragraph (1) the following new paragraph:
Inserted: "(2) Coordination with income averaging for farmers and fishermen.--Solely for purposes of this section, section 1301 (relating to averaging of farm and fishing income) shall not apply in computing the regular tax.".
Inserted: (b) Allowing Income Averaging for Fishermen.--
Inserted: (1) In general.--Section 1301(a) is amended by striking "farming business" and inserting "farming business or fishing business".
Inserted: (2) Definition of elected farm income.--
Inserted: (A) In general.--Clause (i) of section 1301(b)(1)(A) is amended by inserting "or fishing business" before the semicolon.
Inserted: (B) Conforming amendment.--Subparagraph (B) of section 1301(b)(1) is amended by inserting "or fishing business" after "farming business" both places it occurs.
Inserted: (3) Definition of fishing business.--Section 1301(b) is amended by adding at the end the following new paragraph:
Inserted: "(4) Fishing business.--The term 'fishing business' means the conduct of commercial fishing as defined in section 3 of the Magnuson-Stevens Fishery Conservation and Management Act (16 U.S.C. 1802).".
Inserted: (c) Effective Date.--The amendments made by this section shall apply to taxable years beginning after December 31, 2003.
The amendment doesn't say where this goes; the clerk decides.
Original wording
At the appropriate place, insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 2667. Mr. SMITH (for himself, Mr. Lautenberg, and Ms. Murkowski) submitted an amendment intended to be proposed by him to the bill S. 1637, to amend the Internal Revenue Code of 1986 to comply with the World Trade Organization rulings on the FSC/ETI benefit in a manner that preserves jobs and production activities in the United States, to reform and simplify the international taxation rules of the United States, and for other purposes; which was ordered to lie on the table; as follows:
At the appropriate place, insert the following:
SEC.__. INCOME AVERAGING FOR FARMERS AND FISHERMEN NOT TO INCREASE ALTERNATIVE MINIMUM TAX LIABILITY.
(a) In General.--Section 55(c) (defining regular tax) is amended by redesignating paragraph (2) as paragraph (3) and by inserting after paragraph (1) the following new paragraph:
“(2) Coordination with income averaging for farmers and fishermen.--Solely for purposes of this section, section 1301 (relating to averaging of farm and fishing income) shall not apply in computing the regular tax.”.
(b) Allowing Income Averaging for Fishermen.--
(1) In general.--Section 1301(a) is amended by striking “farming business” and inserting “farming business or fishing business”.
(2) Definition of elected farm income.--
(A) In general.--Clause (i) of section 1301(b)(1)(A) is amended by inserting “or fishing business” before the semicolon.
(B) Conforming amendment.--Subparagraph (B) of section 1301(b)(1) is amended by inserting “or fishing business” after “farming business” both places it occurs.
(3) Definition of fishing business.--Section 1301(b) is amended by adding at the end the following new paragraph:
“(4) Fishing business.--The term ‘fishing business' means the conduct of commercial fishing as defined in section 3 of the Magnuson-Stevens Fishery Conservation and Management Act (16 U.S.C. 1802).”.
(c) Effective Date.--The amendments made by this section shall apply to taxable years beginning after December 31, 2003.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
March 3, 2004