S.Amdt. 2690
What it does: Inserts new text on page 71, between lines 2 and 3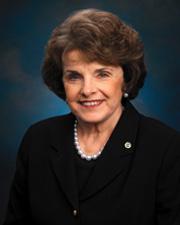 Sen. Dianne Feinstein (D-CA)
What it changes
1 change to S. 1637
Inserts new text on page 71, between lines 2 and 3
InsertsPrinted pageInserted: (f) Exception for Audiovisual Services.--
Inserted: (1) In general.--The amendments made by subsections (a) and (b) shall not apply to extraterritorial income derived from audiovisual services.
Inserted: (2) Coordination with deduction for income attributable to united states production activities.--The deduction under section 199 of the Internal Revenue Code of 1986, as added by section 102 of this Act, shall not apply to any income described in paragraph (1).
Inserted: (3) Coordination with transition rules.--The base period amount under subsection (e)(4) shall not take into account extraterritorial income derived from audiovisual services.
Inserted: (4) Audiovisual services.--For purposes of this subsection, the term "audiovisual services" means such activities as are treated as audiovisual services for purposes of the General Agreement on Trade in Services referred to in section 101(d)(14) of the Uruguay Round Agreements Act (19 U.S.C. 3511(d)(14)).
Original wording
On page 71, between lines 2 and 3, insert the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 2690. Mrs. FEINSTEIN (for herself, Mr. Conrad, and Mrs. Boxer) submitted an amendment intended to be proposed by her to the bill S. 1637, to amend the Internal Revenue Code of 1986 to comply with the World Trade Organization rulings on the FSC/ETI benefit in a manner that preserves jobs and production activities in the United States, to reform and simplify the international taxation rules of the United States, and for other purposes; which was ordered to lie on the table; as follows:
On page 71, between lines 2 and 3, insert the following:
(f) Exception for Audiovisual Services.--
(1) In general.--The amendments made by subsections (a) and (b) shall not apply to extraterritorial income derived from audiovisual services.
(2) Coordination with deduction for income attributable to united states production activities.--The deduction under section 199 of the Internal Revenue Code of 1986, as added by section 102 of this Act, shall not apply to any income described in paragraph (1).
(3) Coordination with transition rules.--The base period amount under subsection (e)(4) shall not take into account extraterritorial income derived from audiovisual services.
(4) Audiovisual services.--For purposes of this subsection, the term “audiovisual services” means such activities as are treated as audiovisual services for purposes of the General Agreement on Trade in Services referred to in section 101(d)(14) of the Uruguay Round Agreements Act (19 U.S.C. 3511(d)(14)).
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
March 4, 2004