S.Amdt. 2763
What it does: Adds SEC. __. REPEAL OF FOREIGN BASE COMPANY SHIPPING INCOME FOR QUALIFIED U.S. FLAG FLEETS AND CARIBBEAN BASIN SHIPPING CORPORATIONS on page 146, line 23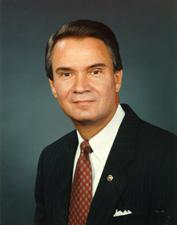 Sen. John B. Breaux (D-LA)
What it changes
1 change to S. 1637
Adds SEC. __. REPEAL OF FOREIGN BASE COMPANY SHIPPING INCOME FOR QUALIFIED U.S. FLAG FLEETS AND CARIBBEAN BASIN SHIPPING CORPORATIONS on page 146, line 23
Adds a sectionPrinted pageInserted: SEC. __. REPEAL OF FOREIGN BASE COMPANY SHIPPING INCOME FOR QUALIFIED U.S. FLAG FLEETS AND CARIBBEAN BASIN SHIPPING CORPORATIONS.
Inserted: (a) In General.--Subsection (f) of section 954 is amended to read as follows:
Inserted: "(f) Foreign Base Company Shipping Income.--For purposes of subsection (a)(4)--
Inserted: "(1) In General.--The term 'foreign base company shipping income' means income derived from, or in connection with, the use (or hiring or leasing for use) of any aircraft or vessel in foreign commerce, or from, or in connection with, the performance of services directly related to the use of any such aircraft, or vessel, or from the sale, exchange, or other disposition of any such aircraft or vessel. Such term includes, but is not limited to--
Inserted: "(A) dividends and interest received from a foreign corporation in respect of which taxes are deemed paid under section 902, and gain from the sale, exchange, or other disposition of stock or obligations of such a foreign corporation to the extent that such dividends, interest, and gains are attributable to foreign base company shipping income, and
Inserted: "(B) that portion of the distributive share of the income of a partnership attributable to foreign base company shipping income.
Inserted: Such term includes any income derived from a space or ocean activity (as defined in section 863(d)(2)). Except as provided in subparagraph (A), such term shall not include any dividend or interest income which is foreign personal holding company income (as defined in subsection (c)).
Inserted: "(2) Exceptions.--
Inserted: "(A) In general.--Such term shall not include income attributable to a qualified U.S.-flag fleet or a Caribbean Basin shipping corporation.
Inserted: "(B) Qualified u.s.-flag fleet.--For purposes of this subsection, the term 'qualified U.S.-flag fleet' means a fleet or 2 or vessels each of which--
Inserted: "(i) is documented under the laws of the United States,
Inserted: "(ii) has a deadweight tonnage of not less than 10,000 deadweight tons,
Show 168 more inserted paragraphsShow less
Inserted: "(iii) are owned by a member of the controlled group (within the meaning of section 1563) of the controlled foreign corporation, and
Inserted: "(iv) has been in operation for not less than 320 days during the preceding taxable year.
Inserted: For purposes of clause (iv), days during which a vessel is dry docked or undergoing survey, inspection, or repair shall be considered to be days during which the vessel is operated.
Inserted: "(C) Caribbean basin shipping corporation.--For purposes of this subsection--
Inserted: "(i) In general.--The term 'Caribbean Basin shipping corporation' means a corporation of which 75 percent of the foreign base company shipping income (as defined in paragraph (1)) for the taxable year is Caribbean Basin shipping income.
Inserted: "(ii) Caribbean basin shipping income.--The term 'Caribbean Basin shipping income' means foreign base company shipping income (as defined in paragraph (1)) derived from or in connection with the operation of any nonpassenger vessel in foreign commerce--
Inserted: "(I) within any Caribbean Basin country,
Inserted: "(II) among Caribbean Basin countries, or
Inserted: "(III) between any Caribbean Basin country and the United States.
Inserted: Such term includes any such foreign base company shipping income derived from that portion of any transshipping originating or terminating in any country which is not a Carribean Basin country if such transshipping otherwise satisfies the requirements of this clause.
Inserted: "(iii) Caribbean basin country.--The term 'Caribbean Basin country' means any beneficiary country (within the meaning of section 212(a)(1)(A) of the Caribbean Basin Economic Recovery Act), except that such term shall also include Anguilla, Colombia, Mexico, the United States Virgin Islands, and Venezuela.".
Inserted: SEC. __. INCOME OF MERCHANT SEAMAN EXCLUDABLE FROM GROSS INCOME AS FOREIGN EARNED INCOME.
Inserted: (a) In General.--Chapter 1 is amended by inserting after subchapter Q the following new subchapter:
Inserted: "Subchapter R--Election to Determine Taxable Income From Certain International Shipping Activities Using per Ton Rate
Inserted: "Sec. 1352. Alternative tax on qualifying shipping activities.
Inserted: "Sec. 1353. Taxable income from qualifying shipping activities.
Inserted: "Sec. 1354. Qualifying shipping tax election; revocation; termination.
Inserted: "Sec. 1355. Definitions and special rules.
Inserted: "Sec. 1356. Qualifying shipping activities.
Inserted: "Sec. 1357. Items not subject to regular tax; depreciation; interest.
Inserted: "Sec. 1358. Allocation of credits, income, and deductions.
Inserted: "Sec. 1359. Disposition of qualifying shipping assets.
Inserted: "SEC. 1352. ALTERNATIVE TAX ON QUALIFYING SHIPPING ACTIVITIES.
Inserted: "(a) In General.--In the case of an electing corporation--
Inserted: "(1) the taxable income of such corporation from qualifying shipping activities shall be the amount determined under this subchapter, and
Inserted: "(2) the corporate percentages of the items of income, gain, loss, deduction, or credit of such corporation and of other members of the electing group of such corporation which would otherwise be taken into account by reason of its qualifying shipping activities shall be taken into account to the extent provided in section 1357.
Inserted: "(b) Alternative Tax.--The taxable income of an electing corporation from qualifying shipping activities, if otherwise taxable under section 11, 882, or 887, shall be subject to tax only under this section at the maximum rate specified in section 11(b).
Inserted: "(c) Transfers to Federal Vessel Financing Fund.--The Secretary of the Treasury shall transfer to the Federal Vessel Financing Fund created under title XI of the Merchant Marine Act, 1936, the taxes collected under subsection (b). Notwithstanding the preceding sentence, the income of a foreign corporation shall not be subject to tax under this subchapter to the extent its income is excludable from gross income under section 883(a)(1) or section 894(a).
Inserted: "SEC. 1353. TAXABLE INCOME FROM QUALIFYING SHIPPING ACTIVITIES.
Inserted: "(a) In General.--For purposes of this subchapter, the taxable income of an electing corporation from qualifying shipping activities shall be its corporate income percentage of the sum of the amounts determined under subsection (b) for each qualifying vessel operated by such electing corporation or other electing entity.
Inserted: "(b) Amounts.--For purposes of subsection (a), the amount of taxable income of an electing entity for each qualifying vessel shall equal the product of--
Inserted: "(1) the daily notional taxable income from the operation of the qualifying vessel in United States foreign trade, and
Inserted: "(2) the number of days during the taxable year that the electing entity operated such vessel as a qualifying vessel in United States foreign trade.
Inserted: "(c) Daily Notional Taxable Income.--For purposes of subsection (b), the daily notional taxable income from the operation of a qualifying vessel is--
Inserted: "(1) 40 cents for each 100 tons of the net tonnage of the vessel below 25,001 net tons, and
Inserted: "(2) 20 cents for each 100 tons of the net tonnage of the vessel in excess of 25,000 net tons.
Inserted: "(d) Multiple Operators of Vessel.--If 2 or more persons have a joint interest in a qualifying vessel and are considered as operators of that vessel, the taxable income from the operation of such vessel for that time (as determined under this section) shall be allocated among such persons on the basis of their ownership and charter interests in such vessel or on such other basis as the Secretary may prescribe by regulations.
Inserted: "(e) Noncorporate Percentage.--Notwithstanding any contrary provision of this subchapter, the noncorporate percentage of any item of income, gain, loss, deduction, or credit of any member of an electing group shall be taken into account for all purposes of this subtitle as if this subchapter were not in effect.
Inserted: "SEC. 1354. QUALIFYING SHIPPING TAX ELECTION; REVOCATION; TERMINATION.
Inserted: "(a) In General.--Except as provided in subsections (b) and (f), a qualifying shipping tax election may be made in respect of any qualifying entity.
Inserted: "(b) Condition of Election.--An election may be made by a member of a controlled group under this subsection for any taxable year only if all qualifying entities that are members of the controlled group join in the election.
Inserted: "(c) When Made.--An election under subsection (a) may be made by a qualifying entity in such form as prescribed by the Secretary. Such election shall be filed with the qualifying entity's return for the first taxable year to which the election shall apply, by the due date for such return (including any applicable extensions).
Inserted: "(d) Years for Which Effective.--An election under subsection (a) shall be effective for the taxable year of the qualifying entity for which it is made and for all succeeding taxable years of the entity, until such election is terminated under subsection (e).
Inserted: "(e) Termination.--
Inserted: "(1) By revocation.--
Inserted: "(A) In general.--An election under subsection (a) may be terminated by revocation.
Inserted: "(B) When effective.--Except as provided in subparagraph (C)--
Inserted: "(i) a revocation made during the taxable year and on or before the fifteenth day of the third month thereof shall be effective on the 1st day of such taxable year, and
Inserted: "(ii) a revocation made during the taxable year but after such fifteenth day shall be effective on the first day of the following taxable year.
Inserted: "(C) Revocation may specify prospective date.--If the revocation specifies a date for revocation which is on or after the day on which the revocation is made, the revocation shall be effective on and after the date so specified.
Inserted: "(2) By entity ceasing to be qualifying entity.--
Inserted: "(A) In general.--An election under subsection (a) shall be terminated whenever (at any time on or after the first day of the first taxable year for which the entity is an electing entity) such entity ceases to be a qualifying entity.
Inserted: "(B) When effective.--Any termination under this paragraph shall be effective on and after the date of cessation.
Inserted: "(f) Election After Termination.--If a qualifying entity has made an election under subsection (a) and if such election has been terminated under subsection (e), such entity (and any successor entity) shall not be eligible to make an election under subsection (a) for any taxable year before its fifth taxable year which begins after the first taxable year for which such termination is effective, unless the Secretary consents to such election.
Inserted: "SEC. 1355. DEFINITIONS AND SPECIAL RULES.
Inserted: "(a) Definitions.--For purposes of this subchapter:
Inserted: "(1) Controlled group.--The term 'controlled group' means any group of trusts and business entities whose members would be treated as a single employer under the rules of section 52(a) (without regard to paragraphs (1) and (2) thereof) and section 52(b)(1).
Inserted: "(2) Corporate income percentage.--The term 'corporate income percentage' means the least aggregate share, expressed as a percentage, of any item of income or gain of an electing corporation or electing group of which such corporation is a member from qualifying shipping activities that would, but for an election in effect under this subchapter, be required to be reported on the Federal income tax return of an electing corporation during any taxable period. In the case of an electing group which includes 2 or more electing corporations, the corporate income percentage of each such corporation shall be determined on the basis of such corporation's direct and indirect ownership and charter interests in qualifying vessels of the electing group or on such other basis as the Secretary may prescribe by regulations.
Inserted: "(3) Corporate loss percentage.--The term 'corporate loss percentage' means the greatest aggregate share, expressed as a percentage, of any item of loss, deduction, or credit of an electing corporation or electing group of which such corporation is a member from qualifying shipping activities that would, but for an election in effect under this subchapter, be required to be reported on the Federal income tax return of an electing corporation during any taxable period.
Inserted: "(4) Corporate percentages.--The term 'corporate percentages' means the corporate income percentage and the corporate loss percentage.
Inserted: "(5) Electing corporation.--The term 'electing corporation' means any C corporation that is an electing entity or that would, but for an election in effect under this subchapter, be required to report any item of income, gain, loss, deduction, or credit of an electing entity on its Federal income tax return.
Inserted: "(6) Electing entity.--The term 'electing entity' means any qualifying entity for which an election is in effect under this subchapter.
Inserted: "(7) Electing group.--The term 'electing group' means a controlled group of which one or more members is an electing entity.
Inserted: "(8) Noncorporate percentage.--The term 'noncorporate percentage' means the difference between 100 percent and the corporate income percentage or corporate loss percentage, as applicable.
Inserted: "(9) Qualifying entity.--The term 'qualifying entity' means a trust or business entity that--
Inserted: "(A) operates 1 or more qualifying vessels, and
Inserted: "(B) meets the shipping activity requirement in subsection (c).
Inserted: "(10) Qualifying shipping assets.--The term 'qualifying shipping assets' means any qualifying vessel and other assets which are used in core qualifying activities as described in section 1356(b).
Inserted: "(11) Qualifying vessel.--The term 'qualifying vessel' means a self-propelled (or a combination self-propelled and non-self-propelled) United States flag vessel of not less than 10,000 deadweight tons used in the United States foreign trade.
Inserted: "(12) United states domestic trade.--The term 'United States domestic trade' means the transportation of goods or passengers between places in the United States.
Inserted: "(13) United states flag vessel.--The term 'United States flag vessel' means any vessel documented under the laws of the United States.
Inserted: "(14) United states foreign trade.--The term 'United States foreign trade' means the transportation of goods or passengers between a place in the United States and a foreign place or between foreign places.
Inserted: "(b) Operating a Vessel.--For purposes of this subchapter:
Inserted: "(1) Except as provided in paragraph (2), an entity is treated as operating any vessel owned by, or chartered (including a time charter) to, the entity.
Inserted: "(2) An entity is treated as operating a vessel that it has chartered out on bareboat charter terms only if--
Inserted: "(A) the vessel is temporarily surplus to the entity's requirements and the term of the charter does not exceed 3 years; or
Inserted: "(B) the vessel is bareboat chartered to a member of a controlled group which includes such entity or to an unrelated third party that sub-bareboats or time charters the vessel to a member of such controlled group (including the owner).
Inserted: "(c) Shipping Activity Requirement.--For purposes of this section, the shipping activity requirement is met for a taxable year only by an entity described in paragraph (1), (2), or (3).
Inserted: "(1) An entity in the first taxable year of its qualifying shipping tax election if, for the preceding taxable year, the test in paragraph (4) is met.
Inserted: "(2) An entity in the second or any subsequent taxable year of its qualifying shipping tax election if, for each of the 2 preceding taxable years, the test in paragraph (4) is met.
Inserted: "(3) An entity that would be described in paragraph (1) or (2) if the test in paragraph (4) were applied on an aggregate basis to the controlled group of which such entity is a member, and vessel charters between members of the controlled group were disregarded.
Inserted: "(4) The test in this paragraph is met if on average at least 25 percent of the aggregate tonnage of qualifying vessels operated by the entity were owned by the entity or chartered to the entity on bareboat charter terms. For purposes of the preceding sentence, vessels chartered (including time chartered) to an entity by a member of a controlled group which includes the entity, or by a third party that bareboat charters the vessels from the entity or a member of the entity's controlled group, shall be treated as chartered to the entity on bareboat charter terms.
Inserted: "(d) Effect of Temporarily Ceasing To Operate a Qualifying Vessel.--
Inserted: "(1) A temporary cessation by an electing entity, in operation of a qualifying vessel shall be disregarded for purposes of subsections (b) and (c) until an occurrence described in paragraph (3) if the electing entity gives timely notice to the Secretary stating--
Inserted: "(A) that it has temporarily ceased to operate the qualifying vessel, and
Inserted: "(B) its intention to resume operating the qualifying vessel.
Inserted: "(2) Notice shall be deemed timely if given not later than the due date (including extensions) for the electing entity's tax return (as set forth in section 6072(b)) for the taxable year in which the temporary cessation begins.
Inserted: "(3) The disregard provided by paragraph (1) continues until the earlier to occur of--
Inserted: "(A) the electing entity abandoning its intention to resume operation of the qualifying vessel, or
Inserted: "(B) the electing entity resuming operation of the qualifying vessel.
Inserted: "(e) Effect of Temporarily Operating a Qualifying Vessel in the United States Domestic Trade.--
Inserted: "(1) The temporary operation in the United States domestic trade of any qualifying vessel which had been used in the United States foreign trade shall be disregarded for purposes of this subchapter until an occurrence described in paragraph (3) if the electing entity gives timely notice to the Secretary stating--
Inserted: "(A) that it temporarily operates or has operated in the United States domestic trade a qualifying vessel which had been used in the United States foreign trade, and
Inserted: "(B) its intention to resume operation of the vessel in the United States foreign trade.
Inserted: "(2) Notice shall be deemed timely if given not later than the due date (including extensions) for the electing entity's tax return (as set forth in section 6072(b)) for the taxable year in which the temporary cessation begins.
Inserted: "(3) The disregard provided by paragraph (1) continues until the earlier to occur of--
Inserted: "(A) the electing entity abandoning its intention to resume operations of the vessel in the United States foreign trade, or
Inserted: "(B) the electing entity resuming operation of the vessel in the United States foreign trade.
Inserted: "(f) Effect of Change in Use.--
Inserted: "(1) Except as provided in subsection (e), a vessel that is used other than for operations in the United States foreign trade on other than a temporary basis ceases to be a qualifying vessel when such use begins.
Inserted: "(2) For purposes of this subsection, a change in use of a vessel, other than a commencement of operation in the United States domestic trade, is taken to be permanent unless there are circumstances indicating that it is temporary.
Inserted: "(g) Regulations.--The Secretary shall prescribe such regulations as may be necessary or appropriate to carry out the purposes of this section.
Inserted: "SEC. 1356. QUALIFYING SHIPPING ACTIVITIES.
Inserted: "(a) Qualifying Shipping Activities.--For purposes of this subchapter, the term 'qualifying shipping activities' means the activities of an electing entity which consist of--
Inserted: "(1) its core qualifying activities,
Inserted: "(2) its qualifying secondary activities, and
Inserted: "(3) its qualifying incidental activities.
Inserted: "(b) Core Qualifying Activities.--
Inserted: "(1) The core qualifying activities of an electing entity are--
Inserted: "(A) its activities in operating qualifying vessels in United States foreign trade, and
Inserted: "(B) other activities of the electing entity and other members of its electing group that are an integral part of its business of operating qualifying vessels in United States foreign trade, including ownership or operation of barges, containers, chassis, and other equipment that are the complement of, or used in connection with, a qualifying vessel in United States foreign trade, the inland haulage of cargo shipped, or to be shipped, on qualifying vessels in United States foreign trade, and the provision of terminal, maintenance, repair, logistical, or other vessel, container, or cargo-related services that are an integral part of operating qualifying vessels in United States foreign trade.
Inserted: "(2) Core qualifying activities do not include the provision by an entity of facilities or services to any person, other than--
Inserted: "(A) another member of such entity's electing group,
Inserted: "(B) a consignor, consignee, or other customer of such entity's business of operating qualifying vessels in United States foreign trade, or
Inserted: "(C) a member of an alliance, joint venture, pool, partnership, or similar undertaking involving the operation of qualifying vessels in United States foreign trade of which such entity is a member.
Inserted: "(c) Qualifying Secondary Activities.--For purposes of this subsection--
Inserted: "(1) the term 'secondary activities' means activities that are not core qualifying activities, and--
Inserted: "(A) are the active management or operation of vessels in the United States foreign trade,
Inserted: "(B) the provision of vessel, container, or cargo-related facilities or services to any person, or
Inserted: "(C) such other activities as may be prescribed by the Secretary pursuant to regulations, and
Inserted: "(2) the qualified secondary activities of an electing entity are its secondary activities and the secondary activities of other members of its electing group, but only to the extent that, without regard to this subchapter, the aggregate gross income derived by the electing entity and the other members of its electing group from such activities does not exceed 20 percent of the aggregate gross income derived by the electing entity and the other members of its electing group from their core qualifying activities.
Inserted: "(d) Qualifying Incidental Activities.--Shipping-related activities carried on by an electing entity or another member of its electing group are qualified incidental activities of the electing entity if--
Inserted: "(1) they are incidental to its core qualifying activities,
Inserted: "(2) they are not qualifying secondary activities, and
Inserted: "(3) without regard to this subchapter, the aggregate gross income derived by the electing entity and other members of its electing group from such activities does not exceed 0.1 percent of such entities' aggregate gross income from their core qualifying activities.
Inserted: "SEC. 1357. ITEMS NOT SUBJECT TO REGULAR TAX; DEPRECIATION; INTEREST.
Inserted: "(a) Exclusion From Gross Income.--Gross income of an electing entity shall not include the corporate income percentage of--
Inserted: "(1) its income from qualifying shipping activities in the United States foreign trade,
Inserted: "(2) its income from money, bank deposits, and other temporary investments which are reasonably necessary to meet the working capital requirements of its qualifying shipping activities, and
Inserted: "(3) its income from money or other intangible assets accumulated pursuant to a plan to purchase qualifying shipping assets.
Inserted: "(b) Electing Group Member.--Gross income of a member of an electing group that is not an electing entity shall not include the corporate income percentage of its income from qualifying shipping activities that are taken into account under this subchapter as qualifying shipping activities of an electing entity.
Inserted: "(c) Denial of Losses, Deductions, and Credits.--
Inserted: "(1) General rule.--Subject to paragraph (2), the corporate loss percentage of each item of loss, deduction (other than for interest expense), or credit of any taxpayer with respect to any activity the income from which is excluded from gross income under this section shall be disallowed.
Inserted: "(2) Depreciation.--Notwithstanding paragraph (1), the deduction for depreciation of a qualifying shipping asset shall be allowed in determining the adjusted basis of such asset for purposes of determining gain from its disposition.
Inserted: "(A) Except as provided in subparagraph (B), the straight line method of depreciation shall apply to the corporate income percentage of qualifying shipping assets the income from operation of which is excluded from gross income under this section.
Inserted: "(B) Subparagraph (A) shall not apply to any qualifying shipping asset which is subject to a charter entered into prior to the effective date of this subchapter.
Inserted: "(3) Interest.--The corporate loss percentage of an electing entity's interest expense shall be disallowed in the ratio that the fair market value of its qualifying vessel assets bears to the fair market value of its total assets.
Inserted: "(d) Section Inapplicable to Unrelated Persons.--This section shall not apply to a taxpayer that is not a member of an electing group.
Inserted: "SEC. 1358. ALLOCATION OF CREDITS, INCOME, AND DEDUCTIONS.
Inserted: "(a) Qualifying Shipping Activities.--For purposes of this chapter the qualifying shipping activities of an electing entity shall be treated as a separate trade or business activity distinct from all other activities conducted by the entity.
Inserted: "(b) Exclusion of Credits or Deductions.--
Inserted: "(1) No deduction shall be allowed against the taxable income of an electing corporation from qualifying shipping activities, and no credit shall be allowed against the tax imposed by section 1352(b).
Inserted: "(2) No deduction shall be allowed for any net operating loss attributable to the qualifying shipping activities of a corporation to the extent that such loss is carried forward by the corporation from a taxable year preceding the first taxable year for which such corporation was an electing corporation.
Inserted: "(c) Transactions not at Arm's Length.--Section 482 applies in accordance with this subsection to a transaction or series of transactions--
Inserted: "(1) as between an electing entity and another person, or
Inserted: "(2) as between an entity's qualifying shipping activities and other activities carried on by it.
Inserted: "SEC. 1359. DISPOSITION OF QUALIFYING SHIPPING ASSETS.
Inserted: "(a) In General.--If an electing entity sells or disposes of qualifying shipping assets (as defined in subsection (c)) in an otherwise taxable transaction, at the election of the entity no gain shall be recognized if replacement qualifying shipping assets are acquired during the period specified in subsection (b), except to the extent that the amount realized upon such sale or disposition exceeds the cost of the replacement qualifying shipping assets.
Inserted: "(b) Period Within Which Property Must Be Replaced.--The period referred to in subsection (a) shall be the period beginning 1 year prior to the disposition of the qualifying shipping assets and ending--
Inserted: "(1) 3 years after the close of the first taxable year in which the gain is realized, or
Inserted: "(2) subject to such terms and conditions as may be specified by the Secretary, on such later date as the Secretary may designate on application by the taxpayer. Such application shall be made at such time and in such manner as the Secretary may by regulations prescribe.
Inserted: "(c) Time for Assessment of Deficiency Attributable to Gain.--If an electing entity has made the election provided in subsection (a), then--
Inserted: "(1) the statutory period for the assessment of any deficiency, for any taxable year in which any part of the gain is realized, attributable to such gain shall not expire prior to the expiration of 3 years from the date the Secretary is notified by the entity (in such manner as the Secretary may by regulations prescribe) of the replacement tonnage tax property or of an intention not to replace, and
Inserted: "(2) such deficiency may be assessed before the expiration of such 3-year period notwithstanding the provisions of section 6212(c) or the provisions of any other law or rule of law which would otherwise prevent such assessment.
Inserted: "(d) Basis of Replacement Qualifying Shipping Assets.--In the case of replacement qualifying shipping assets purchased by an electing entity which resulted in the nonrecognition of any part of the gain realized as the result of a sale or other disposition of qualifying shipping assets, the basis shall be the cost of such property decreased in the amount of the gain not so recognized; and if the property purchased consists of more than 1 piece of property, the basis determined under this sentence shall be allocated to the purchased properties in proportion to their respective costs.
Inserted: "(e) Replacement Qualifying Shipping Assets Must Be Acquired From Unrelated Person in Certain Cases.--
Inserted: "(1) In general.--Subsection (a) shall not apply if the replacement qualifying shipping assets are acquired from a related person except to the extent that the related person acquired the replacement qualifying shipping assets from an unrelated person during the period applicable under subsection (b).
Inserted: "(2) Related person.--For purposes of this subsection, a person is related to another person if the person bears a relationship to the other person described in section 267(b) or 707(b)(1).".
Inserted: (b) Technical and Conforming Amendment.--The second sentence of section 56(g)(4)(B)(i) is amended by striking "or under section 114." and inserting ", under section 114 or under section 1357.".
Inserted: (c) Clerical Amendment.--The table of subchapters for chapter 1 is amended by inserting after the item relating to subchapter Q the following new item:
Inserted: "Subchapter A. Election To Determine Taxable Income From Certain International Shipping Activities Using per Ton Rate.".
Inserted: (d) Effective Date.--The amendments made by this section shall apply to taxable years beginning after the date of the enactment of this Act.
Inserted: SEC. __. INCOME OF MERCHANT SEAMAN EXCLUDABLE FROM GROSS INCOME AS FOREIGN EARNED INCOME.
Inserted: (a) In General.--Section 911(d) (relating to citizens or residents of the United States living abroad) is amended by redesignating paragraph (9) as paragraph (10) and by inserting after paragraph (8) the following:
Inserted: "(9) Application to certain merchant marine crews.--In applying this section to an individual who is a citizen or resident of the United States and who is employed for a minimum of 90 days during a taxable year as a regular member of the crew of a qualified vessel (as defined in section 1355)--
Inserted: "(A) the individual shall be treated as a qualified individual without regard to the requirements of paragraph (1), and
Inserted: "(B) any earned income attributable to services performed by that individual so employed on such a vessel while it is engaged in transportation between the United States and a foreign country or possession of the United States shall be treated (except as provided by subsection (b)(1)(B)) as foreign earned income regardless of the source of such income.".
Inserted: (b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after the date of the enactment of this Act.
Original wording
On page 146, after line 23, add the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 2763. Mr. BREAUX (for himself and Mr. Lott) submitted an amendment intended to be proposed by him to the bill S. 1637, to amend the Internal Revenue Code of 1986 to comply with the World Trade Organization rulings on the FSC/ETI benefit in a manner that preserves jobs and production activities in the United States, to reform and simplify the international taxation rules of the United States, and for other purposes; which was ordered to lie on the table; as follows:
On page 146, after line 23, add the following:
SEC. __. REPEAL OF FOREIGN BASE COMPANY SHIPPING INCOME FOR QUALIFIED U.S. FLAG FLEETS AND CARIBBEAN BASIN SHIPPING CORPORATIONS.
(a) In General.--Subsection (f) of section 954 is amended to read as follows:
“(f) Foreign Base Company Shipping Income.--For purposes of subsection (a)(4)--
“(1) In General.--The term ‘foreign base company shipping income' means income derived from, or in connection with, the use (or hiring or leasing for use) of any aircraft or vessel in foreign commerce, or from, or in connection with, the performance of services directly related to the use of any such aircraft, or vessel, or from the sale, exchange, or other disposition of any such aircraft or vessel. Such term includes, but is not limited to--
“(A) dividends and interest received from a foreign corporation in respect of which taxes are deemed paid under section 902, and gain from the sale, exchange, or other disposition of stock or obligations of such a foreign corporation to the extent that such dividends, interest, and gains are attributable to foreign base company shipping income, and
“(B) that portion of the distributive share of the income of a partnership attributable to foreign base company shipping income.
Such term includes any income derived from a space or ocean activity (as defined in section 863(d)(2)). Except as provided in subparagraph (A), such term shall not include any dividend or interest income which is foreign personal holding company income (as defined in subsection (c)).
“(2) Exceptions.--
“(A) In general.--Such term shall not include income attributable to a qualified U.S.-flag fleet or a Caribbean Basin shipping corporation.
“(B) Qualified u.s.-flag fleet.--For purposes of this subsection, the term ‘qualified U.S.-flag fleet' means a fleet or 2 or vessels each of which--
“(i) is documented under the laws of the United States,
“(ii) has a deadweight tonnage of not less than 10,000 deadweight tons,
“(iii) are owned by a member of the controlled group (within the meaning of section 1563) of the controlled foreign corporation, and
“(iv) has been in operation for not less than 320 days during the preceding taxable year.
For purposes of clause (iv), days during which a vessel is dry docked or undergoing survey, inspection, or repair shall be considered to be days during which the vessel is operated.
“(C) Caribbean basin shipping corporation.--For purposes of this subsection--
“(i) In general.--The term ‘Caribbean Basin shipping corporation' means a corporation of which 75 percent of the foreign base company shipping income (as defined in paragraph (1)) for the taxable year is Caribbean Basin shipping income.
“(ii) Caribbean basin shipping income.--The term ‘Caribbean Basin shipping income' means foreign base company shipping income (as defined in paragraph (1)) derived from or in connection with the operation of any nonpassenger vessel in foreign commerce--
“(I) within any Caribbean Basin country,
“(II) among Caribbean Basin countries, or
“(III) between any Caribbean Basin country and the United States.
Such term includes any such foreign base company shipping income derived from that portion of any transshipping originating or terminating in any country which is not a Carribean Basin country if such transshipping otherwise satisfies the requirements of this clause.
“(iii) Caribbean basin country.--The term ‘Caribbean Basin country' means any beneficiary country (within the meaning of section 212(a)(1)(A) of the Caribbean Basin Economic Recovery Act), except that such term shall also include Anguilla, Colombia, Mexico, the United States Virgin Islands, and Venezuela.”.
SEC. __. INCOME OF MERCHANT SEAMAN EXCLUDABLE FROM GROSS INCOME AS FOREIGN EARNED INCOME.
(a) In General.--Chapter 1 is amended by inserting after subchapter Q the following new subchapter:
“Subchapter R--Election to Determine Taxable Income From Certain International Shipping Activities Using per Ton Rate
“Sec. 1352. Alternative tax on qualifying shipping activities.
“Sec. 1353. Taxable income from qualifying shipping activities.
“Sec. 1354. Qualifying shipping tax election; revocation; termination.
“Sec. 1355. Definitions and special rules.
“Sec. 1356. Qualifying shipping activities.
“Sec. 1357. Items not subject to regular tax; depreciation; interest.
“Sec. 1358. Allocation of credits, income, and deductions.
“Sec. 1359. Disposition of qualifying shipping assets.
“SEC. 1352. ALTERNATIVE TAX ON QUALIFYING SHIPPING ACTIVITIES.
“(a) In General.--In the case of an electing corporation--
“(1) the taxable income of such corporation from qualifying shipping activities shall be the amount determined under this subchapter, and
“(2) the corporate percentages of the items of income, gain, loss, deduction, or credit of such corporation and of other members of the electing group of such corporation which would otherwise be taken into account by reason of its qualifying shipping activities shall be taken into account to the extent provided in section 1357.
“(b) Alternative Tax.--The taxable income of an electing corporation from qualifying shipping activities, if otherwise taxable under section 11, 882, or 887, shall be subject to tax only under this section at the maximum rate specified in section 11(b).
“(c) Transfers to Federal Vessel Financing Fund.--The Secretary of the Treasury shall transfer to the Federal Vessel Financing Fund created under title XI of the Merchant Marine Act, 1936, the taxes collected under subsection (b). Notwithstanding the preceding sentence, the income of a foreign corporation shall not be subject to tax under this subchapter to the extent its income is excludable from gross income under section 883(a)(1) or section 894(a).
“SEC. 1353. TAXABLE INCOME FROM QUALIFYING SHIPPING ACTIVITIES.
“(a) In General.--For purposes of this subchapter, the taxable income of an electing corporation from qualifying shipping activities shall be its corporate income percentage of the sum of the amounts determined under subsection (b) for each qualifying vessel operated by such electing corporation or other electing entity.
“(b) Amounts.--For purposes of subsection (a), the amount of taxable income of an electing entity for each qualifying vessel shall equal the product of--
“(1) the daily notional taxable income from the operation of the qualifying vessel in United States foreign trade, and
“(2) the number of days during the taxable year that the electing entity operated such vessel as a qualifying vessel in United States foreign trade.
“(c) Daily Notional Taxable Income.--For purposes of subsection (b), the daily notional taxable income from the operation of a qualifying vessel is--
“(1) 40 cents for each 100 tons of the net tonnage of the vessel below 25,001 net tons, and
“(2) 20 cents for each 100 tons of the net tonnage of the vessel in excess of 25,000 net tons.
“(d) Multiple Operators of Vessel.--If 2 or more persons have a joint interest in a qualifying vessel and are considered as operators of that vessel, the taxable income from the operation of such vessel for that time (as determined under this section) shall be allocated among such persons on the basis of their ownership and charter interests in such vessel or on such other basis as the Secretary may prescribe by regulations.
“(e) Noncorporate Percentage.--Notwithstanding any contrary provision of this subchapter, the noncorporate percentage of any item of income, gain, loss, deduction, or credit of any member of an electing group shall be taken into account for all purposes of this subtitle as if this subchapter were not in effect.
“SEC. 1354. QUALIFYING SHIPPING TAX ELECTION; REVOCATION; TERMINATION.
“(a) In General.--Except as provided in subsections (b) and (f), a qualifying shipping tax election may be made in respect of any qualifying entity.
“(b) Condition of Election.--An election may be made by a member of a controlled group under this subsection for any taxable year only if all qualifying entities that are members of the controlled group join in the election.
“(c) When Made.--An election under subsection (a) may be made by a qualifying entity in such form as prescribed by the Secretary. Such election shall be filed with the qualifying entity's return for the first taxable year to which the election shall apply, by the due date for such return (including any applicable extensions).
“(d) Years for Which Effective.--An election under subsection (a) shall be effective for the taxable year of the qualifying entity for which it is made and for all succeeding taxable years of the entity, until such election is terminated under subsection (e).
“(e) Termination.--
“(1) By revocation.--
“(A) In general.--An election under subsection (a) may be terminated by revocation.
“(B) When effective.--Except as provided in subparagraph (C)--
“(i) a revocation made during the taxable year and on or before the fifteenth day of the third month thereof shall be effective on the 1st day of such taxable year, and
“(ii) a revocation made during the taxable year but after such fifteenth day shall be effective on the first day of the following taxable year.
“(C) Revocation may specify prospective date.--If the revocation specifies a date for revocation which is on or after the day on which the revocation is made, the revocation shall be effective on and after the date so specified.
“(2) By entity ceasing to be qualifying entity.--
“(A) In general.--An election under subsection (a) shall be terminated whenever (at any time on or after the first day of the first taxable year for which the entity is an electing entity) such entity ceases to be a qualifying entity.
“(B) When effective.--Any termination under this paragraph shall be effective on and after the date of cessation.
“(f) Election After Termination.--If a qualifying entity has made an election under subsection (a) and if such election has been terminated under subsection (e), such entity (and any successor entity) shall not be eligible to make an election under subsection (a) for any taxable year before its fifth taxable year which begins after the first taxable year for which such termination is effective, unless the Secretary consents to such election.
“SEC. 1355. DEFINITIONS AND SPECIAL RULES.
“(a) Definitions.--For purposes of this subchapter:
“(1) Controlled group.--The term ‘controlled group' means any group of trusts and business entities whose members would be treated as a single employer under the rules of section 52(a) (without regard to paragraphs (1) and (2) thereof) and section 52(b)(1).
“(2) Corporate income percentage.--The term ‘corporate income percentage' means the least aggregate share, expressed as a percentage, of any item of income or gain of an electing corporation or electing group of which such corporation is a member from qualifying shipping activities that would, but for an election in effect under this subchapter, be required to be reported on the Federal income tax return of an electing corporation during any taxable period. In the case of an electing group which includes 2 or more electing corporations, the corporate income percentage of each such corporation shall be determined on the basis of such corporation's direct and indirect ownership and charter interests in qualifying vessels of the electing group or on such other basis as the Secretary may prescribe by regulations.
“(3) Corporate loss percentage.--The term ‘corporate loss percentage' means the greatest aggregate share, expressed as a percentage, of any item of loss, deduction, or credit of an electing corporation or electing group of which such corporation is a member from qualifying shipping activities that would, but for an election in effect under this subchapter, be required to be reported on the Federal income tax return of an electing corporation during any taxable period.
“(4) Corporate percentages.--The term ‘corporate percentages' means the corporate income percentage and the corporate loss percentage.
“(5) Electing corporation.--The term ‘electing corporation' means any C corporation that is an electing entity or that would, but for an election in effect under this subchapter, be required to report any item of income, gain, loss, deduction, or credit of an electing entity on its Federal income tax return.
“(6) Electing entity.--The term ‘electing entity' means any qualifying entity for which an election is in effect under this subchapter.
“(7) Electing group.--The term ‘electing group' means a controlled group of which one or more members is an electing entity.
“(8) Noncorporate percentage.--The term ‘noncorporate percentage' means the difference between 100 percent and the corporate income percentage or corporate loss percentage, as applicable.
“(9) Qualifying entity.--The term ‘qualifying entity' means a trust or business entity that--
“(A) operates 1 or more qualifying vessels, and
“(B) meets the shipping activity requirement in subsection (c).
“(10) Qualifying shipping assets.--The term ‘qualifying shipping assets' means any qualifying vessel and other assets which are used in core qualifying activities as described in section 1356(b).
“(11) Qualifying vessel.--The term ‘qualifying vessel' means a self-propelled (or a combination self-propelled and non-self-propelled) United States flag vessel of not less than 10,000 deadweight tons used in the United States foreign trade.
“(12) United states domestic trade.--The term ‘United States domestic trade' means the transportation of goods or passengers between places in the United States.
“(13) United states flag vessel.--The term ‘United States flag vessel' means any vessel documented under the laws of the United States.
“(14) United states foreign trade.--The term ‘United States foreign trade' means the transportation of goods or passengers between a place in the United States and a foreign place or between foreign places.
“(b) Operating a Vessel.--For purposes of this subchapter:
“(1) Except as provided in paragraph (2), an entity is treated as operating any vessel owned by, or chartered (including a time charter) to, the entity.
“(2) An entity is treated as operating a vessel that it has chartered out on bareboat charter terms only if--
“(A) the vessel is temporarily surplus to the entity's requirements and the term of the charter does not exceed 3 years; or
“(B) the vessel is bareboat chartered to a member of a controlled group which includes such entity or to an unrelated third party that sub-bareboats or time charters the vessel to a member of such controlled group (including the owner).
“(c) Shipping Activity Requirement.--For purposes of this section, the shipping activity requirement is met for a taxable year only by an entity described in paragraph (1), (2), or (3).
“(1) An entity in the first taxable year of its qualifying shipping tax election if, for the preceding taxable year, the test in paragraph (4) is met.
“(2) An entity in the second or any subsequent taxable year of its qualifying shipping tax election if, for each of the 2 preceding taxable years, the test in paragraph (4) is met.
“(3) An entity that would be described in paragraph (1) or (2) if the test in paragraph (4) were applied on an aggregate basis to the controlled group of which such entity is a member, and vessel charters between members of the controlled group were disregarded.
“(4) The test in this paragraph is met if on average at least 25 percent of the aggregate tonnage of qualifying vessels operated by the entity were owned by the entity or chartered to the entity on bareboat charter terms. For purposes of the preceding sentence, vessels chartered (including time chartered) to an entity by a member of a controlled group which includes the entity, or by a third party that bareboat charters the vessels from the entity or a member of the entity's controlled group, shall be treated as chartered to the entity on bareboat charter terms.
“(d) Effect of Temporarily Ceasing To Operate a Qualifying Vessel.--
“(1) A temporary cessation by an electing entity, in operation of a qualifying vessel shall be disregarded for purposes of subsections (b) and (c) until an occurrence described in paragraph (3) if the electing entity gives timely notice to the Secretary stating--
“(A) that it has temporarily ceased to operate the qualifying vessel, and
“(B) its intention to resume operating the qualifying vessel.
“(2) Notice shall be deemed timely if given not later than the due date (including extensions) for the electing entity's tax return (as set forth in section 6072(b)) for the taxable year in which the temporary cessation begins.
“(3) The disregard provided by paragraph (1) continues until the earlier to occur of--
“(A) the electing entity abandoning its intention to resume operation of the qualifying vessel, or
“(B) the electing entity resuming operation of the qualifying vessel.
“(e) Effect of Temporarily Operating a Qualifying Vessel in the United States Domestic Trade.--
“(1) The temporary operation in the United States domestic trade of any qualifying vessel which had been used in the United States foreign trade shall be disregarded for purposes of this subchapter until an occurrence described in paragraph (3) if the electing entity gives timely notice to the Secretary stating--
“(A) that it temporarily operates or has operated in the United States domestic trade a qualifying vessel which had been used in the United States foreign trade, and
“(B) its intention to resume operation of the vessel in the United States foreign trade.
“(2) Notice shall be deemed timely if given not later than the due date (including extensions) for the electing entity's tax return (as set forth in section 6072(b)) for the taxable year in which the temporary cessation begins.
“(3) The disregard provided by paragraph (1) continues until the earlier to occur of--
“(A) the electing entity abandoning its intention to resume operations of the vessel in the United States foreign trade, or
“(B) the electing entity resuming operation of the vessel in the United States foreign trade.
“(f) Effect of Change in Use.--
“(1) Except as provided in subsection (e), a vessel that is used other than for operations in the United States foreign trade on other than a temporary basis ceases to be a qualifying vessel when such use begins.
“(2) For purposes of this subsection, a change in use of a vessel, other than a commencement of operation in the United States domestic trade, is taken to be permanent unless there are circumstances indicating that it is temporary.
“(g) Regulations.--The Secretary shall prescribe such regulations as may be necessary or appropriate to carry out the purposes of this section.
“SEC. 1356. QUALIFYING SHIPPING ACTIVITIES.
“(a) Qualifying Shipping Activities.--For purposes of this subchapter, the term ‘qualifying shipping activities' means the activities of an electing entity which consist of--
“(1) its core qualifying activities,
“(2) its qualifying secondary activities, and
“(3) its qualifying incidental activities.
“(b) Core Qualifying Activities.--
“(1) The core qualifying activities of an electing entity are--
“(A) its activities in operating qualifying vessels in United States foreign trade, and
“(B) other activities of the electing entity and other members of its electing group that are an integral part of its business of operating qualifying vessels in United States foreign trade, including ownership or operation of barges, containers, chassis, and other equipment that are the complement of, or used in connection with, a qualifying vessel in United States foreign trade, the inland haulage of cargo shipped, or to be shipped, on qualifying vessels in United States foreign trade, and the provision of terminal, maintenance, repair, logistical, or other vessel, container, or cargo-related services that are an integral part of operating qualifying vessels in United States foreign trade.
“(2) Core qualifying activities do not include the provision by an entity of facilities or services to any person, other than--
“(A) another member of such entity's electing group,
“(B) a consignor, consignee, or other customer of such entity's business of operating qualifying vessels in United States foreign trade, or
“(C) a member of an alliance, joint venture, pool, partnership, or similar undertaking involving the operation of qualifying vessels in United States foreign trade of which such entity is a member.
“(c) Qualifying Secondary Activities.--For purposes of this subsection--
“(1) the term ‘secondary activities' means activities that are not core qualifying activities, and--
“(A) are the active management or operation of vessels in the United States foreign trade,
“(B) the provision of vessel, container, or cargo-related facilities or services to any person, or
“(C) such other activities as may be prescribed by the Secretary pursuant to regulations, and
“(2) the qualified secondary activities of an electing entity are its secondary activities and the secondary activities of other members of its electing group, but only to the extent that, without regard to this subchapter, the aggregate gross income derived by the electing entity and the other members of its electing group from such activities does not exceed 20 percent of the aggregate gross income derived by the electing entity and the other members of its electing group from their core qualifying activities.
“(d) Qualifying Incidental Activities.--Shipping-related activities carried on by an electing entity or another member of its electing group are qualified incidental activities of the electing entity if--
“(1) they are incidental to its core qualifying activities,
“(2) they are not qualifying secondary activities, and
“(3) without regard to this subchapter, the aggregate gross income derived by the electing entity and other members of its electing group from such activities does not exceed 0.1 percent of such entities' aggregate gross income from their core qualifying activities.
“SEC. 1357. ITEMS NOT SUBJECT TO REGULAR TAX; DEPRECIATION; INTEREST.
“(a) Exclusion From Gross Income.--Gross income of an electing entity shall not include the corporate income percentage of--
“(1) its income from qualifying shipping activities in the United States foreign trade,
“(2) its income from money, bank deposits, and other temporary investments which are reasonably necessary to meet the working capital requirements of its qualifying shipping activities, and
“(3) its income from money or other intangible assets accumulated pursuant to a plan to purchase qualifying shipping assets.
“(b) Electing Group Member.--Gross income of a member of an electing group that is not an electing entity shall not include the corporate income percentage of its income from qualifying shipping activities that are taken into account under this subchapter as qualifying shipping activities of an electing entity.
“(c) Denial of Losses, Deductions, and Credits.--
“(1) General rule.--Subject to paragraph (2), the corporate loss percentage of each item of loss, deduction (other than for interest expense), or credit of any taxpayer with respect to any activity the income from which is excluded from gross income under this section shall be disallowed.
“(2) Depreciation.--Notwithstanding paragraph (1), the deduction for depreciation of a qualifying shipping asset shall be allowed in determining the adjusted basis of such asset for purposes of determining gain from its disposition.
“(A) Except as provided in subparagraph (B), the straight line method of depreciation shall apply to the corporate income percentage of qualifying shipping assets the income from operation of which is excluded from gross income under this section.
“(B) Subparagraph (A) shall not apply to any qualifying shipping asset which is subject to a charter entered into prior to the effective date of this subchapter.
“(3) Interest.--The corporate loss percentage of an electing entity's interest expense shall be disallowed in the ratio that the fair market value of its qualifying vessel assets bears to the fair market value of its total assets.
“(d) Section Inapplicable to Unrelated Persons.--This section shall not apply to a taxpayer that is not a member of an electing group.
“SEC. 1358. ALLOCATION OF CREDITS, INCOME, AND DEDUCTIONS.
“(a) Qualifying Shipping Activities.--For purposes of this chapter the qualifying shipping activities of an electing entity shall be treated as a separate trade or business activity distinct from all other activities conducted by the entity.
“(b) Exclusion of Credits or Deductions.--
“(1) No deduction shall be allowed against the taxable income of an electing corporation from qualifying shipping activities, and no credit shall be allowed against the tax imposed by section 1352(b).
“(2) No deduction shall be allowed for any net operating loss attributable to the qualifying shipping activities of a corporation to the extent that such loss is carried forward by the corporation from a taxable year preceding the first taxable year for which such corporation was an electing corporation.
“(c) Transactions not at Arm's Length.--Section 482 applies in accordance with this subsection to a transaction or series of transactions--
“(1) as between an electing entity and another person, or
“(2) as between an entity's qualifying shipping activities and other activities carried on by it.
“SEC. 1359. DISPOSITION OF QUALIFYING SHIPPING ASSETS.
“(a) In General.--If an electing entity sells or disposes of qualifying shipping assets (as defined in subsection (c)) in an otherwise taxable transaction, at the election of the entity no gain shall be recognized if replacement qualifying shipping assets are acquired during the period specified in subsection (b), except to the extent that the amount realized upon such sale or disposition exceeds the cost of the replacement qualifying shipping assets.
“(b) Period Within Which Property Must Be Replaced.--The period referred to in subsection (a) shall be the period beginning 1 year prior to the disposition of the qualifying shipping assets and ending--
“(1) 3 years after the close of the first taxable year in which the gain is realized, or
“(2) subject to such terms and conditions as may be specified by the Secretary, on such later date as the Secretary may designate on application by the taxpayer. Such application shall be made at such time and in such manner as the Secretary may by regulations prescribe.
“(c) Time for Assessment of Deficiency Attributable to Gain.--If an electing entity has made the election provided in subsection (a), then--
“(1) the statutory period for the assessment of any deficiency, for any taxable year in which any part of the gain is realized, attributable to such gain shall not expire prior to the expiration of 3 years from the date the Secretary is notified by the entity (in such manner as the Secretary may by regulations prescribe) of the replacement tonnage tax property or of an intention not to replace, and
“(2) such deficiency may be assessed before the expiration of such 3-year period notwithstanding the provisions of section 6212(c) or the provisions of any other law or rule of law which would otherwise prevent such assessment.
“(d) Basis of Replacement Qualifying Shipping Assets.--In the case of replacement qualifying shipping assets purchased by an electing entity which resulted in the nonrecognition of any part of the gain realized as the result of a sale or other disposition of qualifying shipping assets, the basis shall be the cost of such property decreased in the amount of the gain not so recognized; and if the property purchased consists of more than 1 piece of property, the basis determined under this sentence shall be allocated to the purchased properties in proportion to their respective costs.
“(e) Replacement Qualifying Shipping Assets Must Be Acquired From Unrelated Person in Certain Cases.--
“(1) In general.--Subsection (a) shall not apply if the replacement qualifying shipping assets are acquired from a related person except to the extent that the related person acquired the replacement qualifying shipping assets from an unrelated person during the period applicable under subsection (b).
“(2) Related person.--For purposes of this subsection, a person is related to another person if the person bears a relationship to the other person described in section 267(b) or 707(b)(1).”.
(b) Technical and Conforming Amendment.--The second sentence of section 56(g)(4)(B)(i) is amended by striking “or under section 114.” and inserting “, under section 114 or under section 1357.”.
(c) Clerical Amendment.--The table of subchapters for chapter 1 is amended by inserting after the item relating to subchapter Q the following new item:
“Subchapter A. Election To Determine Taxable Income From Certain International Shipping Activities Using per Ton Rate.”.
(d) Effective Date.--The amendments made by this section shall apply to taxable years beginning after the date of the enactment of this Act.
SEC. __. INCOME OF MERCHANT SEAMAN EXCLUDABLE FROM GROSS INCOME AS FOREIGN EARNED INCOME.
(a) In General.--Section 911(d) (relating to citizens or residents of the United States living abroad) is amended by redesignating paragraph (9) as paragraph (10) and by inserting after paragraph (8) the following:
“(9) Application to certain merchant marine crews.--In applying this section to an individual who is a citizen or resident of the United States and who is employed for a minimum of 90 days during a taxable year as a regular member of the crew of a qualified vessel (as defined in section 1355)--
“(A) the individual shall be treated as a qualified individual without regard to the requirements of paragraph (1), and
“(B) any earned income attributable to services performed by that individual so employed on such a vessel while it is engaged in transportation between the United States and a foreign country or possession of the United States shall be treated (except as provided by subsection (b)(1)(B)) as foreign earned income regardless of the source of such income.”.
(b) Effective Date.--The amendment made by this section shall apply to taxable years beginning after the date of the enactment of this Act.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
March 10, 2004