S.Amdt. 2887
What it does: Adds SEC. __. MANUFACTURER'S JOBS CREDIT at the end of title I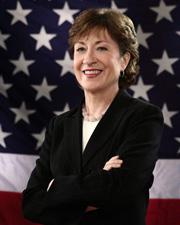 Sen. Susan M. Collins (R-ME)
What it changes
1 change to S. 1637 · shown in the bill's text
Adds SEC. __. MANUFACTURER'S JOBS CREDIT at the end of title I
Adds a sectionIn S. 1637 · Reported to Senate
(2) Application of section 15.--Section 15 of the Internal Revenue Code of 1986 shall apply to the amendments made by this section as if they were changes in a rate of tax.
Inserted: SEC. __. MANUFACTURER'S JOBS CREDIT.
Inserted: (a) In General.--Subpart D of part IV of subchapter A of chapter 1 (relating to business-related credits) is amended by adding at the end the following:
Inserted: "SEC. 45G. MANUFACTURER'S JOBS CREDIT.
Inserted: "(a) General Rule.--For purposes of section 38, in the case of an eligible taxpayer, the manufacturer's jobs credit determined under this section is an amount equal to the lesser of the following:
Inserted: "(1) The excess of the W-2 wages paid by the taxpayer during the taxable year over the W-2 wages paid by the taxpayer during the preceding taxable year.
Inserted: "(2) The W-2 wages paid by the taxpayer during the taxable year to any employee who is an eligible TAA recipient (as defined in section 35(c)(2)) for any month during such taxable year.
Inserted: "(3) 22.4 percent of the W-2 wages paid by the taxpayer during the taxable year.
Inserted: "(b) Limitation.--
Inserted: "(1) In general.--If there is an excess described in paragraph (2)(A) for any taxable year, the amount of credit determined under subsection (a) (without regard to this subsection)--
Inserted: "(A) if the value of domestic production determined under subsection (g)(2) for the taxable year does not exceed such value for the preceding taxable year, shall be zero, and
Inserted: "(B) if subparagraph (A) does not apply, shall be reduced (but not below zero) by the applicable percentage of such amount.
Inserted: "(2) Applicable percentage.--For purposes of paragraph (1), the term 'applicable percentage' means, with respect to any taxable year, the percentage equal to a fraction--
Show 18 more inserted paragraphsShow less
Inserted: "(A) the numerator of which is the excess (if any) of the modified value of worldwide production of the taxpayer for the taxable year over such modified value for the preceding taxable year, and
Inserted: "(B) the denominator of which is the excess (if any) of the value of worldwide production of the taxpayer for the taxable year over such value for the preceding taxable year.
Inserted: "(3) Definitions.--For purposes of this subsection--
Inserted: "(A) Value of worldwide production.--The value of worldwide production for any taxable year shall be determined under subsection (g)(4).
Inserted: "(B) Modified value.--The term 'modified value of worldwide production' means the value of worldwide production determined by not taking into account any item taken into account in determining the value of domestic production under subsection (g)(2).
Inserted: "(c) Eligible Taxpayer.--For purposes of this section, the term 'eligible taxpayer' means any taxpayer--
Inserted: "(1) which has domestic production gross receipts for the taxable year and the preceding taxable year, and
Inserted: "(2) which is not treated at any time during the taxable year as an inverted domestic corporation under section 7874.
Inserted: "(d) Definitions.--For purposes of this section--
Inserted: "(1) In general.--Any term used in this section which is also used in section 199 shall have the meaning given such term by section 199.
Inserted: "(2) Special rule for w-2 wages.--Notwithstanding paragraph (1), the amount of W-2 wages taken into account with respect to any employee for any taxable year shall not exceed $50,000.
Inserted: "(e) Certain Rules Made Applicable.--For purposes of this section, rules similar to the rules of section 52 shall apply.
Inserted: "(f) Termination.--This section shall not apply to any taxable year beginning after December 31, 2005."
Inserted: (b) Credit To Be Part of General Business Credit.--Section 38(b) (relating to current year business credit) is amended by striking "plus" at the end of paragraph (14), by striking the period at the end of paragraph (15) and inserting ", plus", and by adding at the end the following:
Inserted: "(16) the manufacturer's jobs credit determined under section 45G."
Inserted: (c) Clerical Amendment.--The table of sections for subpart D of part IV of subchapter A of chapter 1 is amended by adding at the end the following:
Inserted: "Sec. 45G. Manufacturer's jobs credit."
Inserted: (d) Effective Date.--The amendments made by this section shall apply to taxable years beginning after December 31, 2003.
Original wording
At the end of title I, insert:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 2887. Ms. COLLINS submitted an amendment intended to be proposed by her to the bill S. 1637, to amend the Internal Revenue Code of 1986 to comply with the World Trade Organization rulings on the FSC/ETI benefit in a manner that preserves jobs and production activities in the United States, to reform and simplify the international taxation rules of the United States, and for other purposes; which was ordered to lie on the table; as follows:
At the end of title I, insert:
SEC. __. MANUFACTURER'S JOBS CREDIT.
(a) In General.--Subpart D of part IV of subchapter A of chapter 1 (relating to business-related credits) is amended by adding at the end the following:
“SEC. 45G. MANUFACTURER'S JOBS CREDIT.
“(a) General Rule.--For purposes of section 38, in the case of an eligible taxpayer, the manufacturer's jobs credit determined under this section is an amount equal to the lesser of the following:
“(1) The excess of the W-2 wages paid by the taxpayer during the taxable year over the W-2 wages paid by the taxpayer during the preceding taxable year.
“(2) The W-2 wages paid by the taxpayer during the taxable year to any employee who is an eligible TAA recipient (as defined in section 35(c)(2)) for any month during such taxable year.
“(3) 22.4 percent of the W-2 wages paid by the taxpayer during the taxable year.
“(b) Limitation.--
“(1) In general.--If there is an excess described in paragraph (2)(A) for any taxable year, the amount of credit determined under subsection (a) (without regard to this subsection)--
“(A) if the value of domestic production determined under subsection (g)(2) for the taxable year does not exceed such value for the preceding taxable year, shall be zero, and
“(B) if subparagraph (A) does not apply, shall be reduced (but not below zero) by the applicable percentage of such amount.
“(2) Applicable percentage.--For purposes of paragraph (1), the term ‘applicable percentage' means, with respect to any taxable year, the percentage equal to a fraction--
“(A) the numerator of which is the excess (if any) of the modified value of worldwide production of the taxpayer for the taxable year over such modified value for the preceding taxable year, and
“(B) the denominator of which is the excess (if any) of the value of worldwide production of the taxpayer for the taxable year over such value for the preceding taxable year.
“(3) Definitions.--For purposes of this subsection--
“(A) Value of worldwide production.--The value of worldwide production for any taxable year shall be determined under subsection (g)(4).
“(B) Modified value.--The term ‘modified value of worldwide production' means the value of worldwide production determined by not taking into account any item taken into account in determining the value of domestic production under subsection (g)(2).
“(c) Eligible Taxpayer.--For purposes of this section, the term ‘eligible taxpayer' means any taxpayer--
“(1) which has domestic production gross receipts for the taxable year and the preceding taxable year, and
“(2) which is not treated at any time during the taxable year as an inverted domestic corporation under section 7874.
“(d) Definitions.--For purposes of this section--
“(1) In general.--Any term used in this section which is also used in section 199 shall have the meaning given such term by section 199.
“(2) Special rule for w-2 wages.--Notwithstanding paragraph (1), the amount of W-2 wages taken into account with respect to any employee for any taxable year shall not exceed $50,000.
“(e) Certain Rules Made Applicable.--For purposes of this section, rules similar to the rules of section 52 shall apply.
“(f) Termination.--This section shall not apply to any taxable year beginning after December 31, 2005.”
(b) Credit To Be Part of General Business Credit.--Section 38(b) (relating to current year business credit) is amended by striking “plus” at the end of paragraph (14), by striking the period at the end of paragraph (15) and inserting “, plus”, and by adding at the end the following:
“(16) the manufacturer's jobs credit determined under section 45G.”
(c) Clerical Amendment.--The table of sections for subpart D of part IV of subchapter A of chapter 1 is amended by adding at the end the following:
“Sec. 45G. Manufacturer's jobs credit.”
(d) Effective Date.--The amendments made by this section shall apply to taxable years beginning after December 31, 2003.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
March 22, 2004