To amend the Fair Labor Standards Act of 1938 to clarify provisions relating to overtime pay.
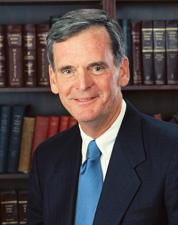 Sen. Judd Gregg (R-NH)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
May 4, 2004
View full timeline
Senate amendment submitted
May 4, 2004
Roll call votes on amendments in Senate: Amendment SA 3111 agreed to in Senate by Yea-Nay Vote. 99 - 0. Record Vote Number: 78.
May 4, 2004
Senate amendment agreed to: Amendment SA 3111 agreed to in Senate by Yea-Nay Vote. 99 - 0. Record Vote Number: 78.
May 4, 2004
Senate amendment proposed (on the floor): Amendment SA 3111 proposed by Senator Gregg.(consideration: CR S4790-4793, S4806; text: CR S4792-4793)
May 4, 2004
Amendment SA 3111 proposed by Senator Gregg. (consideration: CR S4790-4793, S4806; text: CR S4792-4793) To amend the Fair Labor Standards Act of 1938 to clarify provisions relating to overtime pay.
May 4, 2004
Amendment SA 3111 agreed to in Senate by Yea-Nay Vote. 99 - 0. Record Vote Number: 78.
May 4, 2004
Votes
1 roll call on this amendment
Text
Submitted
TEXT OF AMENDMENTS

SA 3110. Mr. DORGAN (for himself, Ms. Mikulski, Mr. Harkin, Mr.
Feingold, Mr. Kennedy, and Mr. Edwards) proposed an amendment to the
bill S. 1637, to amend the Internal Revenue Code of 1986 to comply with
the World Trade Organization rulings on the FSC/ETI benefit in a manner
that preserves jobs and production activities in the United States, to
reform and simplify the international taxation rules of the United
States, and for other purposes; as follows:

At the end of subtitle E of title IV, add the following:

SEC. __. TAXATION OF INCOME OF CONTROLLED FOREIGN
CORPORATIONS ATTRIBUTABLE TO IMPORTED PROPERTY.

(a) General Rule.--Subsection (a) of section 954 (defining
foreign base company income) is amended by striking ``and''
at the end of paragraph (4), by striking the period at the
end of paragraph (5) and inserting ``, and'', and by adding
at the end the following new paragraph:
``(6) imported property income for the taxable year
(determined under subsection (j) and reduced as provided in
subsection (b)(5)).''
(b) Definition of Imported Property Income.--Section 954 is
amended by adding at the end the following new subsection:
``(j) Imported Property Income.--
``(1) In general.--For purposes of subsection (a)(6), the
term `imported property income' means income (whether in the
form of profits, commissions, fees, or otherwise) derived in
connection with--
``(A) manufacturing, producing, growing, or extracting
imported property,
``(B) the sale, exchange, or other disposition of imported
property, or
``(C) the lease, rental, or licensing of imported property.

Such term shall not include any foreign oil and gas
extraction income (within the meaning of section 907(c)) or
any foreign oil related income (within the meaning of section
907(c)).
``(2) Imported property.--For purposes of this subsection--
``(A) In general.--Except as otherwise provided in this
paragraph, the term `imported property' means property which
is imported into the United States by the controlled foreign
corporation or a related person.
``(B) Imported property includes certain property imported
by unrelated persons.--The term `imported property' includes
any property imported into the United States by an unrelated
person if, when such property was sold to the unrelated
person by the controlled foreign corporation (or a related
person), it was reasonable to expect that--
``(i) such property would be imported into the United
States, or
``(ii) such property would be used as a component in other
property which would be imported into the United States.
``(C) Exception for property subsequently exported.--The
term `imported property' does not include any property which
is imported into the United States and which--
``(i) before substantial use in the United States, is sold,
leased, or rented by the controlled foreign corporation or a
related person for direct use, consumption, or disposition
outside the United States, or
``(ii) is used by the controlled foreign corporation or a
related person as a component in other property which is so
sold, leased, or rented.
``(3) Definitions and special rules.--
``(A) Import.--For purposes of this subsection, the term
`import' means entering, or withdrawal from warehouse, for
consumption or use. Such term includes any grant of the right
to use intangible property (as defined in section
936(h)(3)(B)) in the United States.
``(B) United states.--For purposes of this subsection, the
term `United States' includes the Commonwealth of Puerto
Rico, the Virgin Islands of the United States, Guam, American
Samoa, and the Commonwealth of the Northern Mariana Islands.
``(C) Unrelated person.--For purposes of this subsection,
the term `unrelated person' means any person who is not a
related person with respect to the controlled foreign
corporation.
``(D) Coordination with foreign base company sales
income.--For purposes of this section, the term `foreign base
company sales income' shall not include any imported property
income.''
(c) Separate Application of Limitations on Foreign Tax
Credit for Imported Property Income.--
(1) In general.--Paragraph (1) of section 904(d) (relating
to separate application of section with respect to certain
categories of income) is amended by striking ``and'' at the
end of subparagraph (H), by redesignating subparagraph (I) as
subparagraph (J), and by inserting after subparagraph (H) the
following new subparagraph:
``(I) imported property income, and''.
(2) Imported property income defined.--Paragraph (2) of
section 904(d) is amended by redesignating subparagraphs (H)
and (I) as subparagraphs (I) and (J), respectively, and by
inserting after subparagraph (G) the following new
subparagraph:
``(H) Imported property income.--The term `imported
property income' means any income received or accrued by any
person which is of a kind which would be imported property
income (as defined in section 954(j)).''
(3) Look-thru rules to apply.--Subparagraph (F) of section
904(d)(3) is amended by striking ``or (E)'' and inserting
``(E), or (I)''.
(d) Technical Amendments.--
(1) Clause (iii) of section 952(c)(1)(B) (relating to
certain prior year deficits may be taken into account) is
amended--
(A) by redesignating subclauses (III), (IV), (V), and (VI)
as subclauses (IV), (V), (VI), and (VII), and
(B) by inserting after subclause (II) the following new
subclause:
``(III) imported property income,''.
(2) Paragraph (5) of section 954(b) (relating to deductions
to be taken into account) is amended by striking ``and the
foreign base company oil related income'' and inserting ``the
foreign base company oil related income, and the imported
property income''.
(e) Effective Date.--
(1) In general.--Except as provided in paragraph (2), the
amendments made by this section shall apply to taxable years
of foreign corporations beginning after the date of the
enactment of this Act, and to taxable years of United States
shareholders within which or with which such taxable years of
such foreign corporations end.
(2) Subsection (c).--The amendments made by subsection (c)
shall apply to taxable years beginning after such date of
enactment.
(f) Sense of the Senate.--It is the sense of the Senate
that any increase in revenues in the Treasury resulting from
the amendments made by this section should be applied to
reduce the phasein of the deduction relating to income
attributable to domestic production activities under section
199 of the Internal Revenue Code of 1986 (as added by section
102 of this Act).

SEC. __. AMENDMENTS TO THE WORKER ADJUSTMENT AND RETRAINING
NOTIFICATION ACT.

(a) Definition.--Section 2(a) of the Worker Adjustment and
Retraining Notification Act (29 U.S.C. 2101(a)) is amended--
(1) in paragraph (3)(B), by striking ``for--'' and all that
follows through ``500 employees'' in clause (ii), and
inserting ``for at least 50 employees'';
(2) in paragraph (7), by striking ``and'' at the end;
(3) in paragraph (8), by striking the period and inserting
``; and''; and
(4) by adding at the end the following:
``(9) the term `offshoring of jobs' means any action taken
by an employer the effect of which is to create, shift, or
transfer employment positions or facilities outside the
United States and which results in an employment loss during
any 30 day period for 15 or more employees.''.
(b) Notice.--Section 3 of the Worker Adjustment and
Retraining Notification Act (29 U.S.C. 2102) is amended--
(1) in subsection (a)--
(A) in the matter preceding paragraph (1), by striking
``60-day'' and inserting ``90-day''; and
(B) in paragraph (1), by striking ``and'' at the end;
(C) in paragraph (2), by striking the period and inserting
``; and''; and
(D) by inserting after paragraph (2), the following:
``(3) to the Secretary of Labor.'';
(2) in subsection (b), by striking ``60-day'' each place
that such appears and inserting ``90-day''; and
(3) by adding at the end the following:
``(e) Notice for Offshoring of Jobs.--In the case of a
notice under subsection (a) regarding the offshoring of jobs,
the notice shall include, in addition to the information
otherwise required by the Secretary with respect to other
notices under such subsection, information concerning--
``(1) the number of jobs affected;
``(2) the location that the jobs are being shifted or
transferred to; and
``(3) the reasons that such shifting or transferring of
jobs is occurring.''.

[[Page S4847]]

(c) Technical Amendments.--The Worker Adjustment and
Retraining Notification Act (29 U.S.C. 2101 et seq.) is
amended--
(1) by striking ``plant closing or mass layoff'' each place
that such appears and inserting ``plant closing, mass layoff,
or offshoring of jobs'';
(2) by striking ``closing or layoff'' each place that such
appears and inserting ``closing, layoff, or offshoring'';
(3) in section 3--
(A) in the section heading by striking ``PLANT CLOSINGS AND
MASS LAYOFFS'' and inserting ``PLANT CLOSINGS, MASS LAYOFFS,
AND OFFSHORING OF JOBS'';
(B) in subsection (b)(2)(A), by striking ``closing or mass
layoff'' and inserting ``closing, layoff, or offshoring'';
and
(C) in subsection (d), by striking ``section 2(a)(2) or
(3)'' and inserting ``paragraph (2), (3), or (9) of section
2(a)''; and
(4) in section 5(a)(1), in the matter following
subparagraph (B), by striking ``60 days'' and inserting ``90
days''.
(d) Posting of Employee Rights.--The Worker Adjustment and
Retraining Notification Act (29 U.S.C. 2101 et seq.) is
amended by adding at the end the following:

``SEC. 11. POSTING OF NOTICE OF RIGHTS.

``(a) Development.--Not later than 60 days after the date
of enactment of this section, the Secretary of Labor shall
develop a notice of employee rights under this Act for
posting by employers.
``(b) Posting.--Each employer shall post in a conspicuous
place in places of employment the notice of the rights of
employees as developed by the Secretary under subsection
(a).''.
(e) Annual Report.--The Worker Adjustment and Retraining
Notification Act (29 U.S.C. 2101 et seq.), as amended by
subsection (d), is further amended by adding at the end the
following:

``SEC. 12. CONTENTS OF ANNUAL REPORTS BY THE SECRETARY OF
LABOR.

``(a) In General.--The Secretary of Labor shall collect and
compile statistics based on the information submitted to the
Secretary under subsections (a)(3) and (e) of section 3.
``(b) Report.--Not later than 120 days after the date on
which each regular session of Congress commences, the
Secretary of Labor shall prepare and submit to the President
and the appropriate committees of Congress a report on the
offshoring of jobs (as defined in section 2(a)(9)). Each such
report shall include information concerning--
``(1) the number of jobs affected by offshoring;
``(2) the locations to which jobs are being shifted or
transferred;
``(3) the reasons why such shifts and transfers are
occurring; and
``(4) any other relevant data compiled under subsection
(a).''.
______

SA 3111. Mr. GREGG proposed an amendment to the bill S. 1637, to
amend the Internal Revenue Code of 1986 to comply with the World Trade
Organization rulings on the FSC/ETI benefit in a manner that preserves
jobs and production activities in the United States, to reform and
simplify the international taxation rules of the United States, and for
other purposes; as follows:

At the appropriate place, insert the following:

SEC. __. PROTECTION OF OVERTIME PAY.

Section 13 of the Fair Labor Standards Act of 1938 (29
U.S.C. 213) is amended by adding at the end the following:
``(k)(1) The Secretary shall not promulgate any rule under
subsection (a)(1) that exempts from the overtime pay
provisions of section 7 any employee who earns less than
$23,660 per year.
``(2) The Secretary shall not promulgate any rule under
subsection (a)(1) concerning the right to overtime pay that
is not as protective, or more protective, of the overtime pay
rights of employees in the occupations or job classifications
described in paragraph (3) as the protections provided for
such employees under the regulations in effect under such
subsection on March 31, 2003.
``(3) The occupations or job classifications described in
this paragraph are as follows:
``(A) Any worker paid on an hourly basis.
``(B) Blue collar workers.
``(C) Any worker provided overtime under a collective
bargaining agreement.
``(D) Team leaders.
``(E) Computer programmers.
``(F) Registered nurses.
``(G) Licensed practical nurses.
``(H) Nurse midwives.
``(I) Nursery school teachers.
``(J) Oil and gas pipeline workers.
``(K) Oil and gas field workers.
``(L) Oil and gas platform workers.
``(M) Refinery workers.
``(N) Steel workers.
``(O) Shipyard and ship scrapping workers.
``(P) Teachers.
``(Q) Technicians.
``(R) Journalists.
``(S) Chefs.
``(T) Cooks.
``(U) Police officers.
``(V) Firefighters.
``(W) Fire sergeants.
``(X) Police sergeants.
``(Y) Emergency medical technicians.
``(Z) Paramedics.
``(AA) Waste disposal workers.
``(BB) Day care workers.
``(CC) Maintenance employees.
``(DD) Production line employees.
``(EE) Construction employees.
``(FF) Carpenters.
``(GG) Mechanics.
``(HH) Plumbers.
``(II) Iron workers.
``(JJ) Craftsmen.
``(KK) Operating engineers.
``(LL) Laborers.
``(MM) Painters.
``(NN) Cement masons.
``(OO) Stone and brick masons.
``(PP) Sheet metal workers.
``(QQ) Utility workers.
``(RR) Longshoremen.
``(SS) Stationary engineers.
``(TT) Welders.
``(UU) Boilermakers.
``(VV) Funeral directors.
``(WW) Athletic trainers.
``(XX) Outside sales employees.
``(YY) Inside sales employees.
``(ZZ) Grocery store managers.
``(AAA) Financial services industry workers.
``(BBB) Route drivers.
``(CCC) Assistant retail managers.
``(4) Any portion of a rule promulgated under subsection
(a)(1) after March 31, 2003, that modifies the overtime pay
provisions of section 7 in a manner that is inconsistent with
paragraphs (2) and (3) shall have no force or effect as it
relates to the occupation or job classification involved.''.
______

SA 3112. Mr. GRAHAM of Florida (for himself and Mr. Dayton) proposed
an amendment to the bill S. 1637, to amend the Internal Revenue Code of
1986 to comply with the World Trade Organization rulings on the FSC/ETI
benefit in a manner that preserves jobs and production activities in
the United States, to reform and simplify the international taxation
rules of the United States, and for other purposes; as follows:

Strike section 102 and title II and insert the following:

SEC. 102. MANUFACTURING JOBS CREDIT.

(a) In General.--Subpart D of part IV of subchapter A of
chapter 1 (relating to business-related credits), as amended
by this Act, is amended by adding at the end the following:

``SEC. 45S. MANUFACTURING JOBS CREDIT.

``(a) General Rule.--For purposes of section 38, in the
case of an eligible taxpayer, the manufacturing jobs credit
determined under this section is an amount equal to 1.66
percent of the W-2 wages paid by the taxpayer during the
taxable year attributable to the taxpayer's domestic
production gross receipts for such taxable year.
``(b) Eligible Taxpayer.--For purposes of this section, the
term `eligible taxpayer' means any taxpayer which has
domestic production gross receipts for the taxable year and
the preceding taxable year.
``(c) W-2 Wages.--For purposes of this section--
``(1) W-2 wages.--The term `W-2 wages' means the sum of the
aggregate amounts the taxpayer is required to include on
statements under paragraphs (3) and (8) of section 6051(a)
with respect to employment of employees of the taxpayer
during the taxpayer's taxable year.
``(2) Limitation.--The aggregate amount of W-2 wages taken
into account with respect to any employee for any taxable
year shall not exceed $35,000.
``(3) Special rules.--
``(A) Pass-thru entities.--In the case of an S corporation,
partnership, estate or trust, or other pass-thru entity, the
determination of W-2 wages shall be made at the entity level.
``(B) Acquisitions and dispositions.--The Secretary shall
provide for the determination of W-2 wages in cases where the
taxpayer acquires, or disposes of, the major portion of a
trade or business or the major portion of a separate unit of
a trade or business during the taxable year.
``(C) Coordination with targeted jobs credit, etc.--Such
term shall not include wages attributable to service taken
into account in determining the credit under section 45A, 51,
or 1396.
``(d) Domestic Production Gross Receipts.--For purposes of
this section, the term `domestic production gross receipts'
means the gross receipts of the taxpayer which are derived
from--
``(1) any sale, exchange, or other disposition of, or
``(2) any lease, rental, or license of,

that portion of qualifying production property which was
manufactured, produced, grown, or extracted by the taxpayer
within the United States.
``(e) Qualifying Production Property.--For purposes of this
section--
``(1) In general.--Except as otherwise provided in this
paragraph, the term `qualifying production property' means--
``(A) any tangible personal property,
``(B) any computer software, and
``(C) any property described in section 168(f) (3) or (4),
including any underlying copyright or trademark.
``(2) Exclusions from qualifying production property.--The
term `qualifying production property' shall not include--
``(A) consumable property that is sold, leased, or licensed
by the taxpayer as an integral part of the provision of
services,
``(B) oil or gas,

[[Page S4848]]

``(C) electricity,
``(D) water supplied by pipeline to the consumer,
``(E) utility services, or
``(F) any film, tape, recording, book, magazine, newspaper,
or similar property the market for which is primarily topical
or otherwise essentially transitory in nature.
``(f) United States.--For purposes of subsection (e), the
term `United States' includes the Commonwealth of Puerto
Rico, Guam, American Samoa, the Commonwealth of the Northern
Mariana Islands, and the Virgin Islands of the United States.
``(g) Certain Rules Made Applicable.--For purposes of this
section, rules similar to the rules of section 52 shall
apply.''.
(b) Credit To Be Part of General Business Credit.--Section
38(b) (relating to current year business credit), as amended
by this Act, is amended by striking ``plus'' at the end of
paragraph (29), by striking the period at the end of
paragraph (30) and inserting ``, plus'', and by adding at the
end the following:
``(31) the manufacturing jobs credit determined under
section 45S.''.
(c) Denial of Deduction for Portion of Wages Equal to
Manufacturing Jobs Credit.--
(1) Subsection (a) of section 280C (relating to rule for
targeted jobs credit) is amended by inserting ``45S(a),''
after ``45A(a),''.
(2) Subsection (c) of section 196 (relating to deduction
for certain unused business credits), as amended by this Act,
is amended by striking ``and'' at the end of paragraph (12),
by striking the period at the end of paragraph (13) and
inserting ``, and'', and by adding at the end the following
new paragraph:
``(14) the manufacturing jobs credit determined under
section 45S(a).''.
(d) Denial of Carrybacks to Preenactment Years.--Subsection
(d) of section 39, as amended by this Act, is amended by
adding at the end thereof the following new paragraph:
``(16) No carryback of section 45s credit before
enactment.--No portion of the unused business credit for any
taxable year which is attributable to the manufacturing jobs
credit determined under section 45S may be carried to a
taxable year ending on or before the date of the enactment of
section 45S.''.
(e) Clerical Amendment.--The table of sections for subpart
D of part IV of subchapter A of chapter 1, as amended by this
Act, is amended by adding at the end the following:

``Sec. 45S. Manufacturing jobs credit.''.

(f) Effective Date.--The amendments made by this section
shall apply to taxable years ending after the date of the
enactment of this Act.

TITLE II--INTERNATIONAL TAX PROVISIONS

SEC. 201. DETERMINATION OF FOREIGN PERSONAL HOLDING COMPANY
INCOME WITH RESPECT TO TRANSACTIONS IN
COMMODITIES.

(a) In General.--Clauses (i) and (ii) of section
954(c)(1)(C) (relating to commodity transactions) are amended
to read as follows:
``(i) arise out of commodity hedging transactions (as
defined in paragraph (4)(A)),
``(ii) are active business gains or losses from the sale of
commodities, but only if substantially all of the controlled
foreign corporation's commodities are property described in
paragraph (1), (2), or (8) of section 1221(a), or''.
(b) Definition and Special Rules.--Subsection (c) of
section 954 is amended by adding after paragraph (3) the
following new paragraph:
``(4) Definition and special rules relating to commodity
transactions.--
``(A) Commodity hedging transactions.--For purposes of
paragraph (1)(C)(i), the term `commodity hedging transaction'
means any transaction with respect to a commodity if such
transaction--
``(i) is a hedging transaction as defined in section
1221(b)(2), determined--

``(I) without regard to subparagraph (A)(ii) thereof,
``(II) by applying subparagraph (A)(i) thereof by
substituting `ordinary property or property described in
section 1231(b)' for `ordinary property', and
``(III) by substituting `controlled foreign corporation'
for `taxpayer' each place it appears, and

``(ii) is clearly identified as such in accordance with
section 1221(a)(7).
``(B) Treatment of dealer activities under paragraph
(1)(C).--Commodities with respect to which gains and losses
are not taken into account under paragraph (2)(C) in
computing a controlled foreign corporation's foreign personal
holding company income shall not be taken into account in
applying the substantially all test under paragraph
(1)(C)(ii) to such corporation.
``(C) Regulations.--The Secretary shall prescribe such
regulations as are appropriate to carry out the purposes of
paragraph (1)(C) in the case of transactions involving
related parties.''.
(c) Modification of Exception for Dealers.--Clause (i) of
section 954(c)(2)(C) is amended by inserting ``and
transactions involving physical settlement'' after
``(including hedging transactions''.
(d) Effective Date.--The amendments made by this section
shall apply to transactions entered into after December 31,
2004.
______

SA 3113. Mr. ALLEN (for himself, Mrs. Dole, Mr. Edwards, and Mr.
Graham of South Carolina) submitted an amendment intended to be
proposed by him to the bill S. 1637, to amend the Internal Revenue Code
of 1986 to comply with the World Trade Organization rulings on the FSC/
ETI benefit in a manner that preserves jobs and production activities
in the United States, to reform and simplify the international taxation
rules of the United States, and for other purposes; as follows:

At the end add the following:

TITLE IX--HOMESTEAD PRESERVATION ACT

SEC. 901. SHORT TITLE.

This title may be cited as the ``Homestead Preservation
Act''.

SEC. 902. MORTGAGE PAYMENT ASSISTANCE.

(a) Establishment of Program.--The Secretary of Housing and
Urban Development (referred to in this section as the
``Secretary'') shall establish a program under which the
Secretary shall award low-interest loans to eligible
individuals to enable such individuals to continue to make
mortgage payments with respect to the primary residences of
such individuals.
(b) Eligibility.--To be eligible to receive a loan under
the program established under subsection (a), an individual
shall be--
(1) an individual that is a worker adversely affected by
international economic activity, as determined by the
Secretary;
(2) a borrower under a loan which requires the individual
to make monthly mortgage payments with respect to the primary
place of residence of the individual; and
(3) enrolled in a training or assistance program.
(c) Loan Requirements.--
(1) In general.--A loan provided to an eligible individual
under this section shall--
(A) be for a period of not to exceed 12 months;
(B) be for an amount that does not exceed the sum of--
(i) the amount of the monthly mortgage payment owed by the
individual; and
(ii) the number of months for which the loan is provided;
(C) have an applicable rate of interest that equals 4
percent;
(D) require repayment as provided for in subsection (d);
and
(E) be subject to such other terms and conditions as the
Secretary determines appropriate.
(2) Account.--A loan awarded to an individual under this
section shall be deposited into an account from which a
monthly mortgage payment will be made in accordance with the
terms and conditions of such loan.
(d) Repayment.--
(1) In general.--An individual to which a loan has been
awarded under this section shall be required to begin making
repayments on the loan on the earlier of--
(A) the date on which the individual has been employed on a
full-time basis for 6 consecutive months; or
(B) the date that is 1 year after the date on which the
loan has been approved under this section.
(2) Repayment period and amount.--
(A) Repayment period.--A loan awarded under this section
shall be repaid on a monthly basis over the 5-year period
beginning on the date determined under paragraph (1).
(B) Amount.--The amount of the monthly payment described in
subparagraph (A) shall be determined by dividing the total
amount provided under the loan (plus interest) by 60.
(C) Rule of construction.--Nothing in this paragraph shall
be construed to prohibit an individual from--
(i) paying off a loan awarded under this section in less
than 5 years; or
(ii) from paying a monthly amount under such loan in excess
of the monthly amount determined under subparagraph (B) with
respect to the loan.
(e) Regulations.--Not later than 6 weeks after the date of
enactment of this section, the Secretary shall promulgate
regulations necessary to carry out this section, including
regulations that permit an individual to certify that the
individual is an eligible individual under subsection (b).
(f) Authorization of Appropriations.--There is authorized
to be appropriated to carry out this section, $10,000,000 for
each of fiscal years 2005 through 2009.
______

SA 3114. Ms. CANTWELL (for herself and Mr. Voinovich) proposed an
amendment to the bill S. 1637, to amend the Internal Revenue Code of
1986 to comply with the World Trade Organization rulings on the FSC/ETI
benefit in a manner that preserves jobs and production activities in
the United States, to reform and simplify the international taxation
rules of the United States, and for other purposes; as follows:

At the end, add the following:

TITLE __--UNEMPLOYMENT COMPENSATION

SEC. __01. EXTENSION OF THE TEMPORARY EXTENDED UNEMPLOYMENT
COMPENSATION ACT OF 2002.

(a) In General.--Section 208 of the Temporary Extended
Unemployment Compensation Act of 2002 (Public Law 107-147;
116 Stat. 30), as amended by Public Law 108-1 (117 Stat. 3)
and the Unemployment Compensation Amendments of 2003 (Public
Law 108-26; 117 Stat. 751), is amended--

[[Page S4849]]

(1) in subsection (a)(2), by striking ``December 31, 2003''
and inserting ``November 30, 2004'';
(2) in subsection (b)(1), by striking ``December 31, 2003''
and inserting ``November 30, 2004'';
(3) in subsection (b)(2)--
(A) in the heading, by striking ``december 31, 2003'' and
inserting ``november 30, 2004''; and
(B) by striking ``December 31, 2003'' and inserting
``November 30, 2004''; and
(4) in subsection (b)(3), by striking ``March 31, 2004''
and inserting ``February 28, 2005''.
(b) Effective Date.--The amendments made by this section
shall take effect as if included in the enactment of the
Temporary Extended Unemployment Compensation Act of 2002
(Public Law 107-147; 116 Stat. 21).

SEC. __02. ADDITIONAL REVISION TO CURRENT TEUC-X TRIGGER.

(a) In General.--Section 203(c)(2)(B) of the Temporary
Extended Unemployment Compensation Act of 2002 (Public Law
107-147; 116 Stat. 30) is amended to read as follows:
``(B) such a period would then be in effect for such State
under such Act if--
``(i) section 203(d) of such Act were applied as if it had
been amended by striking `5' each place it appears and
inserting `4'; and
``(ii) with respect to weeks of unemployment beginning
after December 27, 2003--

``(I) paragraph (1)(A) of such section 203(d) did not
apply; and
``(II) clause (ii) of section 203(f)(1)(A) of such Act did
not apply.''.

(b) Application.--Section 203(c)(2)(B)(ii) of the Temporary
Extended Unemployment Compensation Act of 2002 (Public Law
107-147; 116 Stat. 30), as added by subsection (a), shall
apply with respect to payments for weeks of unemployment
beginning on or after the date of enactment this Act.

SEC. __03. TEMPORARY STATE AUTHORITY TO WAIVE APPLICATION OF
LOOKBACKS UNDER THE FEDERAL-STATE EXTENDED
UNEMPLOYMENT COMPENSATION ACT OF 1970.

For purposes of conforming with the provisions of the
Federal-State Extended Unemployment Compensation Act of 1970
(26 U.S.C. 3304 note), a State may, during the period
beginning on the date of enactment of this Act and ending on
June 30, 2004, waive the application of either subsection
(d)(1)(A) of section 203 of such Act or subsection
(f)(1)(A)(ii) of such section, or both.
______

SA 3115. Mr. LAUTENBERG (for himself, Mrs. Feinstein, Mr. Feingold,
and Mrs. Clinton) submitted an amendment intended to be proposed by him
to the bill S. 1637, to amend the Internal Revenue Code of 1986 to
comply with the World Trade Organization rulings on the FSC/ETI benefit
in a manner that preserves jobs and production activities in the United
States, to reform and simplify the international taxation rules of the
United States, and for other purposes; which was ordered to lie on the
table; as follows:

At the end, add the following:

TITLE IX--NON-REVENUE PROVISIONS

SEC. 901. CLARIFICATION OF CERTAIN SANCTIONS.

(a) In General.--
(1) Clarification of certain actions under IEEPA.--In any
case in which the President takes action under the
International Emergency Economic Powers Act (50 U.S.C. 1701
et seq.) with respect to a foreign country, or persons
dealing with or associated with that foreign government, as a
result of a determination by the Secretary of State that the
government has repeatedly provided support for acts of
international terrorism, such action shall apply to a United
States person or other person as defined in paragraph (2).
(2) Definitions.--In this section:
(A) Person.--The term ``person'' means an individual,
partnership, corporation, or other form of association,
including any government or agency thereof.
(B) United States person.--The term ``United States
person'' means--
(i) any resident or national (other than an individual
resident outside the United States and employed by other than
a United States person); and
(ii) any domestic concern (including any permanent domestic
establishment of any foreign concern) or any foreign
subsidiary or affiliate (including any permanent foreign
establishment) of any domestic concern, which is controlled
in fact by such domestic concern.
(C) Controlled.--The term ``is controlled'' means--
(i) in the case of a corporation, holds at least 50 percent
(by vote or value) of the capital structure of the
corporation; and
(ii) in the case of any other kind of legal entity, holds
interests representing at least 50 percent of the capital
structure of the entity.
(b) Applicability.--
(1) In general.--In any case in which the President has
taken action under the International Emergency Economic
Powers Act and such action is in effect on the date of
enactment of this Act, the provisions of subsection (a) shall
not apply to a United States person (or other person) if such
person divests or terminates its business with the government
or person identified by such action within 90 days after the
date of enactment of this Act.
(2) Actions after date of enactment.--In any case in which
the President takes action under the International Emergency
Economic Powers Act on or after the date of enactment of this
Act, the provisions of subsection (a) shall not apply to a
United States person (or other person) if such person divests
or terminates its business with the government or person
identified by such action within 90 days after the date of
such action.

SEC. 902. NOTIFICATION OF CONGRESS OF TERMINATION OF
INVESTIGATION BY OFFICE OF FOREIGN ASSETS
CONTROL.

(a) Notification Requirement.--The Office of Federal
Procurement Policy Act (41 U.S.C. 403 et seq.) is amended by
adding at the end the following new section:

``SEC. 42. NOTIFICATION OF CONGRESS OF TERMINATION OF
INVESTIGATION BY OFFICE OF FOREIGN ASSETS
CONTROL.

``The Director of the Office of Foreign Assets Control
shall notify Congress upon the termination of any
investigation by the Office of Foreign Assets Control of the
Department of the Treasury if any sanction is imposed by the
Director of such office as a result of the investigation.''.
(b) Clerical Amendment.--The table of sections in section
1(b) of such Act is amended by adding at the end the
following new item:

``Sec. 42. Notification of Congress of termination of investigation by
Office of Foreign Assets Control.''.
______

SA 3116. Mr. DASCHLE submitted an amendment intended to be proposed
by him to the bill S. 1637, to amend the Internal Revenue Code of 1986
to comply with the World Trade Organization rulings on the FSC/ETI
benefit in a manner that preserves jobs and production activities in
the United States, to reform and simplify the international taxation
rules of the United States, and for other purposes; which was ordered
to lie on the table; as follows:

At the appropriate place, insert the following:

SEC. __. MODIFICATION OF EXEMPTION FROM SELF-EMPLOYMENT TAX
FOR CERTAIN TERMINATION PAYMENTS RECEIVED BY
FORMER INSURANCE SALESMEN.

(a) Internal Revenue Code.--Paragraph (4) of section
1402(k) of the Internal Revenue Code of 1986 (relating to
codification of treatment of certain termination payments
received by former insurance salesmen) is amended to read as
follows:
``(4) the amount of such payment depends primarily on
policies sold by or credited to the account of such
individual or the extent to which such policies remain in
force for some period after such termination, or both.''.
(b) Social Security Act.--Paragraph (4) of section 211(j)
of the Social Security Act is amended to read as follows:
``(4) the amount of such payment depends primarily on
policies sold by or credited to the account of such
individual or the extent to which such policies remain in
force for some period after such termination, or both.''.
(c) Effective Date.--The amendments made by this section
shall apply to payments after the date of the enactment of
this Act.

____________________