An amendment numbered 15 printed in Part B of House Report 109-175 to declare that it is U.S. policy to use the voice, vote, and influence of the U.S. to oppose the creation of any internationalor global taxation by the UN or its affiliated agencie s. Declares that no U.S. person shall be subject to an international tax if it is levied.
What it does: 2 changes: renumbers, adds a section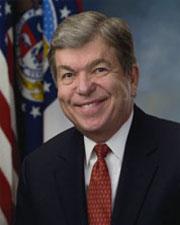 Rep. Roy Blunt (R-MO)
Description
Amendment adds language which opposes the creation of any international or global tax by the UN or its affiliated agencies.
What it changes
2 changes to H.R. 2601
We couldn't match these changes to the text of H.R. 2601, so they're shown as written.
Change 1: Renumbers sections (1111) through (1126) as (1121) through (1136)
RenumbersSubtitle B of title XIOriginal wording
In subtitle B of title XI, redesignate sections 1111 through 1126 as sections 1121 through 1136, respectively.
Change 2: Adds SEC. 1111. STATEMENT OF POLICY RELATING TO INTERNATIONAL TAXATION at the end of subtitle A of title XI
Adds a sectionInserted: SEC. 1111. STATEMENT OF POLICY RELATING TO INTERNATIONAL TAXATION.
Inserted: (a) Policy.--It is the policy of the United States to use the voice, vote, and influence of the United States to vigorously oppose any international or global tax that is or may be considered or promoted by the United Nations, its specialized or affiliated agencies, its Member States, or United Nations-recognized nongovernmental organizations.
Inserted: (b) Efforts.--United States representatives at the United Nations shall--
Inserted: (1) use the voice, vote, and influence of the United States to vigorously oppose any effort by the United Nations or any of its specialized or affiliated agencies to fund, approve, advocate, or promote any proposal concerning the imposition of a tax or fee on any United States person in order to raise revenue for the United Nations or any such agency; and
Inserted: (2) declare that a United States person shall not be subject to any international tax and shall not be required to pay such tax if such tax is levied against such person.
Inserted: (c) Exception.--The policy described in subsection (a) shall not apply to fees for publications or other kinds of fees that are not tantamount to a tax on a United States person.
Inserted: (d) Person Defined.--For purposes of this section, the term "person" has the meaning given such term in section 7701(a)(1) of the Internal Revenue Code of 1986 (26 U.S.C. 7701(a)(1)).
Original wording
At the end of subtitle A of title XI, add the following new section:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
In subtitle B of title XI, redesignate sections 1111 through 1126 as sections 1121 through 1136, respectively.
At the end of subtitle A of title XI, add the following new section:
SEC. 1111. STATEMENT OF POLICY RELATING TO INTERNATIONAL TAXATION.
(a) Policy.--It is the policy of the United States to use the voice, vote, and influence of the United States to vigorously oppose any international or global tax that is or may be considered or promoted by the United Nations, its specialized or affiliated agencies, its Member States, or United Nations-recognized nongovernmental organizations.
(b) Efforts.--United States representatives at the United Nations shall--
(1) use the voice, vote, and influence of the United States to vigorously oppose any effort by the United Nations or any of its specialized or affiliated agencies to fund, approve, advocate, or promote any proposal concerning the imposition of a tax or fee on any United States person in order to raise revenue for the United Nations or any such agency; and
(2) declare that a United States person shall not be subject to any international tax and shall not be required to pay such tax if such tax is levied against such person.
(c) Exception.--The policy described in subsection (a) shall not apply to fees for publications or other kinds of fees that are not tantamount to a tax on a United States person.
(d) Person Defined.--For purposes of this section, the term “person” has the meaning given such term in section 7701(a)(1) of the Internal Revenue Code of 1986 (26 U.S.C. 7701(a)(1)).
Legislative Activity
Stay on top of the latest movement without scrolling through every action
House amendment offered
July 19, 2005
View full timeline
House amendment offered
July 19, 2005
House amendment agreed to: On agreeing to the Blunt amendment (A014) Agreed to by voice vote.
July 19, 2005 • 4:21 PM
Amendment agreed to Committee of the Whole
July 19, 2005 • 4:21 PM
House amendment offered/reported by : Amendment (A014) offered by Mr. Blunt.(consideration: CR H6056-6057; text: CR H6056)
July 19, 2005 • 4:13 PM
Amendment (A014) offered by Mr. Blunt. (consideration: CR H6056-6057; text: CR H6056)
July 19, 2005 • 4:13 PM
On agreeing to the Blunt amendment (A014) Agreed to by voice vote.
July 19, 2005 • 4:21 PM