S.Amdt. 2621
What it does: Adds SEC. __. CLARIFICATION OF CASH ACCOUNTING RULES FOR SMALL BUSINESS at the end of title IV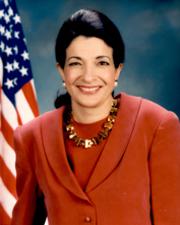 Sen. Olympia J. Snowe (R-ME)
What it changes
1 change to S. 2020 · shown in the bill's text
Adds SEC. __. CLARIFICATION OF CASH ACCOUNTING RULES FOR SMALL BUSINESS at the end of title IV
Adds a sectionIn S. 2020 · Placed on Calendar Senate
(d) Effective Date.--The amendments made by this section shall apply to amounts paid or accrued during the period beginning after December 31, 2006, and before January 1, 2008, and properly allocable to such period, with respect to mortgage insurance contracts issued after December 31, 2006.
Inserted: SEC. __. CLARIFICATION OF CASH ACCOUNTING RULES FOR SMALL BUSINESS.
Inserted: (a) Cash Accounting Permitted.--
Inserted: (1) In general.--Section 446 (relating to general rule for methods of accounting) is amended by adding at the end the following new subsection:
Inserted: "(g) Certain Small Business Taxpayers Permitted to Use Cash Accounting Method Without Limitation.--
Inserted: "(1) In general.--An eligible taxpayer shall not be required to use an accrual method of accounting for any taxable year.
Inserted: "(2) Eligible taxpayer.--For purposes of this subsection, a taxpayer is an eligible taxpayer with respect to any taxable year if--
Inserted: "(A) for all prior taxable years beginning after December 31, 2004, the taxpayer (or any predecessor) met the gross receipts test of section 448(c), and
Inserted: "(B) the taxpayer is not subject to section 447 or 448.".
Inserted: (2) Expansion of gross receipts test.--
Inserted: (A) In general.--Paragraph (3) of section 448(b) (relating to entities with gross receipts of not more than $5,000,000) is amended by striking "$5,000,000" in the text and in the heading and inserting "$10,000,000".
Inserted: (B) Conforming amendments.--Section 448(c) is amended--
Inserted: (i) by striking "$5,000,000" each place it appears in the text and in the heading of paragraph (1) and inserting "$10,000,000", and
Show 29 more inserted paragraphsShow less
Inserted: (ii) by adding at the end the following new paragraph:
Inserted: "(4) Inflation adjustment.--In the case of any taxable year beginning in a calendar year after 2005, the dollar amount contained in subsection (b)(3) and paragraph (1) of this subsection shall be increased by an amount equal to--
Inserted: "(A) such dollar amount, multiplied by
Inserted: "(B) the cost-of-living adjustment determined under section 1(f)(3) for the calendar year in which the taxable year begins, by substituting 'calendar year 2004' for 'calendar year 1992' in subparagraph (B) thereof. If any amount as adjusted under this subparagraph is not a multiple of $100,000, such amount shall be rounded to the nearest multiple of $100,000.".
Inserted: (b) Clarification of Inventory Rules for Small Business.--
Inserted: (1) In general.--Section 471 (relating to general rule for inventories) is amended by redesignating subsection (c) as subsection (d) and by inserting after subsection (b) the following new subsection:
Inserted: "(c) Small Business Taxpayers Not Required to Use Inventories.--
Inserted: "(1) In general.--A qualified taxpayer shall not be required to use inventories under this section for a taxable year.
Inserted: "(2) Treatment of taxpayers not using inventories.--If a qualified taxpayer does not use inventories with respect to any property for any taxable year beginning after December 31, 2004, such property shall be treated as a material or supply which is not incidental.
Inserted: "(3) Qualified taxpayer.--For purposes of this subsection, the term 'qualified taxpayer' means--
Inserted: "(A) any eligible taxpayer (as defined in section 446(g)(2)), and
Inserted: "(B) any taxpayer described in section 448(b)(3).".
Inserted: (2) Conforming amendments.--
Inserted: (A) Subpart D of part II of subchapter E of chapter 1 is amended by striking section 474.
Inserted: (B) The table of sections for subpart D of part II of subchapter E of chapter 1 is amended by striking the item relating to section 474.
Inserted: (c) Effective Date and Special Rules.--
Inserted: (1) In general.--The amendments made by this section shall apply to taxable years beginning after December 31, 2004.
Inserted: (2) Change in method of accounting.--In the case of any taxpayer changing the taxpayer's method of accounting for any taxable year under the amendments made by this section--
Inserted: (A) such change shall be treated as initiated by the taxpayer;
Inserted: (B) such change shall be treated as made with the consent of the Secretary of the Treasury; and
Inserted: (C) the net amount of the adjustments required to be taken into account by the taxpayer under section 481 of the Internal Revenue Code of 1986 shall be taken into account over a period (not greater than 4 taxable years) beginning with such taxable year.
Inserted: SEC. __. INCLUSION OF HEAVY VEHICLES IN LIMITATION ON DEPRECIATION OF CERTAIN LUXURY AUTOMOBILES.
Inserted: (a) In General.--Section 280F(d)(5)(A) (defining passenger automobile) is amended--
Inserted: (1) by striking clause (ii) and inserting the following new clause:
Inserted: "(ii)(I) which is rated at 6,000 pounds unloaded gross vehicle weight or less, or
Inserted: "(II) which is rated at more than 6,000 pounds but not more than 14,000 pounds gross vehicle weight.",
Inserted: (2) by striking "clause (ii)" in the second sentence and inserting "clause (ii)(I)".
Inserted: (b) Conforming Amendment.--Section 179(b) (relating to limitations) is amended by striking paragraph (6).
Inserted: (c) Effective Date.--The amendments made by this section shall apply to property placed in service after the date of the enactment of this Act.
Original wording
At the end of title IV, add the following:
Read automatically from the Congressional Record. Check the original before relying on it.
As printed
SA 2621. Ms. SNOWE submitted an amendment intended to be proposed by her to the bill S. 2020, to provide for reconciliation pursuant to section 202(b) of the concurrent resolution on the budget for fiscal year 2006; which was ordered to lie on the table; as follows:
At the end of title IV, add the following:
SEC. __. CLARIFICATION OF CASH ACCOUNTING RULES FOR SMALL BUSINESS.
(a) Cash Accounting Permitted.--
(1) In general.--Section 446 (relating to general rule for methods of accounting) is amended by adding at the end the following new subsection:
“(g) Certain Small Business Taxpayers Permitted to Use Cash Accounting Method Without Limitation.--
“(1) In general.--An eligible taxpayer shall not be required to use an accrual method of accounting for any taxable year.
“(2) Eligible taxpayer.--For purposes of this subsection, a taxpayer is an eligible taxpayer with respect to any taxable year if--
“(A) for all prior taxable years beginning after December 31, 2004, the taxpayer (or any predecessor) met the gross receipts test of section 448(c), and
“(B) the taxpayer is not subject to section 447 or 448.”.
(2) Expansion of gross receipts test.--
(A) In general.--Paragraph (3) of section 448(b) (relating to entities with gross receipts of not more than $5,000,000) is amended by striking “$5,000,000” in the text and in the heading and inserting “$10,000,000”.
(B) Conforming amendments.--Section 448(c) is amended--
(i) by striking “$5,000,000” each place it appears in the text and in the heading of paragraph (1) and inserting “$10,000,000”, and
(ii) by adding at the end the following new paragraph:
“(4) Inflation adjustment.--In the case of any taxable year beginning in a calendar year after 2005, the dollar amount contained in subsection (b)(3) and paragraph (1) of this subsection shall be increased by an amount equal to--
“(A) such dollar amount, multiplied by
“(B) the cost-of-living adjustment determined under section 1(f)(3) for the calendar year in which the taxable year begins, by substituting ‘calendar year 2004' for ‘calendar year 1992' in subparagraph (B) thereof. If any amount as adjusted under this subparagraph is not a multiple of $100,000, such amount shall be rounded to the nearest multiple of $100,000.”.
(b) Clarification of Inventory Rules for Small Business.--
(1) In general.--Section 471 (relating to general rule for inventories) is amended by redesignating subsection (c) as subsection (d) and by inserting after subsection (b) the following new subsection:
“(c) Small Business Taxpayers Not Required to Use Inventories.--
“(1) In general.--A qualified taxpayer shall not be required to use inventories under this section for a taxable year.
“(2) Treatment of taxpayers not using inventories.--If a qualified taxpayer does not use inventories with respect to any property for any taxable year beginning after December 31, 2004, such property shall be treated as a material or supply which is not incidental.
“(3) Qualified taxpayer.--For purposes of this subsection, the term ‘qualified taxpayer' means--
“(A) any eligible taxpayer (as defined in section 446(g)(2)), and
“(B) any taxpayer described in section 448(b)(3).”.
(2) Conforming amendments.--
(A) Subpart D of part II of subchapter E of chapter 1 is amended by striking section 474.
(B) The table of sections for subpart D of part II of subchapter E of chapter 1 is amended by striking the item relating to section 474.
(c) Effective Date and Special Rules.--
(1) In general.--The amendments made by this section shall apply to taxable years beginning after December 31, 2004.
(2) Change in method of accounting.--In the case of any taxpayer changing the taxpayer's method of accounting for any taxable year under the amendments made by this section--
(A) such change shall be treated as initiated by the taxpayer;
(B) such change shall be treated as made with the consent of the Secretary of the Treasury; and
(C) the net amount of the adjustments required to be taken into account by the taxpayer under section 481 of the Internal Revenue Code of 1986 shall be taken into account over a period (not greater than 4 taxable years) beginning with such taxable year.
SEC. __. INCLUSION OF HEAVY VEHICLES IN LIMITATION ON DEPRECIATION OF CERTAIN LUXURY AUTOMOBILES.
(a) In General.--Section 280F(d)(5)(A) (defining passenger automobile) is amended--
(1) by striking clause (ii) and inserting the following new clause:
“(ii)(I) which is rated at 6,000 pounds unloaded gross vehicle weight or less, or
“(II) which is rated at more than 6,000 pounds but not more than 14,000 pounds gross vehicle weight.”,
(2) by striking “clause (ii)” in the second sentence and inserting “clause (ii)(I)”.
(b) Conforming Amendment.--Section 179(b) (relating to limitations) is amended by striking paragraph (6).
(c) Effective Date.--The amendments made by this section shall apply to property placed in service after the date of the enactment of this Act.
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
November 17, 2005