To provide tax incentives for the purchase of advanced mine safety equipment and the training of mine rescue teams, and for other purposes.
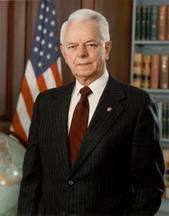 Sen. Robert C. Byrd (D-WV)
Legislative Activity
Stay on top of the latest movement without scrolling through every action
Senate amendment submitted
February 2, 2006
View full timeline
Senate amendment submitted
February 2, 2006
Senate amendment proposed (on the floor): Amendment SA 2728 proposed by Senator Baucus for Senator Byrd to Amendment SA 2707.(consideration: CR S488-489; text: CR S488-489)
February 2, 2006
Senate amendment agreed to: Amendment SA 2728 agreed to in Senate by Voice Vote.
February 2, 2006
Amendment SA 2728 proposed by Senator Baucus for Senator Byrd to Amendment SA 2707. (consideration: CR S488-489; text: CR S488-489) To provide tax incentives for the purchase of advanced mine safety equipment and the training of mine rescue teams, and for other purposes.
February 2, 2006
Amendment SA 2728 agreed to in Senate by Voice Vote.
February 2, 2006
Text
Submitted
SA 2728. Mr. BAUCUS (for Mr. Byrd (for himself, Mr. Rockefeller, Mr.
Santorum, Mr. Kerry, Mr. Durbin, Mr. Obama, Mr. McConnell, and Mr.
Bunning)) proposed an amendment to amendment SA 2707 proposed by Mr.
Frist (for Mr. Grassley (for himself and Mr. Baucus)) to the bill H.R.
4297, to provide for reconciliation pursuant to section 201(b) of the
concurrent resolution on the budget for fiscal year 2006; as follows:

At the appropriate place insert the following:

SEC. __. PARTIAL EXPENSING FOR ADVANCED MINE SAFETY
EQUIPMENT.

(a) In General.--Part VI of subchapter B of chapter 1 is
amended by inserting after section 179D the following new
section:

``SEC. 179E. ELECTION TO EXPENSE ADVANCED MINE SAFETY
EQUIPMENT.

``(a) Treatment as Expenses.--A taxpayer may elect to treat
50 percent of the cost of any qualified advanced mine safety
equipment property as an expense which is not chargeable to
capital account. Any cost so treated shall be allowed as a
deduction for the taxable year in which the qualified
advanced mine safety equipment property is placed in service.
``(b) Election.--
``(1) In general.--An election under this section for any
taxable year shall be made on the taxpayer's return of the
tax imposed by this chapter for the taxable year. Such
election shall specify the advanced mine safety equipment
property to which the election applies and shall be made in
such manner as the Secretary may by regulations prescribe.
``(2) Election irrevocable.--Any election made under this
section may not be revoked except with the consent of the
Secretary.
``(c) Qualified Advanced Mine Safety Equipment Property.--
For purposes of this section, the term `qualified advanced
mine safety equipment property' means any advanced mine
safety equipment property for use in any underground mine
located in the United States--
``(1) the original use of which commences with the
taxpayer, and
``(2) which is placed in service by the taxpayer after the
date of the enactment of this section.
``(d) Advanced Mine Safety Equipment Property.--For
purposes of this section, the term `advanced mine safety
equipment property' means any of the following:
``(1) Emergency communication technology or device which is
used to allow a miner to maintain constant communication with
an individual who is not in the mine.
``(2) Electronic identification and location device which
allows an individual who is not in the mine to track at all
times the movements and location of miners working in or at
the mine.
``(3) Emergency oxygen-generating, self-rescue device which
provides oxygen for at least 90 minutes.
``(4) Pre-positioned supplies of oxygen which (in
combination with self-rescue devices) can be used to provide
each miner on a shift, in the event of an accident or other
event which traps the miner in the mine or otherwise
necessitates the use of such a self-rescue device, the
ability to survive for at least 48 hours.
``(5) Comprehensive atmospheric monitoring system which
monitors the levels of carbon monoxide, methane, and oxygen
that are present in all areas of the mine and which can
detect smoke in the case of a fire in a mine.
``(e) Special Rules.--
``(1) Coordination with section 179.--No expenditures shall
be taken into account under subsection (a) with respect to
the portion of the cost of any property specified in an
election under section 179.
``(2) Basis reduction.--For purposes of this title, the
basis of any property shall be reduced by the portion of the
cost of such property taken into account under subsection
(a).
``(f) Reporting.--No deduction shall be allowed under
subsection (a) to any taxpayer for any taxable year unless
such taxpayer files with the Secretary a report containing
such information with respect to the operation of the mines
of the taxpayer as the Secretary shall require.
``(g) Termination.--This section shall not apply to
property placed in service after the date which is 3 years
after the date of the enactment of this section.''.
(b) Conforming Amendments.--
(1) Section 263(a)(1) is amended by striking ``or'' at the
end of subparagraph (J), by striking the period at the end of
subparagraph (K) and inserting ``, or'', and by inserting
after subparagraph (K) the following new subparagraph:
``(L) expenditures for which a deduction is allowed under
section 179E.''.
(2) Section 312(k)(3)(B) is amended by striking ``or 179D''
each place it appears in the heading and text thereof and
inserting ``179D, or 179E''.
(3) Section 1016(a) is amended by striking ``and'' at the
end of paragraph (36), by striking the period at the end of
paragraph (37) and inserting ``, and'', and by adding at the
end the following new paragraph:
``(38) to the extent provided in section 179E(e)(2).''.
(4) Section 1245(a)(2)(C) is amended by inserting ``179E,''
after ``179D,''.
(5) The table of sections for part VI of subchapter B of
chapter 1 is amended by inserting after the item relating to
section 179D the following new item:

``Sec. 179E. Election to expense advanced mine safety equipment.''.

(c) Effective Date.--The amendments made by this section
shall apply to costs paid or incurred after the date of the
enactment of this Act.

SEC. __. MINE RESCUE TEAM TRAINING TAX CREDIT.

(a) In General.--Subpart D of part IV of subchapter A of
chapter 1 (relating to business related credits) is amended
by adding at the end the following new section:

``SEC. 45N. MINE RESCUE TEAM TRAINING CREDIT.

``(a) Amount of Credit.--For purposes of section 38, the
mine rescue team training credit determined under this
section with respect to any eligible employer for any taxable
year is an amount equal to the lesser of--
``(1) 20 percent of the amount paid or incurred by the
taxpayer during the taxable year with respect to the training
program costs of each qualified mine rescue team employee
(including wages of such employee while attending such
program), or
``(2) $10,000.
``(b) Qualified Mine Rescue Team Employee.--For purposes of
this section, the term `qualified mine rescue team employee'
means with respect to any taxable year any full-time employee
of the taxpayer who is--
``(1) a miner eligible for more than 6 months of such
taxable year to serve as a mine rescue team member as a
result of completing, at a minimum, an initial 20-hour course
of instruction as prescribed by the Mine Safety and Health
Administration's Office of Educational Policy and
Development, or
``(2) a miner eligible for more than 6 months of such
taxable year to serve as a mine rescue team member by virtue
of receiving at least 40 hours of refresher training in such
instruction.
``(c) Eligible Employer.--For purposes of this section, the
term `eligible employer' means any taxpayer which employs
individuals as miners in underground mines in the United
States.
``(d) Wages.--For purposes of this section, the term
`wages' has the meaning given to such term by subsection (b)
of section 3306 (determined without regard to any dollar
limitation contained in such section).
``(e) Termination.--This section shall not apply to taxable
years beginning after December 31, 2008.''.
(b) Credit Made Part of General Business Credit.--Section
38(b) is amended by striking ``and'' at the end of paragraph
(25), by striking the period at the end of paragraph (26) and
inserting ``, and'', and by adding at the end the following
new paragraph:
``(27) the mine rescue team training credit determined
under section 45N(a).''.
(c) No Double Benefit.--Section 280C is amended by adding
at the end the following new subsection:
``(e) Mine Rescue Team Training Credit.--No deduction shall
be allowed for that portion of the expenses otherwise
allowable as a

[[Page S666]]

deduction for the taxable year which is equal to the amount
of the credit determined for the taxable year under section
45N(a).''.
(d) Clerical Amendment.--The table of sections for subpart
D of part IV of subchapter A of chapter 1 is amended by
adding at the end the following new item:

``Sec. 45N. Mine rescue team training credit.''.

(e) Effective Date.--The amendments made by this section
shall apply to taxable years beginning after December 31,
2005.
______